PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2138092
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2138092
Flow Cytometry Market by Technology (Cell, Bead-based), Product [Cell Analyzer, Sorter, Antibodies, Assays & Kits (Apoptosis), Software], Service, Detection (Spectral), Application (Clinical, Research), End User, Competition - Global Forecast to 2034
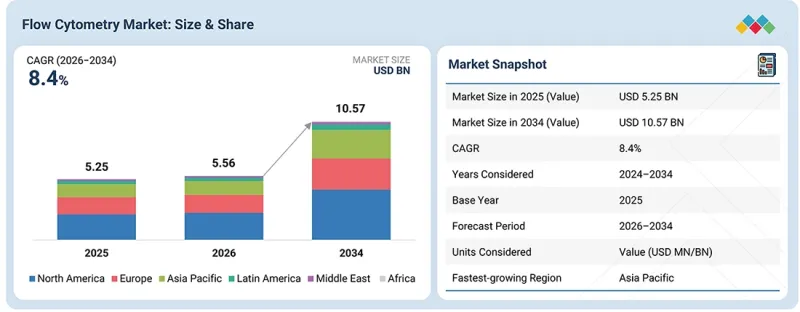
The flow cytometry market is expected to reach USD 10.57 billion by 2034 from USD 5.56 billion in 2026, at a CAGR of 8.4% during the forecast period. The market is expected to grow steadily during the forecast period, driven by increasing use of flow cytometry in immunology, oncology, hematology, drug discovery, cell and gene therapy, and clinical diagnostics. Technologies such as conventional flow cytometry, spectral flow cytometry, imaging/hybrid flow cytometry, and bead-based flow cytometry enable detailed analysis of cell phenotype, viability, apoptosis, cell cycle, intracellular proteins, cytokines, and other functional characteristics. These technologies support applications across cancer diagnostics, autoimmune disease assessment, stem cell research, in vitro toxicity testing, cell sorting, vaccine manufacturing, CGT manufacturing, and other biologics manufacturing.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2034 |
| Base Year | 2025 |
| Forecast Period | 2026-2034 |
| Units Considered | Value (USD billion) |
| Segments | Product, Technology, Detection Modality, Application, End User (Product), Service Type, and End User (Service) |
| Regions covered | North America, Europe, the Asia Pacific, Latin America, the Middle East, and Africa |
The growing use of high-parameter analyzers, spectral systems, complex antibody-dye conjugates, multiplex assays, and automated data analysis is further strengthening adoption across pharmaceutical, biotechnology, academic, clinical, and CRO/CDMO settings. In addition, recurring demand for antibodies, assays & kits, controls, calibration reagents, sheath fluids, and other consumables is supporting sustained market growth. However, the market continues to face challenges related to the high cost of advanced instruments, the complexity of multicolor panel design, the need for skilled operators, reagent standardization, and the interpretation of high-dimensional flow cytometry data.
"Bead-based flow cytometry segment is expected to grow at the highest CAGR during the forecast period."
The bead-based flow cytometry segment is projected to grow at the highest CAGR due to the increasing adoption of multiplex assays for simultaneous detection and quantification of multiple analytes from limited sample volumes. Bead-based platforms are increasingly used for cytokine profiling, biomarker analysis, immunoassays, and drug discovery studies, particularly in applications requiring high-throughput multiplex testing. The growing demand for efficient, scalable, and multiplexed analytical workflows across pharmaceutical, biotechnology, and research laboratories is driving segment growth.
"The reagents & consumables segment holds the largest share of the market."
The reagents & consumables segment accounts for the largest share of the flow cytometry market, primarily due to the recurring requirement for antibodies, antibody-dye conjugates, assays & kits, buffers, controls, calibration reagents, sheath fluids, and other consumables in routine flow cytometry workflows. These products are extensively used in immunophenotyping, cytokine detection, apoptosis and cell viability analysis, multiplex assays, and other cellular studies. Their high frequency of consumption across academic, clinical, pharmaceutical, biotechnology, and CRO/CDMO laboratories supports the segment's leading market position.
"The US is expected to grow at the highest CAGR during the forecast period."
The US is expected to grow at the highest CAGR in the flow cytometry market due to its strong presence of leading flow cytometry manufacturers, pharmaceutical & biotechnology companies, advanced research infrastructure, and high adoption of sophisticated cell analysis technologies across research and clinical settings. Rising use of flow cytometry in oncology, immunology, hematology, drug discovery, cell & gene therapy, and clinical diagnostics is driving market growth. High-parameter analyzers, spectral flow cytometry systems, cell sorters, antibody-dye conjugates, multiplex assays, and advanced data analysis solutions are increasingly used across pharmaceutical & biotechnology companies, academic & research institutes, hospitals & clinical testing laboratories, and CROs & CDMOs.
The primary interviews conducted for this report can be categorized as follows:
- By Respondent: Supply Side (70%) and Demand Side (30%)
- By Designation: Managers (45%), CXOs and Directors (30%), and Executives (25%)
- By Region: North America (40%), Europe (25%), Asia Pacific (25%), Latin America (5%), and the Middle East & Africa (5%)
BD (US), Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), Agilent Technologies, Inc. (US), Bio-Rad Laboratories, Inc. (US), Sony Corporation (Japan), Miltenyi Biotec (Germany), Enzo Biochem Inc. (US), Sysmex Corporation (Japan), Cytek Biosciences (US), BIOMERIEUX (France), Cytonome/ST LLC (US), Sartorius AG (Germany), Union Biometrica, Inc. (US), Takara Bio Inc. (Japan), Revvity (US), Charles River Laboratories (US), The Jackson Laboratory (US), Apogee Flow Systems Ltd. (UK), Stratedigm, Inc (US), Nova Biomedical (US), On-chip Biotechnologies Co., Ltd. Corporation (Japan), Precision Cell Systems (US), CytoBuoy (Netherlands), CUSABIO TECHNOLOGY LLC (US), De Novo Software (US), Altasciences (Canada), RayBiotech, Inc. (US), and KCAS Bio (US) are some of the key companies offering flow cytometry products and services.
Research Coverage
This research report categorizes the flow cytometry market by product {reagents & consumables [antibodies (unconjugated antibodies and antibody-dye conjugates), assays & kits (phenotyping assays & kits, cytokine detection assays & kits, multiplex assays & kits, apoptosis & cell viability assays, and other assays & kits) and other reagents & consumables], instruments [cell analyzers (high-plex/high-parameter analyzers, standard benchtop/mid-parameter analyzers, and compact/low-parameter analyzers), and cell sorters (high-range cell sorters, mid-range cell sorters, and low-range cell sorters)], software, and accessories}, technology (cell-based flow cytometry and bead-based flow cytometry), detection modality (conventional flow cytometry, spectral flow cytometry, and imaging/hybrid flow cytometry), application [research applications (drug discovery, stem cell research, in vitro toxicity testing, immunology, cell sorting, apoptosis, cell cycle analysis, cell viability, cell counting, and other research applications), clinical applications (cancer diagnostics, hematology, autoimmune diseases, organ transplantation, and other clinical applications), pharmaceutical & biotechnology applications, and industrial applications], product market by end user (academic & research institutes, hospitals & clinical testing laboratories, pharmaceutical & biotechnology companies, and CROs & CDMOs), service market by type (immunophenotyping services, cell sorting services, assay development services, and other services), service market by end user (academic & research institutes, hospitals & clinical testing laboratories, and pharmaceutical & biotechnology companies), and region (North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa).
The report's scope encompasses detailed information about the primary factors, including drivers, restraints, challenges, and opportunities, which influence the growth of the flow cytometry market. A comprehensive analysis of key industry players has been conducted to provide insights into their business overviews, product portfolios, key strategies, new product launches, acquisitions, and recent developments in the flow cytometry market. This report also includes a competitive analysis of emerging startups in the flow cytometry industry ecosystem.
Key Benefits of Buying the Report
The report will assist market leaders and new entrants by providing revenue estimates for the overall market and its subsegments. It will also help stakeholders better understand the competitive landscape and gain more insights to position their businesses effectively and develop suitable go-to-market strategies. This report will enable stakeholders to grasp the market's pulse and provide insights into key drivers, restraints, opportunities, and challenges.
The report provides insights into the following pointers:
- Analysis of key drivers (rising adoption of flow cytometry in oncology research and diagnostics, increasing demand for high-parameter and spectral flow cytometry for multiparameter cellular analysis, growing application of flow cytometry in cell and gene therapy development and manufacturing), restraints (high cost of advanced flow cytometers), opportunities (increasing adoption of flow cytometry in clinical diagnostics and biopharmaceutical quality control, growing demand for automated and AI-enabled flow cytometry for high-throughput and complex data analysis), and challenges (complexities related to reagent development) influencing the market growth
- Product Development/Innovation: Detailed insights into newly launched products and innovations in the flow cytometry market
- Market Development: Comprehensive information about lucrative markets and analysis of the market across varied regions
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the flow cytometry market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and products & services of leading players, BD (US), Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), Agilent Technologies, Inc. (US), Bio-Rad Laboratories, Inc. (US), Sony Corporation (Japan), Miltenyi Biotec (Germany), Enzo Biochem Inc. (US), Sysmex Corporation (Japan), Cytek Biosciences (US), and Revvity (US), among others, for the flow cytometry market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONS COVERED
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN FLOW CYTOMETRY MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 FLOW CYTOMETRY MARKET OVERVIEW
- 3.2 NORTH AMERICA: FLOW CYTOMETRY MARKET, BY PRODUCT & COUNTRY
- 3.3 FLOW CYTOMETRY MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 FLOW CYTOMETRY MARKET SHARE, BY TECHNOLOGY, 2026 VS. 2034 (%)
- 3.5 FLOW CYTOMETRY MARKET, BY OFFERING, 2024-2034 (USD MILLION)
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising adoption of flow cytometry in oncology research and diagnostics
- 4.2.1.2 Increasing demand for high-parameter and spectral flow cytometry for multiparameter cellular analysis
- 4.2.1.3 Growing applications in cell & gene therapy development and manufacturing
- 4.2.2 RESTRAINTS
- 4.2.2.1 High cost of advanced flow cytometers
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing adoption in clinical diagnostics and biopharmaceutical quality control
- 4.2.3.2 Growing demand for automated and AI-enabled flow cytometry for high-throughput and complex data analysis
- 4.2.4 CHALLENGES
- 4.2.4.1 Complexities related to reagent development
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.2 BARGAINING POWER OF SUPPLIERS
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 THREAT FROM SUBSTITUTES
- 5.1.5 THREAT FROM NEW ENTRANTS
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL HEALTHCARE INDUSTRY
- 5.2.4 TRENDS IN GLOBAL BIOTECH INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 ROLE OF PLAYERS IN ECOSYSTEM
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND, BY KEY PLAYER, 2023-2025
- 5.5.2 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 9027.50)
- 5.6.2 EXPORT SCENARIO (HS CODE 9027.50)
- 5.7 KEY CONFERENCES & EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.9 INVESTMENT & FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 AI-ASSISTED FLOW CYTOMETRY SUPPORTS MEASURABLE RESIDUAL DISEASE ASSESSMENT FOR CHRONIC LYMPHOCYTIC LEUKEMIA
- 5.10.2 SPECTRAL FLOW CYTOMETRY EXPANDS HIGH-DIMENSIONAL IMMUNE PROFILING
- 5.10.3 NO-WASH FLOW CYTOMETRY IMPROVES CAR-T CELL MONITORING
- 5.11 IMPACT OF 2025 US TARIFFS-FLOW CYTOMETRY MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
- 5.11.5.1 Academic & Research Institutes
- 5.11.5.2 Hospitals & Clinical Testing Laboratories
- 5.11.5.3 Pharmaceutical & Biotechnology Companies
- 5.11.5.4 CROs & CDMOs
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Mass cytometry
- 6.1.1.2 Microfluidics
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Single-cell analysis
- 6.1.2.2 Spatial analysis
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Single-cell RNA sequencing
- 6.1.3.2 High-content screening
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY ROADMAP
- 6.3 PATENT ANALYSIS
- 6.3.1 METHODOLOGY
- 6.3.2 NUMBER OF PATENTS FILED, BY DOCUMENT TYPE
- 6.3.3 LIST OF KEY PATENTS
- 6.4 FUTURE APPLICATIONS
- 6.5 IMPACT OF AI/GEN AI ON FLOW CYTOMETRY MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES IN AI-ENABLED FLOW CYTOMETRY DATA ANALYSIS AND INTERPRETATION
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN FLOW CYTOMETRY MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT AI-INTEGRATED FLOW CYTOMETRY SOLUTIONS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Rest of the world
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA, BY END USER
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
9 FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 REAGENTS & CONSUMABLES
- 9.2.1 ANTIBODIES
- 9.2.1.1 Unconjugated Antibodies
- 9.2.1.1.1 Expanding assay customization and biomarker validation to drive market
- 9.2.1.2 Antibody Dye Conjugates
- 9.2.1.2.1 Expanding multicolor and spectral workflows to boost market
- 9.2.1.1 Unconjugated Antibodies
- 9.2.2 ASSAYS & KITS
- 9.2.2.1 Phenotyping Assays & Kits
- 9.2.2.1.1 Standardized immune profiling and expanding cell therapy characterization to drive market
- 9.2.2.2 Cytokine Detection Assays & Kits
- 9.2.2.2.1 Growing emphasis on functional immune-response assessment to boost market
- 9.2.2.3 Multiplex Assays & Kits
- 9.2.2.3.1 Broader biomarker profiling and sample-efficient testing to drive market
- 9.2.2.4 Apoptosis & Cell Viability Assays & Kits
- 9.2.2.4.1 Expanding drug-response testing and cell quality assessment to boost market
- 9.2.2.5 Other Assays & Kits
- 9.2.2.1 Phenotyping Assays & Kits
- 9.2.3 OTHER REAGENTS & CONSUMABLES
- 9.2.1 ANTIBODIES
- 9.3 INSTRUMENTS
- 9.3.1 CELL ANALYZERS
- 9.3.1.1 High-Plex/ High-Parameter Analyzers
- 9.3.1.1.1 Expanding high-dimensional immune profiling and biomarker research to accelerate market growth
- 9.3.1.2 Standard Benchtop/ Mid-Parameter Analyzers
- 9.3.1.2.1 Increasing demand for accessible, compact, and simplified routine cell analysis to drive market
- 9.3.1.3 Compact/Low-Parameter Analyzers
- 9.3.1.3.1 Decentralized routine testing and demand for simpler cell analysis to expand adoption
- 9.3.1.1 High-Plex/ High-Parameter Analyzers
- 9.3.2 CELL SORTERS
- 9.3.2.1 High-Range Cell Sorters
- 9.3.2.1.1 High-dimensional research and rare-cell recovery to drive market
- 9.3.2.2 Mid-Range Cell Sorters
- 9.3.2.2.1 Expanding in-house research workflows and demand for flexible, cost-efficient cell purification to drive market
- 9.3.2.3 Low-Range Cell Sorters
- 9.3.2.3.1 Affordability, ease of use, and decentralized access to boost growth
- 9.3.2.1 High-Range Cell Sorters
- 9.3.1 CELL ANALYZERS
- 9.4 SOFTWARE
- 9.4.1 RISING DATA COMPLEXITY AND AUTOMATION REQUIREMENTS TO DRIVE MARKET
- 9.5 ACCESSORIES
- 9.5.1 EXPANDING INSTRUMENT INSTALLATIONS, TECHNOLOGY UPGRADES, AND CALIBRATION REQUIREMENTS TO DRIVE MARKET
10 FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY
- 10.1 INTRODUCTION
- 10.2 CELL-BASED FLOW CYTOMETRY
- 10.2.1 RISING DEMAND FOR HIGH-PARAMETER CELLULAR ANALYSIS TO BOOST MARKET GROWTH
- 10.3 BEAD-BASED FLOW CYTOMETRY
- 10.3.1 GROWING DEMAND FOR MULTIPLEX BIOMARKER ANALYSIS TO FUEL SEGMENT
11 FLOW CYTOMETRY PRODUCTS MARKET, BY DETECTION MODALITY
- 11.1 INTRODUCTION
- 11.2 CONVENTIONAL FLOW CYTOMETRY
- 11.2.1 ESTABLISHED FILTER-BASED DETECTION, VALIDATED ASSAYS, AND ROUTINE CLINICAL WORKFLOWS TO DRIVE MARKET
- 11.3 SPECTRAL FLOW CYTOMETRY
- 11.3.1 HIGH-PARAMETER ANALYSIS, SPECTRAL UNMIXING, AND EXPANDING PANEL COMPLEXITY TO PROPEL GROWTH
- 11.4 IMAGING/HYBRID FLOW CYTOMETRY
- 11.4.1 DEMAND FOR SIMULTANEOUS MORPHOLOGICAL AND FLUORESCENCE-BASED CHARACTERIZATION TO DRIVE MARKET
12 FLOW CYTOMETRY PRODUCTS MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.2 ACADEMIC & RESEARCH INSTITUTES
- 12.2.1 EXPANDING RESEARCH INFRASTRUCTURE TO BOOST MARKET GROWTH
- 12.3 HOSPITALS & CLINICAL TESTING LABORATORIES
- 12.3.1 EXPANDING CLINICAL DIAGNOSTICS AND DISEASE MONITORING TO FUEL SEGMENT
- 12.4 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 12.4.1 EXPANDING DRUG DISCOVERY AND CELL THERAPY PIPELINES TO DRIVE MARKET
- 12.5 CROS & CDMOS
- 12.5.1 RISING OUTSOURCING OF COMPLEX BIOANALYTICAL WORKFLOWS TO DRIVE GROWTH
13 FLOW CYTOMETRY SERVICES MARKET, BY TYPE
- 13.1 INTRODUCTION
- 13.2 IMMUNOPHENOTYPING SERVICES
- 13.2.1 EXPANDING BIOMARKER-DRIVEN TRIALS AND ADVANCED THERAPIES TO BOOST MARKET GROWTH
- 13.3 CELL SORTING SERVICES
- 13.3.1 INCREASING DEMAND FOR RARE-CELL ISOLATION, SINGLE-CELL WORKFLOWS, AND ADVANCED SPECTRAL SORTING TO FUEL SEGMENT
- 13.4 ASSAY DEVELOPMENT SERVICES
- 13.4.1 INCREASING THERAPEUTIC COMPLEXITY AND DEMAND FOR VALIDATED, CUSTOMIZED HIGH-PARAMETER ASSAYS TO DRIVE MARKET
- 13.5 OTHER SERVICES
14 FLOW CYTOMETRY SERVICES MARKET, BY END USER
- 14.1 INTRODUCTION
- 14.2 ACADEMIC & RESEARCH INSTITUTES
- 14.2.1 EXPANDING ACCESS TO SPECIALIZED CYTOMETRY EXPERTISE TO BOOST MARKET GROWTH
- 14.3 HOSPITALS & CLINICAL TESTING LABORATORIES
- 14.3.1 RISING DEMAND FOR SPECIALIZED CLINICAL TESTING TO FUEL SEGMENT
- 14.4 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 14.4.1 EXPANDING OUTSOURCING OF COMPLEX BIOANALYTICAL TESTING TO DRIVE MARKET
15 FLOW CYTOMETRY MARKET, BY APPLICATION
- 15.1 INTRODUCTION
- 15.2 RESEARCH APPLICATIONS
- 15.2.1 DRUG DISCOVERY
- 15.2.1.1 High-throughput cellular screening and deeper phenotypic analysis to boost market growth
- 15.2.2 STEM CELL RESEARCH
- 15.2.2.1 Expanding iPSC research to drive market
- 15.2.3 IN VITRO TOXICITY TESTING
- 15.2.3.1 Growing mechanistic safety testing to drive market
- 15.2.4 IMMUNOLOGY
- 15.2.4.1 High-dimensional immune profiling to aid market growth
- 15.2.5 CELL SORTING
- 15.2.5.1 Rare-cell isolation and integration with downstream single-cell analysis to drive market
- 15.2.6 APOPTOSIS
- 15.2.6.1 Expanding cancer therapy research to propel market growth
- 15.2.7 CELL CYCLE ANALYSIS
- 15.2.7.1 Expanding cell cycle-targeted drug research to drive market
- 15.2.8 CELL VIABILITY
- 15.2.8.1 Growing cell-based research and increasing emphasis on standardized cell quality assessment to drive market growth
- 15.2.9 CELL COUNTING
- 15.2.9.1 Increasing demand for accurate population-specific quantification to drive market
- 15.2.10 OTHER RESEARCH APPLICATIONS
- 15.2.1 DRUG DISCOVERY
- 15.3 CLINICAL APPLICATIONS
- 15.3.1 CANCER DIAGNOSTICS
- 15.3.1.1 High-parameter cancer immunophenotyping and expanding residual disease assessment to drive market
- 15.3.2 HEMATOLOGY
- 15.3.2.1 Expanding stem cell transplantation and specialized blood cell assessment to propel market growth
- 15.3.3 AUTOIMMUNE DISEASES
- 15.3.3.1 Advanced immune profiling and biomarker-based patient stratification to drive market
- 15.3.4 ORGAN TRANSPLANTATION
- 15.3.4.1 Increasing demand for sensitive donor-recipient compatibility assessment to drive market
- 15.3.5 OTHER CLINICAL APPLICATIONS
- 15.3.1 CANCER DIAGNOSTICS
- 15.4 PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS
- 15.4.1 HIGH-THROUGHPUT DRUG DISCOVERY AND EXPANDING ADVANCED THERAPY DEVELOPMENT TO DRIVE MARKET
- 15.5 INDUSTRIAL APPLICATIONS
- 15.5.1 DEMAND FOR RAPID MICROBIAL QUALITY ASSESSMENT TO DRIVE MARKET
16 FLOW CYTOMETRY MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 Advanced biomedical research and expanding cell therapy development to drive market
- 16.2.2 CANADA
- 16.2.2.1 Public research investment and expanding advanced cellular research to boost market growth
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 GERMANY
- 16.3.1.1 Research infrastructure investment and growing high-dimensional cellular studies to aid market growth
- 16.3.2 UK
- 16.3.2.1 Research infrastructure funding and expanding translational science to spur market growth
- 16.3.3 FRANCE
- 16.3.3.1 Public research infrastructure investment and advanced oncology research to fuel market growth
- 16.3.4 ITALY
- 16.3.4.1 Research infrastructure modernization to boost market growth
- 16.3.5 SPAIN
- 16.3.5.1 Advanced hematology diagnostics and expanding translational research to augment market growth
- 16.3.6 REST OF EUROPE
- 16.3.1 GERMANY
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Expanding cell therapy research, clinical adoption, and localized instrument manufacturing to support market growth
- 16.4.2 JAPAN
- 16.4.2.1 Regenerative medicine leadership and investment in advanced shared cytometry infrastructure to drive market
- 16.4.3 INDIA
- 16.4.3.1 Expanding biopharma research and access to advanced cytometry infrastructure to drive market
- 16.4.4 AUSTRALIA
- 16.4.4.1 Research infrastructure modernization and expanding precision medicine to propel market growth
- 16.4.5 SOUTH KOREA
- 16.4.5.1 Increasing adoption of high-dimensional cellular analysis to spur market growth
- 16.4.6 SINGAPORE
- 16.4.6.1 Biomedical research investment and localization of advanced cytometry manufacturing to drive market
- 16.4.7 INDONESIA
- 16.4.7.1 Healthcare modernization and expanding biomedical research to drive market
- 16.4.8 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 LATIN AMERICA
- 16.5.1 BRAZIL
- 16.5.1.1 Expanding advanced biomedical research and modernization of shared cytometry infrastructure to boost market growth
- 16.5.2 MEXICO
- 16.5.2.1 Expanding shared research infrastructure to fuel market growth
- 16.5.3 REST OF LATIN AMERICA
- 16.5.1 BRAZIL
- 16.6 MIDDLE EAST
- 16.6.1 GCC COUNTRIES
- 16.6.1.1 Saudi Arabia
- 16.6.1.1.1 Advanced hematology diagnostics to boost market growth
- 16.6.1.2 UAE
- 16.6.1.2.1 Expanding advanced diagnostic infrastructure to drive market
- 16.6.1.3 Rest of GCC countries
- 16.6.1.1 Saudi Arabia
- 16.6.2 REST OF MIDDLE EAST
- 16.6.1 GCC COUNTRIES
- 16.7 AFRICA
- 16.7.1 PUBLIC HEALTH INVESTMENT AND EXPANDING BIOMEDICAL RESEARCH INFRASTRUCTURE TO PROPEL MARKET GROWTH
17 COMPETITIVE LANDSCAPE
- 17.1 INTRODUCTION
- 17.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021-2025
- 17.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN FLOW CYTOMETRY MARKET, JANUARY 2023-JULY 2026
- 17.3 REVENUE ANALYSIS, 2021-2025
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.5 BRAND COMPARISON
- 17.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.6.1 STARS
- 17.6.2 EMERGING LEADERS
- 17.6.3 PERVASIVE PLAYERS
- 17.6.4 PARTICIPANTS
- 17.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.6.5.1 Company footprint
- 17.6.5.2 Region footprint
- 17.6.5.3 Product & service footprint
- 17.6.5.4 Technology footprint
- 17.6.5.5 Application footprint
- 17.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.7.1 PROGRESSIVE COMPANIES
- 17.7.2 RESPONSIVE COMPANIES
- 17.7.3 DYNAMIC COMPANIES
- 17.7.4 STARTING BLOCKS
- 17.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 17.7.5.1 Detailed list of key startup/SME players
- 17.7.5.2 Competitive benchmarking of startups/SMEs
- 17.8 COMPANY VALUATION AND FINANCIAL METRICS
- 17.8.1 COMPANY VALUATION
- 17.8.2 FINANCIAL METRICS
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 PRODUCT LAUNCHES
- 17.9.2 DEALS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 BD
- 18.1.1.1 Business overview
- 18.1.1.2 Products/services/solutions offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Product launches and product enhancements
- 18.1.1.3.2 Deals
- 18.1.1.4 MnM view
- 18.1.1.4.1 Right to win
- 18.1.1.4.2 Strategic choices
- 18.1.1.4.3 Weaknesses & competitive threats
- 18.1.2 DANAHER CORPORATION
- 18.1.2.1 Business overview
- 18.1.2.2 Products/services/solutions offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Product launches
- 18.1.2.3.2 Deals
- 18.1.2.4 MnM view
- 18.1.2.4.1 Right to win
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses & competitive threats
- 18.1.3 THERMO FISHER SCIENTIFIC INC.
- 18.1.3.1 Business overview
- 18.1.3.2 Products/services/solutions offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product launches
- 18.1.3.4 MnM view
- 18.1.3.4.1 Right to win
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses & competitive threats
- 18.1.4 REVVITY
- 18.1.4.1 Business overview
- 18.1.4.2 Products/services/solutions offered
- 18.1.4.3 MnM view
- 18.1.4.3.1 Right to win
- 18.1.4.3.2 Strategic choices
- 18.1.4.3.3 Weaknesses & competitive threats
- 18.1.5 AGILENT TECHNOLOGIES, INC.
- 18.1.5.1 Business overview
- 18.1.5.2 Products/services/solutions offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Product launches
- 18.1.6 SONY GROUP CORPORATION
- 18.1.6.1 Business overview
- 18.1.6.2 Products/services/solutions offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Product launches
- 18.1.6.3.2 Deals
- 18.1.7 BIO-RAD LABORATORIES, INC.
- 18.1.7.1 Business overview
- 18.1.7.2 Products/Services/Solutions offered
- 18.1.7.3 Recent developments
- 18.1.7.3.1 Product launches
- 18.1.8 MILTENYI BIOTEC
- 18.1.8.1 Business overview
- 18.1.8.2 Products/services/solutions offered
- 18.1.9 ENZO BIOCHEM, INC.
- 18.1.9.1 Business overview
- 18.1.9.2 Products/services/solutions offered
- 18.1.10 SYSMEX CORPORATION
- 18.1.10.1 Business overview
- 18.1.10.2 Products/services/solutions offered
- 18.1.11 CYTEK BIOSCIENCES, INC.
- 18.1.11.1 Business overview
- 18.1.11.2 Products/services/solutions offered
- 18.1.11.3 Recent developments
- 18.1.11.3.1 Product launches
- 18.1.11.3.2 Deals
- 18.1.12 BIOMERIEUX
- 18.1.12.1 Business overview
- 18.1.12.2 Products/services/solutions offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Deals
- 18.1.13 CYTONOME/ST, LLC
- 18.1.13.1 Business overview
- 18.1.13.2 Products/services/solutions offered
- 18.1.14 SARTORIUS AG
- 18.1.14.1 Business overview
- 18.1.14.2 Products/services/solutions offered
- 18.1.14.3 Recent developments
- 18.1.14.3.1 Product launches
- 18.1.15 UNION BIOMETRICA, INC.
- 18.1.15.1 Business overview
- 18.1.15.2 Products/services/solutions offered
- 18.1.16 TAKARA BIO INC.
- 18.1.16.1 Business overview
- 18.1.16.2 Products/services/solutions offered
- 18.1.17 CHARLES RIVER LABORATORIES INTERNATIONAL, INC.
- 18.1.17.1 Business overview
- 18.1.17.2 Products/services/solutions offered
- 18.1.18 THE JACKSON LABORATORY
- 18.1.18.1 Business overview
- 18.1.18.2 Products/services/solutions offered
- 18.1.1 BD
- 18.2 OTHER PLAYERS
- 18.2.1 APOGEE FLOW SYSTEMS LTD
- 18.2.2 STRATEDIGM, INC.
- 18.2.3 NOVA BIOMEDICAL CORPORATION
- 18.2.4 ON-CHIP BIOTECHNOLOGIES CO., LTD.
- 18.2.5 PRECISION CELL SYSTEMS, INC.
- 18.2.6 CYTOBUOY B.V.
- 18.2.7 CUSABIO TECHNOLOGY LLC
- 18.2.8 DE NOVO SOFTWARE
- 18.2.9 ALTASCIENCES
- 18.2.10 RAYBIOTECH, INC.
- 18.2.11 KCAS BIO
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH DATA
- 19.1.1 SECONDARY DATA
- 19.1.1.1 Key data from secondary sources
- 19.1.2 PRIMARY DATA
- 19.1.2.1 Key data from primary sources
- 19.1.2.2 Key primary participants
- 19.1.2.3 Breakdown of primary interviews
- 19.1.2.4 Key industry insights
- 19.1.1 SECONDARY DATA
- 19.2 MARKET SIZE ESTIMATION
- 19.2.1 GLOBAL FLOW CYTOMETRY MARKET ESTIMATION, 2025
- 19.2.2 SEGMENTAL MARKET SIZE ESTIMATION
- 19.3 MARKET GROWTH RATE PROJECTIONS
- 19.4 DATA TRIANGULATION
- 19.5 FACTOR ANALYSIS
- 19.6 RESEARCH ASSUMPTIONS
- 19.7 RESEARCH LIMITATIONS AND RISK ASSESSMENT
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS
List of Tables
- TABLE 1 FLOW CYTOMETRY MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 FLOW CYTOMETRY MARKET, BY OFFERING, 2024-2034 (USD MILLION)
- TABLE 3 FLOW CYTOMETRY MARKET: IMPACT ANALYSIS OF MARKET DYNAMICS
- TABLE 4 FLOW CYTOMETRY MARKET: PORTER'S FIVE FORCES
- TABLE 5 FLOW CYTOMETRY MARKET: ROLE OF PLAYERS IN ECOSYSTEM
- TABLE 6 AVERAGE SELLING PRICE TREND OF INSTRUMENTS, BY KEY PLAYER, 2023-2025 (USD)
- TABLE 7 AVERAGE SELLING PRICE TREND OF REAGENTS & CONSUMABLES, BY KEY PLAYER, 2023-2025 (USD)
- TABLE 8 AVERAGE SELLING PRICE TREND OF INSTRUMENTS, BY REGION, 2023-2025 (USD)
- TABLE 9 AVERAGE SELLING PRICE TREND OF REAGENTS & CONSUMABLES, BY REGION, 2023-2025 (USD)
- TABLE 10 IMPORT DATA FOR HS CODE 9027.50-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 EXPORT DATA FOR HS CODE 9027.50-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 12 FLOW CYTOMETRY MARKET: LIST OF KEY CONFERENCES & EVENTS, JANUARY 2026-SEPTEMBER 2027
- TABLE 13 RECIPROCAL TARIFF RATES ADJUSTED BY US
- TABLE 14 CRITICAL COMPONENTS LIKELY EXPOSED TO TARIFF CHANGES
- TABLE 15 NUMBER OF PATENTS FILED, BY DOCUMENT TYPE, 2015-2025
- TABLE 16 LIST OF KEY PATENTS IN FLOW CYTOMETRY MARKET, 2023-2025
- TABLE 17 CASE STUDIES OF AI IMPLEMENTATION IN FLOW CYTOMETRY MARKET
- TABLE 18 CLIENTS' READINESS TO ADOPT AI-INTEGRATED FLOW CYTOMETRY SOLUTIONS
- TABLE 19 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS
- TABLE 25 KEY BUYING CRITERIA, BY END USER
- TABLE 26 FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 27 FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 28 FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 29 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 30 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 31 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 32 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 33 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 34 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 35 FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 36 FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 37 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 38 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 39 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 40 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 41 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 42 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 43 FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 44 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 45 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 46 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 47 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 48 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 49 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR UNCONJUGATED ANTIBODIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 50 FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 51 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 52 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 53 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 54 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 55 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 56 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODY DYE CONJUGATES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 57 FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 58 FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 59 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 60 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 61 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 62 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 63 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 64 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 65 FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 66 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 67 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 68 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 69 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 70 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 71 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR PHENOTYPING ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 72 FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 73 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 74 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 75 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 76 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 77 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 78 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CYTOKINE DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 79 FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 80 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 81 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 82 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 83 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 84 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 85 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR MULTIPLEX DETECTION ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 86 FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 87 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 88 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 89 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 90 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 91 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 92 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR APOPTOSIS & CELL VIABILITY ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 93 FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 94 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 95 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 96 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 97 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 98 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 99 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER ASSAYS & KITS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 100 FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 101 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 102 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 103 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 104 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 105 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 106 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR OTHER REAGENTS & CONSUMABLES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 107 FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 108 FLOW CYTOMETRY PRODUCT MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (UNITS)
- TABLE 109 FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 110 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 111 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 112 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 113 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 114 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 115 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 116 FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 117 FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 118 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 119 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 120 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 121 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 122 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 123 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 124 FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 125 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 126 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 127 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 128 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 129 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 130 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-PLEX/HIGH-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 131 FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 132 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 133 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 134 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 135 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 136 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 137 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR STANDARD BENCHTOP/MID-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 138 FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 139 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 140 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 141 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 142 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 143 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 144 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR COMPACT/LOW-PARAMETER ANALYZERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 145 FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 146 FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 147 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 148 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 149 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 150 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 151 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 152 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 153 FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 154 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 155 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 156 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 157 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 158 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 159 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR HIGH-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 160 FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 161 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 162 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 163 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 164 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 165 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 166 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR MID-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 167 FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 168 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 169 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 170 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 171 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 172 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 173 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR LOW-RANGE CELL SORTERS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 174 FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY REGION, 2024-2034 (USD MILLION)
- TABLE 175 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 176 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 177 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 178 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 179 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY REGION, 2024-2034 (USD MILLION)
- TABLE 180 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR SOFTWARE, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 181 FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 182 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 183 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 184 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 185 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 186 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 187 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ACCESSORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 188 FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 189 FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 190 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 191 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 192 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 193 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 194 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 195 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 196 FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 197 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 198 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 199 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 200 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 201 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 202 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR BEAD-BASED FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 203 FLOW CYTOMETRY PRODUCTS MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 204 FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 205 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 206 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 207 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 208 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 209 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 210 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CONVENTIONAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 211 FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 212 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 213 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 214 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 215 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 216 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 217 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR SPECTRAL FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 218 FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 219 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 220 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 221 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 222 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 223 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 224 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR IMAGING/HYBRID FLOW CYTOMETRY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 225 FLOW CYTOMETRY PRODUCTS MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 226 FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 227 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 228 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 229 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 230 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 231 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 232 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 233 FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 234 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 235 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 236 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 237 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 238 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 239 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 240 FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 241 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 242 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 243 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 244 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 245 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 246 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 247 FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 248 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 249 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 250 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 251 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 252 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 253 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CROS & CDMOS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 254 FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 255 FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 256 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 257 EUROPE: FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 258 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 259 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 260 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 261 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET FOR IMMUNOPHENOTYPING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 262 FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 263 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 264 EUROPE: FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 265 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 266 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 267 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 268 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET FOR CELL SORTING SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 269 FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 270 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 271 EUROPE: FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 272 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 273 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 274 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 275 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET FOR ASSAY DEVELOPMENT SERVICES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 276 OTHER FLOW CYTOMETRY SERVICES MARKET, BY REGION, 2024-2034 (USD MILLION)
- TABLE 277 NORTH AMERICA: OTHER FLOW CYTOMETRY SERVICES MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 278 EUROPE: OTHER FLOW CYTOMETRY SERVICES MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 279 ASIA PACIFIC: OTHER FLOW CYTOMETRY SERVICES MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 280 LATIN AMERICA: OTHER FLOW CYTOMETRY SERVICES MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 281 MIDDLE EAST: OTHER FLOW CYTOMETRY SERVICES MARKET, BY REGION, 2024-2034 (USD MILLION)
- TABLE 282 GCC COUNTRIES: OTHER FLOW CYTOMETRY SERVICES MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 283 FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 284 FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 285 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 286 EUROPE: FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 287 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 288 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 289 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 290 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET FOR ACADEMIC & RESEARCH INSTITUTES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 291 FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 292 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 293 EUROPE: FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 294 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 295 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 296 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 297 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET FOR HOSPITALS & CLINICAL TESTING LABORATORIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 298 FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 299 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 300 EUROPE: FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 301 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 302 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 303 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 304 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 305 FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 306 FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 307 FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 308 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 309 EUROPE: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 310 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 311 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 312 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 313 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 314 FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 315 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 316 EUROPE: FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 317 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 318 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 319 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 320 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR DRUG DISCOVERY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 321 FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY REGION, 2024-2034 (USD MILLION)
- TABLE 322 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 323 EUROPE: FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 324 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 325 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 326 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY REGION, 2024-2034 (USD MILLION)
- TABLE 327 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR STEM CELL RESEARCH, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 328 FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY REGION, 2024-2034 (USD MILLION)
- TABLE 329 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 330 EUROPE: FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 331 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 332 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 333 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY REGION, 2024-2034 (USD MILLION)
- TABLE 334 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR IN VITRO TOXICITY TESTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 335 FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 336 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 337 EUROPE: FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 338 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 339 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 340 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 341 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR IMMUNOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 342 FLOW CYTOMETRY MARKET FOR CELL SORTING, BY REGION, 2024-2034 (USD MILLION)
- TABLE 343 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CELL SORTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 344 EUROPE: FLOW CYTOMETRY MARKET FOR CELL SORTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 345 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CELL SORTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 346 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CELL SORTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 347 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CELL SORTING, BY REGION, 2024-2034 (USD MILLION)
- TABLE 348 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CELL SORTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 349 FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 350 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 351 EUROPE: FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 352 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 353 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 354 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 355 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR APOPTOSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 356 FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 357 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 358 EUROPE: FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 359 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 360 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 361 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 362 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CELL CYCLE ANALYSIS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 363 FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 364 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 365 EUROPE: FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 366 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 367 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 368 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 369 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CELL VIABILITY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 370 FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY REGION, 2024-2034 (USD MILLION)
- TABLE 371 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 372 EUROPE: FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 373 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 374 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 375 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY REGION, 2024-2034 (USD MILLION)
- TABLE 376 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CELL COUNTING, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 377 FLOW CYTOMETRY MARKET FOR OTHER RESEARCH APPLICATIONS, BY REGION, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 378 EUROPE: FLOW CYTOMETRY MARKET FOR OTHER RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 379 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR OTHER RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 380 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR OTHER RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 381 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR OTHER RESEARCH APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 382 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR OTHER RESEARCH APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 383 FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 384 FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 385 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 386 EUROPE: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 387 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 388 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 389 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 390 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 391 FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 392 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 393 EUROPE: FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 394 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 395 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 396 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 397 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CANCER DIAGNOSTICS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 398 FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 399 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 400 EUROPE: FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 401 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 402 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 403 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY REGION, 2024-2034 (USD MILLION)
- TABLE 404 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 405 FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 406 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 407 EUROPE: FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 408 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 409 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 410 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY REGION, 2024-2034 (USD MILLION)
- TABLE 411 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 412 FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY REGION, 2024-2034 (USD MILLION)
- TABLE 413 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 414 EUROPE: FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 415 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 416 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 417 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY REGION, 2024-2034 (USD MILLION)
- TABLE 418 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR ORGAN TRANSPLANTATION, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 419 FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 420 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 421 EUROPE: FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 422 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 423 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 424 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 425 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR OTHER CLINICAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 426 FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 427 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 428 EUROPE: FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 429 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 430 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 431 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 432 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 433 FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 434 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 435 EUROPE: FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 436 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 437 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 438 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY REGION, 2024-2034 (USD MILLION)
- TABLE 439 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR INDUSTRIAL APPLICATIONS, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 440 FLOW CYTOMETRY MARKET, BY REGION, 2024-2034 (USD MILLION)
- TABLE 441 NORTH AMERICA: FLOW CYTOMETRY MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 442 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 443 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 444 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 445 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 446 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 447 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 448 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 449 NORTH AMERICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 450 NORTH AMERICA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 451 NORTH AMERICA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 452 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 453 NORTH AMERICA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 454 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 455 NORTH AMERICA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 456 NORTH AMERICA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 457 US: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 458 US: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 459 US: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 460 US: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 461 US: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 462 US: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 463 US: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 464 US: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 465 US: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 466 US: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 467 US: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 468 US: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 469 US: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 470 US: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 471 US: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 472 CANADA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 473 CANADA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 474 CANADA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 475 CANADA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 476 CANADA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 477 CANADA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 478 CANADA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 479 CANADA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 480 CANADA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 481 CANADA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 482 CANADA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 483 CANADA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 484 CANADA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 485 CANADA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 486 CANADA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 487 EUROPE: FLOW CYTOMETRY MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 488 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 489 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 490 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 491 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 492 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 493 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 494 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 495 EUROPE: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 496 EUROPE: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 497 EUROPE: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 498 EUROPE: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 499 EUROPE: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 500 EUROPE: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 501 EUROPE: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 502 EUROPE: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 503 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 504 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 505 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 506 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 507 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 508 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 509 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 510 GERMANY: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 511 GERMANY: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 512 GERMANY: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 513 GERMANY: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 514 GERMANY: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 515 GERMANY: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 516 GERMANY: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 517 GERMANY: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 518 UK: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 519 UK: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 520 UK: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 521 UK: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 522 UK: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 523 UK: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 524 UK: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 525 UK: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 526 UK: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 527 UK: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 528 UK: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 529 UK: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 530 UK: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 531 UK: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 532 UK: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 533 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 534 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 535 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 536 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 537 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 538 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 539 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 540 FRANCE: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 541 FRANCE: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 542 FRANCE: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 543 FRANCE: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 544 FRANCE: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 545 FRANCE: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 546 FRANCE: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 547 FRANCE: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 548 ITALY: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 549 ITALY: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 550 ITALY: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 551 ITALY: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 552 ITALY: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 553 ITALY: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 554 ITALY: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 555 ITALY: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 556 ITALY: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 557 ITALY: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 558 ITALY: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 559 ITALY: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 560 ITALY: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 561 ITALY: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 562 ITALY: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 563 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 564 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 565 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 566 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 567 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 568 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 569 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 570 SPAIN: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 571 SPAIN: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 572 SPAIN: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 573 SPAIN: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 574 SPAIN: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 575 SPAIN: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 576 SPAIN: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 577 SPAIN: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 578 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 579 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 580 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 581 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 582 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 583 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 584 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 585 REST OF EUROPE: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 586 REST OF EUROPE: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 587 REST OF EUROPE: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 588 REST OF EUROPE: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 589 REST OF EUROPE: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 590 REST OF EUROPE: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 591 REST OF EUROPE: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 592 REST OF EUROPE: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 593 ASIA PACIFIC: FLOW CYTOMETRY MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 594 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 595 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 596 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 597 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 598 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 599 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 600 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 601 ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 602 ASIA PACIFIC: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 603 ASIA PACIFIC: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 604 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 605 ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 606 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 607 ASIA PACIFIC: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 608 ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 609 CHINA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 610 CHINA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 611 CHINA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 612 CHINA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 613 CHINA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 614 CHINA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 615 CHINA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 616 CHINA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 617 CHINA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 618 CHINA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 619 CHINA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 620 CHINA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 621 CHINA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 622 CHINA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 623 CHINA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 624 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 625 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 626 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 627 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 628 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 629 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 630 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 631 JAPAN: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 632 JAPAN: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 633 JAPAN: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 634 JAPAN: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 635 JAPAN: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 636 JAPAN: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 637 JAPAN: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 638 JAPAN: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 639 INDIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 640 INDIA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 641 INDIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 642 INDIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 643 INDIA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 644 INDIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 645 INDIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 646 INDIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 647 INDIA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 648 INDIA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 649 INDIA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 650 INDIA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 651 INDIA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 652 INDIA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 653 INDIA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 654 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 655 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 656 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 657 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 658 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 659 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 660 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 661 AUSTRALIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 662 AUSTRALIA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 663 AUSTRALIA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 664 AUSTRALIA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 665 AUSTRALIA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 666 AUSTRALIA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 667 AUSTRALIA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 668 AUSTRALIA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 669 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 670 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 671 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 672 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 673 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 674 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 675 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 676 SOUTH KOREA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 677 SOUTH KOREA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 678 SOUTH KOREA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 679 SOUTH KOREA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 680 SOUTH KOREA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 681 SOUTH KOREA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 682 SOUTH KOREA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 683 SOUTH KOREA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 684 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 685 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 686 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 687 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 688 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 689 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 690 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 691 SINGAPORE: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 692 SINGAPORE: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 693 SINGAPORE: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 694 SINGAPORE: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 695 SINGAPORE: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 696 SINGAPORE: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 697 SINGAPORE: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 698 SINGAPORE: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 699 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 700 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 701 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 702 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 703 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 704 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 705 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 706 INDONESIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 707 INDONESIA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 708 INDONESIA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 709 INDONESIA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 710 INDONESIA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 711 INDONESIA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 712 INDONESIA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 713 INDONESIA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 714 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 715 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 716 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 717 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 718 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 719 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 720 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 721 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 722 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 723 REST OF ASIA PACIFIC: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 724 REST OF ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 725 REST OF ASIA PACIFIC: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 726 REST OF ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 727 REST OF ASIA PACIFIC: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 728 REST OF ASIA PACIFIC: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 729 LATIN AMERICA: FLOW CYTOMETRY MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 730 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 731 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 732 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 733 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 734 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 735 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 736 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 737 LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 738 LATIN AMERICA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 739 LATIN AMERICA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 740 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 741 LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 742 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 743 LATIN AMERICA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 744 LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 745 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 746 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 747 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 748 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 749 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 750 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 751 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 752 BRAZIL: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 753 BRAZIL: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 754 BRAZIL: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 755 BRAZIL: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 756 BRAZIL: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 757 BRAZIL: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 758 BRAZIL: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 759 BRAZIL: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 760 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 761 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 762 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 763 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 764 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 765 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 766 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 767 MEXICO: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 768 MEXICO: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 769 MEXICO: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 770 MEXICO: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 771 MEXICO: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 772 MEXICO: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 773 MEXICO: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 774 MEXICO: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 775 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 776 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 777 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 778 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 779 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 780 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 781 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 782 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 783 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 784 REST OF LATIN AMERICA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 785 REST OF LATIN AMERICA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 786 REST OF LATIN AMERICA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 787 REST OF LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 788 REST OF LATIN AMERICA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 789 REST OF LATIN AMERICA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 790 MIDDLE EAST: FLOW CYTOMETRY MARKET, BY REGION, 2024-2034 (USD MILLION)
- TABLE 791 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 792 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 793 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 794 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 795 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 796 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 797 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 798 MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 799 MIDDLE EAST: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 800 MIDDLE EAST: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 801 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 802 MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 803 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 804 MIDDLE EAST: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 805 MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 806 GCC COUNTRIES: FLOW CYTOMETRY MARKET, BY COUNTRY, 2024-2034 (USD MILLION)
- TABLE 807 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 808 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 809 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 810 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 811 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 812 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 813 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 814 GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 815 GCC COUNTRIES: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 816 GCC COUNTRIES: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 817 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 818 GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 819 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 820 GCC COUNTRIES: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 821 GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 822 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 823 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 824 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 825 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 826 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 827 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 828 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 829 SAUDI ARABIA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 830 SAUDI ARABIA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 831 SAUDI ARABIA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 832 SAUDI ARABIA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 833 SAUDI ARABIA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 834 SAUDI ARABIA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 835 SAUDI ARABIA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 836 SAUDI ARABIA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 837 UAE: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 838 UAE: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 839 UAE: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 840 UAE: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 841 UAE: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 842 UAE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 843 UAE: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 844 UAE: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 845 UAE: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 846 UAE: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 847 UAE: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 848 UAE: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 849 UAE: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 850 UAE: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 851 UAE: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 852 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 853 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 854 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 855 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 856 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 857 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 858 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 859 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 860 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 861 REST OF GCC COUNTRIES: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 862 REST OF GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 863 REST OF GCC COUNTRIES: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 864 REST OF GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 865 REST OF GCC COUNTRIES: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 866 REST OF GCC COUNTRIES: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 867 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 868 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 869 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 870 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 871 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 872 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 873 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 874 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 875 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 876 REST OF MIDDLE EAST: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 877 REST OF MIDDLE EAST: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 878 REST OF MIDDLE EAST: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 879 REST OF MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 880 REST OF MIDDLE EAST: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 881 REST OF MIDDLE EAST: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 882 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 883 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET FOR REAGENTS & CONSUMABLES, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 884 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ANTIBODIES, 2024-2034 (USD MILLION)
- TABLE 885 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET FOR ASSAYS & KITS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 886 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET FOR INSTRUMENTS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 887 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL ANALYZERS, 2024-2034 (USD MILLION)
- TABLE 888 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET FOR CELL SORTERS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 889 AFRICA: FLOW CYTOMETRY PRODUCTS MARKET, BY TECHNOLOGY, 2024-2034 (USD MILLION)
- TABLE 890 AFRICA: FLOW CYTOMETRY PRODUCT MARKET, BY DETECTION MODALITY, 2024-2034 (USD MILLION)
- TABLE 891 AFRICA: FLOW CYTOMETRY MARKET, BY APPLICATION, 2024-2034 (USD MILLION)
- TABLE 892 AFRICA: FLOW CYTOMETRY MARKET FOR RESEARCH APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 893 AFRICA: FLOW CYTOMETRY MARKET FOR CLINICAL APPLICATIONS, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 894 AFRICA: FLOW CYTOMETRY SERVICES MARKET, BY TYPE, 2024-2034 (USD MILLION)
- TABLE 895 AFRICA: FLOW CYTOMETRY PRODUCT MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 896 AFRICA: FLOW CYTOMETRY SERVICES MARKET, BY END USER, 2024-2034 (USD MILLION)
- TABLE 897 OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN FLOW CYTOMETRY MARKET, JANUARY 2023-JULY 2026
- TABLE 898 FLOW CYTOMETRY MARKET: DEGREE OF COMPETITION
- TABLE 899 FLOW CYTOMETRY MARKET: REGION FOOTPRINT
- TABLE 900 FLOW CYTOMETRY MARKET: PRODUCT & SERVICE FOOTPRINT
- TABLE 901 FLOW CYTOMETRY MARKET: TECHNOLOGY FOOTPRINT
- TABLE 902 FLOW CYTOMETRY MARKET: APPLICATION FOOTPRINT
- TABLE 903 FLOW CYTOMETRY MARKET: DETAILED LIST OF KEY STARTUP/SME PLAYERS
- TABLE 904 FLOW CYTOMETRY MARKET: COMPETITIVE BENCHMARKING OF STARTUPS/SMES
- TABLE 905 FLOW CYTOMETRY MARKET: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 906 FLOW CYTOMETRY MARKET: DEALS, JANUARY 2023-JULY 2026
- TABLE 907 BD: COMPANY OVERVIEW
- TABLE 908 BD: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 909 BD: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 910 BD: DEALS, JANUARY 2023-JULY 2026
- TABLE 911 DANAHER CORPORATION: COMPANY OVERVIEW
- TABLE 912 DANAHER CORPORATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 913 DANAHER CORPORATION: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 914 DANAHER CORPORATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 915 THERMO FISHER SCIENTIFIC INC.: COMPANY OVERVIEW
- TABLE 916 THERMO FISHER SCIENTIFIC INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 917 THERMO FISHER SCIENTIFIC INC.: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 918 REVVITY: COMPANY OVERVIEW
- TABLE 919 REVVITY: PRODUCTS/ SERVICES OFFERED
- TABLE 920 AGILENT TECHNOLOGIES, INC.: COMPANY OVERVIEW
- TABLE 921 AGILENT TECHNOLOGIES, INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 922 AGILENT TECHNOLOGIES, INC.: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 923 SONY GROUP CORPORATION: COMPANY OVERVIEW
- TABLE 924 SONY GROUP CORPORATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 925 SONY GROUP CORPORATION: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 926 SONY GROUP CORPORATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 927 BIO-RAD LABORATORIES, INC.: COMPANY OVERVIEW
- TABLE 928 BIO-RAD LABORATORIES, INC.: PRODUCTS/ SERVICES/SOLUTIONS OFFERED
- TABLE 929 BIO-RAD LABORATORIES, INC.: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 930 MILTENYI BIOTEC: COMPANY OVERVIEW
- TABLE 931 MILTENYI BIOTEC: PRODUCTS/ SERVICES OFFERED
- TABLE 932 ENZO BIOCHEM INC.: COMPANY OVERVIEW
- TABLE 933 ENZO BIOCHEM INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 934 SYSMEX CORPORATION: COMPANY OVERVIEW
- TABLE 935 SYSMEX CORPORATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 936 CYTEK BIOSCIENCES: COMPANY OVERVIEW
- TABLE 937 CYTEK BIOSCIENCES: PRODUCTS/ SERVICES OFFERED
- TABLE 938 CYTEK BIOSCIENCES: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 939 CYTEK BIOSCIENCES: DEALS, JANUARY 2023-JULY 2026
- TABLE 940 BIOMERIEUX: COMPANY OVERVIEW
- TABLE 941 BIOMERIEUX: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 942 BIOMERIEUX: DEALS, JANUARY 2023-JULY 2026
- TABLE 943 CYTONOME/ST, LLC: COMPANY OVERVIEW
- TABLE 944 CYTONOME/ST, LLC: PRODUCTS/ SERVICES OFFERED
- TABLE 945 SARTORIUS AG: COMPANY OVERVIEW
- TABLE 946 SARTORIUS AG: PRODUCTS/ SERVICES OFFERED
- TABLE 947 SARTORIUS AG: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 948 UNION BIOMETRICA, INC.: COMPANY OVERVIEW
- TABLE 949 UNION BIOMETRICA, INC.: PRODUCTS/ SERVICES OFFERED
- TABLE 950 TAKARA BIO INC.: COMPANY OVERVIEW
- TABLE 951 TAKARA BIO INC.: PRODUCTS/ SERVICES OFFERED
- TABLE 952 CHARLES RIVER LABORATORIES: COMPANY OVERVIEW
- TABLE 953 CHARLES RIVER LABORATORIES: PRODUCTS/ SERVICES OFFERED
- TABLE 954 THE JACKSON LABORATORY: COMPANY OVERVIEW
- TABLE 955 THE JACKSON LABORATORY: PRODUCTS/ SERVICES OFFERED
- TABLE 956 APOGEE FLOW SYSTEMS LTD: COMPANY OVERVIEW
- TABLE 957 STRATEDIGM, INC.: COMPANY OVERVIEW
- TABLE 958 NOVA BIOMEDICAL: COMPANY OVERVIEW
- TABLE 959 ON-CHIP BIOTECHNOLOGIES CO., LTD.: COMPANY OVERVIEW
- TABLE 960 PRECISION CELL SYSTEMS: COMPANY OVERVIEW
- TABLE 961 CYTOBUOY: COMPANY OVERVIEW
- TABLE 962 CUSABIO TECHNOLOGY LLC: COMPANY OVERVIEW
- TABLE 963 DE NOVO SOFTWARE: COMPANY OVERVIEW
- TABLE 964 ALTASCIENCES: COMPANY OVERVIEW
- TABLE 965 RAYBIOTECH, INC.: COMPANY OVERVIEW
- TABLE 966 KCAS BIO: COMPANY OVERVIEW
- TABLE 967 IMPACT ANALYSIS OF SUPPLY-SIDE AND DEMAND-SIDE FACTORS
- TABLE 968 RISK ASSESSMENT
List of Figures
- FIGURE 1 FLOW CYTOMETRY MARKET SEGMENTATION AND REGIONS CONSIDERED
- FIGURE 2 FLOW CYTOMETRY MARKET: YEARS CONSIDERED
- FIGURE 3 MARKET SCENARIO
- FIGURE 4 GLOBAL FLOW CYTOMETRY MARKET, 2024-2034
- FIGURE 5 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN FLOW CYTOMETRY MARKET, 2023-2026
- FIGURE 6 DISRUPTIONS INFLUENCING GROWTH OF FLOW CYTOMETRY MARKET
- FIGURE 7 HIGH-GROWTH SEGMENTS IN FLOW CYTOMETRY MARKET, 2026-2034
- FIGURE 8 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN FLOW CYTOMETRY MARKET, IN TERMS OF VALUE, DURING FORECAST PERIOD
- FIGURE 9 RISING ADOPTION OF FLOW CYTOMETRY IN IMMUNOLOGY, ONCOLOGY, AND CLINICAL RESEARCH TO DRIVE MARKET GROWTH
- FIGURE 10 REAGENTS & CONSUMABLES DOMINATED NORTH AMERICAN MARKET IN 2025
- FIGURE 11 ASIA PACIFIC COUNTRIES TO REGISTER HIGHER GROWTH RATES DURING FORECAST PERIOD
- FIGURE 12 CELL-BASED FLOW CYTOMETRY TO DOMINATE MARKET DURING FORECAST PERIOD
- FIGURE 13 FLOW CYTOMETRY MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 FLOW CYTOMETRY MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 VALUE CHAIN ANALYSIS
- FIGURE 16 FLOW CYTOMETRY MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 AVERAGE SELLING PRICE OF INSTRUMENTS, BY KEY PLAYER, 2025 (USD)
- FIGURE 18 AVERAGE SELLING PRICE OF REAGENTS & CONSUMABLES, BY KEY PLAYER, 2025 (USD)
- FIGURE 19 AVERAGE SELLING PRICE OF INSTRUMENTS, BY REGION, 2025 (USD)
- FIGURE 20 AVERAGE SELLING PRICE OF REAGENTS & CONSUMABLES, BY REGION, 2025 (USD)
- FIGURE 21 FLOW CYTOMETRY MARKET: TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- FIGURE 22 INVESTMENT & FUNDING SCENARIO, 2023-2025 (USD MILLION)
- FIGURE 23 PATENT APPLICATIONS IN THE FLOW CYTOMETRY MARKET, JANUARY 2015-DECEMBER 2025
- FIGURE 24 IMPACT OF AI/GEN AI ON FLOW CYTOMETRY MARKET
- FIGURE 25 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS
- FIGURE 26 KEY BUYING CRITERIA, BY END USER
- FIGURE 27 NORTH AMERICA: FLOW CYTOMETRY MARKET SNAPSHOT
- FIGURE 28 ASIA PACIFIC: FLOW CYTOMETRY MARKET SNAPSHOT
- FIGURE 29 REVENUE ANALYSIS OF KEY PLAYERS IN FLOW CYTOMETRY MARKET, 2021-2025 (USD MILLION)
- FIGURE 30 MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025
- FIGURE 31 FLOW CYTOMETRY MARKET: BRAND COMPARATIVE ANALYSIS
- FIGURE 32 FLOW CYTOMETRY MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 33 FLOW CYTOMETRY MARKET: COMPANY FOOTPRINT
- FIGURE 34 FLOW CYTOMETRY MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 35 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 36 EV/EBITDA OF KEY VENDORS
- FIGURE 37 BD: COMPANY SNAPSHOT (2025)
- FIGURE 38 DANAHER CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 39 THERMO FISHER SCIENTIFIC INC.: COMPANY SNAPSHOT (2025)
- FIGURE 40 REVVITY: COMPANY SNAPSHOT (2025)
- FIGURE 41 AGILENT TECHNOLOGIES, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 42 SONY GROUP CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 43 BIO-RAD LABORATORIES, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 44 SYSMEX CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 45 CYTEK BIOSCIENCES: COMPANY SNAPSHOT (2025)
- FIGURE 46 BIOMERIEUX: COMPANY SNAPSHOT (2025)
- FIGURE 47 SARTORIUS AG: COMPANY SNAPSHOT (2025)
- FIGURE 48 TAKARA BIO INC.: COMPANY SNAPSHOT (2025)
- FIGURE 49 CHARLES RIVER LABORATORIES: COMPANY SNAPSHOT (2025)
- FIGURE 50 THE JACKSON LABORATORY: COMPANY SNAPSHOT (2025)
- FIGURE 51 FLOW CYTOMETRY MARKET: RESEARCH DESIGN
- FIGURE 52 FLOW CYTOMETRY MARKET: BREAKDOWN OF PRIMARIES
- FIGURE 53 FLOW CYTOMETRY MARKET: INSIGHTS FROM PRIMARIES
- FIGURE 54 GLOBAL FLOW CYTOMETRY MARKET ESTIMATION, 2025
- FIGURE 55 FLOW CYTOMETRY MARKET: COMPANY REVENUE ANALYSIS-BASED ESTIMATION (BOTTOM-UP APPROACH) (2025)
- FIGURE 56 ILLUSTRATIVE EXAMPLE OF BD: REVENUE ANALYSIS (2025)
- FIGURE 57 SEGMENTAL MARKET SIZE ESTIMATION: TOP-DOWN APPROACH
- FIGURE 58 FLOW CYTOMETRY MARKET: CAGR PROJECTIONS
- FIGURE 59 FLOW CYTOMETRY MARKET: DATA TRIANGULATION

