PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116714

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116714
India Natural Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the India natural gas market size was valued at 77.40 Thousand MMSCM in 2025 and estimated to grow from 81.47 Thousand MMSCM in 2026 to reach 105.28 Thousand MMSCM by 2031, at a CAGR of 5.26% during the forecast period (2026-2031).
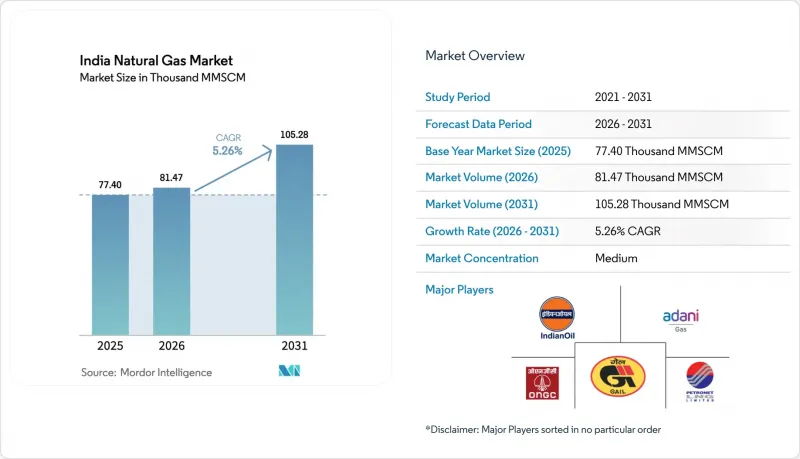
The India Natural Gas Market Report is Segment by Type (Compressed Natural Gas, Piped Natural Gas, and Liquefied Natural Gas ), Source (Domestic Production - Onshore, Domestic Production - Offshore, and LNG Imports), and End-Use Sector (Fertilizer Production, City Gas Distribution, Transportation, Petrochemical Feedstock, and Others). The Market Sizes and Forecasts are Provided in Terms of Volume (MMSCM).
India Natural Gas Market Trends and Insights
Expanding City Gas Distribution Network in Tier-2 & Tier-3 Cities
Roll-outs across 307 areas aim for 12.6 crore PNG connections and 18,336 CNG stations by 2034, pushing the India natural gas market deep into smaller cities . Gujarat Gas has earmarked INR 1,200 crore to hook 3.3 lakh new homes and 200 CNG outlets in FY25-an approach replicated by other distributors venturing beyond saturated metros. Urbanization trends, cleaner-fuel priorities, and standardized tariffs improve project viability, though low consumption density demands innovative last-mile models and long-term policy backing.
Fertilizer Sector's Shift to Gas-Based Feedstock under Nutrient-Based Subsidy Reforms
The sector drew 31% of national demand in 2024 and remains insulated from LNG price swings through direct government support. Reforms channel APM and new-well gas to fertilizer plants, incentivizing a move away from naphtha and reinforcing supply security. Stable offtake from this price-inelastic segment cushions the India natural gas market against industrial fuel-switching cycles while anchoring infrastructure utilization.
Volatility in Spot LNG Prices Driving Industrial Fuel Switching
Spot LNG fluctuated from USD 2/MMBTU in early 2020 to USD 30/MMBTU in late 2021, prompting price-sensitive users to revert to fuel oil or coal whenever landed costs breach viability thresholds. Reliance on spot cargoes for roughly 25% of supply exposes the India natural gas market to exogenous shocks, especially in non-subsidized industries and peaking power plants that lack hedging mechanisms.
Other drivers and restraints analyzed in the detailed report include:
- LNG Contract Restructuring Linking Prices to Emerging Domestic Gas Hub
- Interstate Pipeline Connectivity via "One Nation, One Gas Grid" Policy
- Delays in Pipeline Right-of-Way Clearances across Forest Corridors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
CNG delivered 47.10% of the India natural gas market size in 2025 and is forecast for a 5.83% CAGR, versus PNG's dominant 52.90% share but slower trajectory. Rapid station build-outs-8,067 outlets operational by March 2025-and supportive transport policies make CNG an accessible decarbonization lever for commercial fleets. Bajaj Auto's launch of CNG motorcycles and forthcoming CNG scooter platforms broadens the addressable two-wheeler universe. PNG expansion remains challenged by connection cost, subsidized LPG competition, and lower rural densities, leaving 93 geographical areas without a single household hookup, which compels CGD firms to craft pay-as-you-go and community pipeline solutions.
Complete Report Scope:
- By Type
- Compressed Natural Gas (CNG)
- Piped Natural Gas (PNG)
- Liquefied Natural Gas (LNG)
- By Source
- Domestic Production - Onshore
- Domestic Production - Offshore
- LNG Imports
- By End-Use Sector
- Fertilizer Production
- City Gas Distribution
- Transportation
- Petrochemical Feedstock
- Others [Industrial Manufacturing, Agriculture (Tea Plantation), IC for Pipeline System, LPG Shrinkage, Sponge Iron/Steel]
List of Companies Covered in this Report:
- Adani Total Gas Limited
- Assam Gas Company Limited
- Bharat Petroleum Corporation Limited
- Cairn Oil & Gas (Vedanta Limited)
- Essar Oil & Gas Exploration & Production Ltd.
- ExxonMobil India
- GAIL (India) Limited
- Gujarat Gas Limited
- Gujarat State Petronet Limited
- H-Energy Private Limited
- Hindustan Petroleum Corporation Limited
- Indian Oil Corporation Limited
- Indraprastha Gas Limited
- Mahanagar Gas Limited
- Oil and Natural Gas Corporation (ONGC)
- Petronet LNG Limited
- Reliance Industries Limited
- Shell Energy India Private Limited
- Torrent Gas Private Limited
- TotalEnergies SE (India Operations)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding City Gas Distribution Network in Tier-2 & Tier-3 Cities
- 4.2.2 Fertilizer Sector's Shift to Gas-Based Feedstock under Nutrient-Based Subsidy Reforms
- 4.2.3 LNG Contract Restructuring Linking Prices to Emerging Domestic Gas Hub
- 4.2.4 Industrial Decarbonization Mandates for Steel & Refining Clusters
- 4.2.5 Interstate Pipeline Connectivity via "One Nation, One Gas Grid" Policy
- 4.2.6 Emergence of Bio-CNG Blending Targets for CGD Operators
- 4.3 Market Restraints
- 4.3.1 Volatility in Spot LNG Prices Driving Industrial Fuel Switching
- 4.3.2 Delays in Pipeline Right-of-Way Clearances across Forest Corridors
- 4.3.3 Pricing Formula Caps Limiting Upstream Investment Economics
- 4.3.4 Competition from Rapidly Falling Levelized Cost of Solar-plus-Storage
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 PESTLE Analysis
- 4.8 Porter's Five Forces
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Compressed Natural Gas (CNG)
- 5.1.2 Piped Natural Gas (PNG)
- 5.1.3 Liquefied Natural Gas (LNG)
- 5.2 By Source
- 5.2.1 Domestic Production - Onshore
- 5.2.2 Domestic Production - Offshore
- 5.2.3 LNG Imports
- 5.3 By End-Use Sector
- 5.3.1 Fertilizer Production
- 5.3.2 City Gas Distribution
- 5.3.3 Transportation
- 5.3.4 Petrochemical Feedstock
- 5.3.5 Others [Industrial Manufacturing, Agriculture (Tea Plantation), IC for Pipeline System, LPG Shrinkage, Sponge Iron/Steel]
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Adani Total Gas Limited
- 6.4.2 Assam Gas Company Limited
- 6.4.3 Bharat Petroleum Corporation Limited
- 6.4.4 Cairn Oil & Gas (Vedanta Limited)
- 6.4.5 Essar Oil & Gas Exploration & Production Ltd.
- 6.4.6 ExxonMobil India
- 6.4.7 GAIL (India) Limited
- 6.4.8 Gujarat Gas Limited
- 6.4.9 Gujarat State Petronet Limited
- 6.4.10 H-Energy Private Limited
- 6.4.11 Hindustan Petroleum Corporation Limited
- 6.4.12 Indian Oil Corporation Limited
- 6.4.13 Indraprastha Gas Limited
- 6.4.14 Mahanagar Gas Limited
- 6.4.15 Oil and Natural Gas Corporation (ONGC)
- 6.4.16 Petronet LNG Limited
- 6.4.17 Reliance Industries Limited
- 6.4.18 Shell Energy India Private Limited
- 6.4.19 Torrent Gas Private Limited
- 6.4.20 TotalEnergies SE (India Operations)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

