PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118166

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118166
Middle East and Africa Irrigation Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Middle East and Africa irrigation pumps market size is projected to expand from USD 8.03 billion in 2025 and USD 8.61 billion in 2026 to USD 12.14 billion by 2031, registering a CAGR of 7.11% between 2026 and 2031.
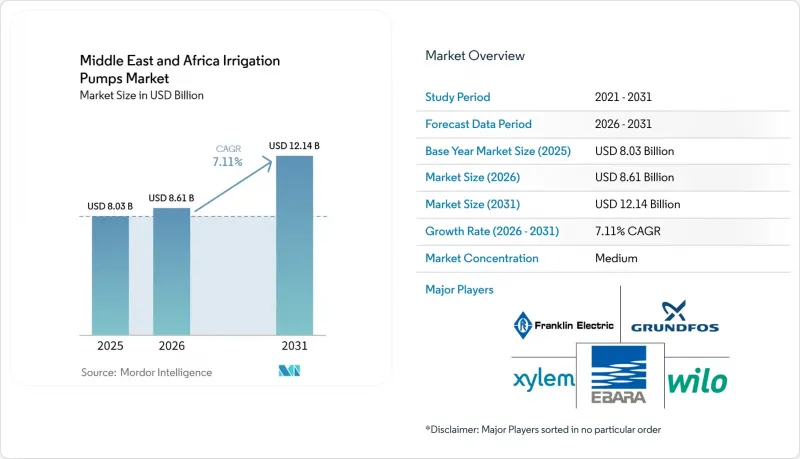
This report is Segmented by Type (Submersible Pump, Centrifugal Pump, Vortex Pump, and Other Irrigation Pump Types) and by Geography (Middle East and Africa). The Report Offers Market Size and Forecasts in Terms of Value (USD).
Middle East and Africa Irrigation Pumps Market Trends and Insights
Expansion of Pressurized Irrigation in Water-Stressed Farms
Flood irrigation is steadily losing ground to drip, sprinkler, and micro-irrigation systems across many farming zones in this region. That change matters because pressurized irrigation needs more reliable pumping performance and tighter pressure control than basic flood systems. The Saudi Irrigation Organization and the International Commission on Irrigation and Drainage (ICID) worked on an Integrated Irrigation Sector Management for Sustainable Development in 2024 to promote efficient irrigation and better water productivity among farmers in Saudi Arabia. Morocco is also expanding distribution infrastructure through the Saiss irrigation project 3, initiated in 2025, to convey 125 million cubic meters of water each year from the M'Dez dam. These projects raise demand for booster systems, pressure-regulated pump sets, and distribution pumps rather than only standard centrifugal units. That shift improves the sales mix in the Middle East and Africa irrigation pumps market because more engineered systems usually carry a higher unit value. It also supports replacement demand, as older pumps often do not meet the pressure and flow stability requirements of modern irrigation layouts. The result is a market where water-saving irrigation methods are directly tied to stronger demand for pump systems and higher technical requirements at the farm level.
Rising Solar-Powered Pump Adoption in Off-Grid Irrigation Clusters
Solar pumping is becoming one of the clearest growth themes in the Middle East and Africa irrigation pumps market. This is because large agricultural areas still lack reliable grid electricity, and diesel costs remain a burden for irrigation operations in rural areas. Ethiopia is moving from scattered pilots to scale, with the International Water Management Institute coordinating a national platform to mobilize 1,750 solar pumps in 2026. Morocco also shows a strong operating case, with solar irrigation pumping. In Saudi Arabia, a 4.58 MW solar water-pumping installation completed in Riyadh by Nuuko Power in October 2025 irrigated 2,560 acres while reducing annual operating costs. Solar adoption is also widening the supplier base, as lower-cost manufacturers can compete more effectively with buyers who focus on payback and fuel savings. As this spread continues, the Middle East and Africa irrigation pumps market is moving closer to a mixed competitive structure that includes global pump brands, local channel partners, and solar-focused entrants.
Limited Grid Reliability in Rural Irrigation Corridors
Unreliable electricity supply remains one of the clearest barriers to faster adoption of electric pumps in many irrigation zones. Voltage fluctuations and outages can damage motors and control components, increasing maintenance costs and eroding growers' confidence. Where supply is unstable, farmers often stay with diesel or delay upgrades to more advanced electric systems. This limits the spread of variable-speed drives and intelligent control systems that need stable voltage to perform well. It also slows adoption in the very corridors where irrigation expansion is most needed. As a result, the Middle East and Africa irrigation pumps market cannot fully benefit from premium electric technologies in many rural areas. The practical outcome is a split market in which modern equipment demand grows fastest only where power quality, financing, and technical support are available. In addition, unreliable grid access complicates irrigation scheduling, reduces operational efficiency during peak growing periods, and discourages investment in automated irrigation infrastructure, further constraining long-term modernization efforts across agricultural regions.
Other drivers and restraints analyzed in the detailed report include:
- Government Subsidy Support for Irrigation Modernization
- Groundwater Dependence in Arid and Semi-Arid Farming Belts
- High Upfront Cost of Solar and Variable-Speed Pump Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Submersible pumps accounted for 41.8% of the Middle East and Africa irrigation pump market share in 2025, making them the leading type segment, as deep-borehole irrigation remains central across Saudi Arabia, Egypt, and several arid farming zones in North Africa. Their strong position reflects the region's continued reliance on groundwater for irrigation, particularly in areas with limited or uneven access to surface water. Centrifugal pumps remained important in canal-fed agriculture and surface irrigation systems, while vortex pumps were used for sediment-laden water conditions. Other irrigation pump types continued to support specialized agricultural flow requirements.
Submersible pumps are anticipated to grow at the fastest rate, at a CAGR of 8.5% from 2026 to 2031, supported by deeper borehole use, rising solar integration, and continued irrigation demand across groundwater-dependent farming belts. Their growth is also tied to the need for reliable high-head pumping in desert agriculture and remote irrigation corridors. Centrifugal pumps are likely to see steady expansion where new distribution networks and surface-water irrigation projects are being developed, especially in organized schemes such as Morocco's Saiss project. Vortex pumps should retain a smaller but stable role in applications with suspended solids, while other irrigation pump types will continue serving niche high-flow agricultural uses.
Complete Report Scope:
- By Type
- Submersible Pump
- Centrifugal Pump
- Vortex Pump
- Other Irrigation Pump Types
- By Geography
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Kuwait
- Oman
- Bahrain
- Israel
- Rest of Middle East
- Africa
- Egypt
- South Africa
- Nigeria
- Kenya
- Morocco
- Algeria
- Ethiopia
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Grundfos Holding A/S
- Xylem Inc.
- Franklin Electric Co., Inc.
- Ebara Corporation
- Wilo Group
- KSB SE and Co. KGaA
- Sulzer Ltd
- The Gorman-Rupp Company
- Kirloskar Brothers Limited
- Shakti Pumps (India) Limited
- Jain Irrigation Systems Ltd.
- Davey Water
- Valmont Industries, Inc
- LEO Group Pump (Zhejiang) Co., Ltd.
- Shimge Pump Industry Group Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET DYNAMICS
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of pressurized irrigation in water-stressed farms
- 4.2.2 Rising solar-powered pump adoption in off-grid irrigation clusters
- 4.2.3 Government subsidy support for irrigation modernization
- 4.2.4 Replacement of diesel pumping with energy-efficient electric systems
- 4.2.5 Groundwater dependence in arid and semi-arid farming belts
- 4.2.6 Precision irrigation deployment on high-value crops
- 4.3 Market Restraints
- 4.3.1 Limited grid reliability in rural irrigation corridors
- 4.3.2 High upfront cost of solar and variable-speed pump systems
- 4.3.3 Borehole depletion increasing pump downtime and replacement burden
- 4.3.4 Fragmented farm sizes slowing standardized equipment adoption
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Buyers
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (Value)
- 5.1 By Type
- 5.1.1 Submersible Pump
- 5.1.2 Centrifugal Pump
- 5.1.3 Vortex Pump
- 5.1.4 Other Irrigation Pump Types
- 5.2 By Geography
- 5.2.1 Middle East
- 5.2.1.1 United Arab Emirates
- 5.2.1.2 Saudi Arabia
- 5.2.1.3 Qatar
- 5.2.1.4 Kuwait
- 5.2.1.5 Oman
- 5.2.1.6 Bahrain
- 5.2.1.7 Israel
- 5.2.1.8 Rest of Middle East
- 5.2.2 Africa
- 5.2.2.1 Egypt
- 5.2.2.2 South Africa
- 5.2.2.3 Nigeria
- 5.2.2.4 Kenya
- 5.2.2.5 Morocco
- 5.2.2.6 Algeria
- 5.2.2.7 Ethiopia
- 5.2.2.8 Rest of Africa
- 5.2.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Grundfos Holding A/S
- 6.4.2 Xylem Inc.
- 6.4.3 Franklin Electric Co., Inc.
- 6.4.4 Ebara Corporation
- 6.4.5 Wilo Group
- 6.4.6 KSB SE and Co. KGaA
- 6.4.7 Sulzer Ltd
- 6.4.8 The Gorman-Rupp Company
- 6.4.9 Kirloskar Brothers Limited
- 6.4.10 Shakti Pumps (India) Limited
- 6.4.11 Jain Irrigation Systems Ltd.
- 6.4.12 Davey Water
- 6.4.13 Valmont Industries, Inc
- 6.4.14 LEO Group Pump (Zhejiang) Co., Ltd.
- 6.4.15 Shimge Pump Industry Group Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

