PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119742

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119742
India Data Center Server - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2032)
According to Mordor Intelligence, the India data center server market size is expected to grow from USD 6.55 billion in 2025 to USD 7.05 billion in 2026 and is forecast to reach USD 10.94 billion by 2032 at 7.61% CAGR over 2026-2032.
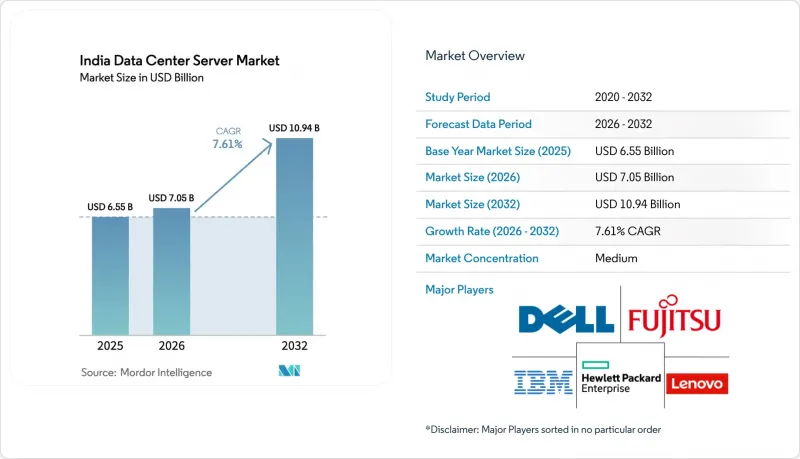
This report is Segmented by Form Factor (Blade Server, Rack Server, and More), Processor Architecture (x86, ARM, and More), Deployment Model (Hyperscale Cloud, Colocation, and More), End-User Industry (IT and Telecommunications, BFSI, and More), and Geography (North India, South India, and More). Market Forecasts are Provided in Terms of Value (USD).
India Data Center Server Market Trends and Insights
Hyperscaler and Colocation CAPEX Surge
Reliance Industries has announced a 3 GW data-center campus in Gujarat that will triple current national capacity and employ NVIDIA AI semiconductors powered by renewable energy. Colocation specialist CtrlS is rolling out 350 MW of "AI-ready" white space buffered by USD 2 billion of fresh investment. Government policy now allows 100% foreign direct investment in data-center infrastructure, which has accelerated cloud-region launches and deepened hardware refresh cycles. Facility blueprints increasingly specify high-density racks, liquid cooling, and DCIM systems calibrated for GPU clusters. With multiple operators racing to lock in land and power at favorable rates, procurement cycles for servers, networking, and power distribution units have shortened from twelve to six months, dramatically lifting baseline demand across the India data center server market.
5G Roll-out Driving Edge-Node Micro-Server Demand
Indian telecom operators will need 22 million skilled workers by 2025 to complete nationwide 5G, underlining the vast scale of tower-side compute that must be installed. Micro-server nodes with ruggedized, low-footprint enclosures house ARM-based boards that consume less than 250 W yet deliver adequate AI inference at the network edge. Bharti Airtel and Reliance Jio have issued multi-year purchase orders that bundle integrated cooling, distributed UPS, and zero-touch provisioning. Open-access fiber and renewed spectrum policies keep backhaul costs manageable, while state PLI schemes reimburse 4-6% of factory gate value for optimized edge systems manufactured locally. The resulting 8.1% CAGR uplift for edge micro-data centers will continue to pull share from centralized hyperscale racks inside the India data center server market.
Grid-Power Scarcity and Rising Utility Tariffs in Mumbai
Mumbai remains India's prime financial hub yet faces a stressed grid where large data-center additions can wait up to 18 months for new substation tie-ins. Operators now lock renewable power purchase agreements for solar farms in Gujarat at INR 3.1 per kWh, circumventing city tariffs that exceed INR 8.0 per kWh. Maharashtra's policy offers stamp-duty rebates and fast-track approvals for facilities built in dedicated technology parks, though capacity will come online only after 2027. In the interim, hyperscalers pivot expansions toward Navi Mumbai and Pune, diluting near-term server shipments into the city while sustaining national growth in the India data center server market.
Other drivers and restraints analyzed in the detailed report include:
- Gen-AI GPU Server Clusters for BFSI and OTT Workloads
- Data-Localization Mandates Under DPDP Act
- Import Duties and INR Volatility Inflating Server BoM
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Micro, modular, and edge servers will contribute USD 1.59 billion to the India data center server market size by 2032, expanding at an 7.76% CAGR. Rack designs still house 37.45% of 2025 shipments but lose incremental share to 2U micro-nodes that mount directly at tower shelters. The move shortens latency and lowers backhaul costs for video, AR, and industrial IoT. Apollo Hospitals uses Nutanix hyper-converged clusters across 72 facilities, boosting real-time monitoring while cutting IT energy by 80%. Tower servers keep traction among SMEs that lack rack infrastructure, while blade frames remain staples for finance workloads requiring dense virtualization.
Heightened power density within edge cabinets raises demand for direct-to-chip cooling plates and 48 V DC bus bars that reduce copper losses. Vendors package sealed module servers rated for 55 °C ambient operation with fan-less convection, essential for rural deployments. Engineering advances such as silicon photonics further consolidate functions, allowing even higher compute per liter. These shifts cement micro-servers as the fastest unit vector inside the India data center server market.
The India data center server market size attributable to x86 reached USD 4.01 billion in 2025, but ARM nodes grow faster toward 19.60% share by 2032. Make-in-India incentives give Netweb Technologies the economics to ship Tyrone ARM servers hosting 192 cores at 225 W TDP. ARM systems trim power by 25-30% relative to x86, a key advantage for edge locales with limited cooling. RISC/Power stays a niche for scientific workloads under the National Supercomputing Mission that has installed 35 PF of compute across 34 facilities.
Software stacks mature quickly: Red Hat and Canonical both certify core banking, ERP, and analytics frameworks on ARM, reducing migration friction. x86 maintains primacy in Microsoft Windows environments and legacy VMware estates, helped by predictable roadmaps from Intel and AMD. Overall, architectural choice now hinges on total-cost calculations that factor electricity, licensing, and supply-chain risk, ensuring healthy coexistence inside the India data center server market.
Complete Report Scope:
- By Form Factor
- Blade Server
- Rack Server
- Tower Server
- Micro / Modular / Edge Server
- By Processor Architecture
- x86
- ARM
- RISC / Power
- By Deployment Model
- Hyperscale/ Cloud Service Provider
- Colocation / Wholesale
- Enterprise On-premise
- By End-User Industry
- IT and Telecommunications
- BFSI
- Government and Public Sector
- Media and Entertainment
- E-commerce and Retail
- Healthcare and Life Sciences
- Other End Users
List of Companies Covered in this Report:
- Dell Technologies
- Hewlett Packard Enterprise
- Lenovo Group
- Cisco Systems
- Inspur Group
- Super Micro Computer
- Quanta Computer
- Wistron Corporation
- Huawei Technologies
- International Business Machines (IBM)
- Advanced Micro Devices (AMD)
- Intel Corporation
- NVIDIA Corporation
- Ampere Computing
- Fujitsu Limited
- Oracle Corporation
- NEC Corporation
- Gigabyte Technology
- ASUStek Computer
- Atos SE (Bull Servers)
- Netweb Technologies
- Acer Inc.
- Tata Consultancy Services - IaaS Platforms
- Reliance Jio Platforms - Edge DC Hardware
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hyperscaler and colocation capex surge (2025-30)
- 4.2.2 5G roll-out driving edge-node micro-server demand
- 4.2.3 Gen-AI GPU server clusters for BFSI and OTT workloads
- 4.2.4 Data-localisation mandates under DPDP Act boosting in-country racks
- 4.2.5 India's Green Open-Access policy lowering renewable PUE costs
- 4.2.6 State incentives for Make-in-India ARM server assembly
- 4.3 Market Restraints
- 4.3.1 Grid-power scarcity and rising utility tariffs in Mumbai
- 4.3.2 Import duties and INR volatility inflating server BOM
- 4.3.3 Supply-chain bottlenecks for HBM/advanced packaging
- 4.3.4 Shortage of data-center-skilled workforce outside Tier-1 cities
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Form Factor
- 5.1.1 Blade Server
- 5.1.2 Rack Server
- 5.1.3 Tower Server
- 5.1.4 Micro / Modular / Edge Server
- 5.2 By Processor Architecture
- 5.2.1 x86
- 5.2.2 ARM
- 5.2.3 RISC / Power
- 5.3 By Deployment Model
- 5.3.1 Hyperscale/ Cloud Service Provider
- 5.3.2 Colocation / Wholesale
- 5.3.3 Enterprise On-premise
- 5.4 By End-User Industry
- 5.4.1 IT and Telecommunications
- 5.4.2 BFSI
- 5.4.3 Government and Public Sector
- 5.4.4 Media and Entertainment
- 5.4.5 E-commerce and Retail
- 5.4.6 Healthcare and Life Sciences
- 5.4.7 Other End Users
6 COMPETITIVE LANDSCAPE
- 6.1 Market Share Analysis
- 6.2 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.2.1 Dell Technologies
- 6.2.2 Hewlett Packard Enterprise
- 6.2.3 Lenovo Group
- 6.2.4 Cisco Systems
- 6.2.5 Inspur Group
- 6.2.6 Super Micro Computer
- 6.2.7 Quanta Computer
- 6.2.8 Wistron Corporation
- 6.2.9 Huawei Technologies
- 6.2.10 International Business Machines (IBM)
- 6.2.11 Advanced Micro Devices (AMD)
- 6.2.12 Intel Corporation
- 6.2.13 NVIDIA Corporation
- 6.2.14 Ampere Computing
- 6.2.15 Fujitsu Limited
- 6.2.16 Oracle Corporation
- 6.2.17 NEC Corporation
- 6.2.18 Gigabyte Technology
- 6.2.19 ASUStek Computer
- 6.2.20 Atos SE (Bull Servers)
- 6.2.21 Netweb Technologies
- 6.2.22 Acer Inc.
- 6.2.23 Tata Consultancy Services - IaaS Platforms
- 6.2.24 Reliance Jio Platforms - Edge DC Hardware
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

