PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119743

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119743
China Data Center Server - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the China data center server market size was valued at USD 12.95 billion in 2025 and is estimated to grow from USD 15.36 billion in 2026 to reach USD 36.68 billion by 2031, at a CAGR of 19.02% during the forecast period (2026-2031).
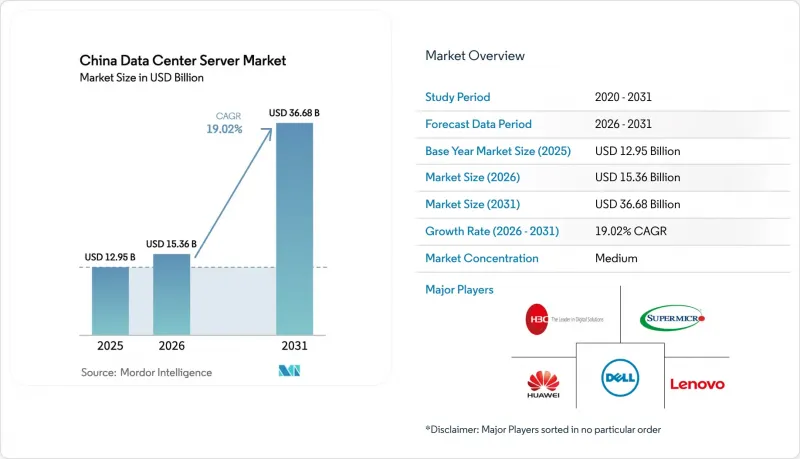
This report is Segmented by Tier Type (Tier 1 and 2, and More), Data Center Size (Small, Medium, and More), Data Center Type (Colocation, Hyperscalers/CSPs, and More), Form Factor (Half-Height Blades, Full-Height Blades, and More), Application/Workload (Virtualization and Private Cloud, HPC, and More). Market Forecasts are Provided in Terms of Value (USD).
China Data Center Server Market Trends and Insights
Surge in AI and GPU-Accelerated Workload Demand
Large language models such as Alibaba's Tongyi Qianwen and Baidu's ERNIE require clusters of eight-way GPU nodes linked by 400 GbE or InfiniBand fabrics, pushing typical rack densities above 70 kW. Operators purchased roughly 1 million Nvidia H20 GPUs in 2025, pairing them with custom cold-plate loops to maximize throughput despite lower peak flops. Huawei's Ascend 910B, fabricated at SMIC, is winning share among state-owned enterprises prioritizing supply-chain sovereignty over raw benchmark records. The Ministry of Industry and Information Technology reported a 45% jump in intelligent-computing power installations in early 2025, triple the growth of general-purpose servers. These dynamics lift average selling prices, accelerate adoption of NVMe storage, and magnify the overall momentum of the China data center server market.
Rising Enterprise Cloud Adoption and Public Cloud IaaS Spending
CAICT estimated that 38% of enterprise workloads ran on public or hybrid clouds by end-2025, up from 29% in 2023. Tencent Cloud pledged USD 10 billion through 2030 for new campuses in Tianjin, Chongqing, and Qingyuan, heightening bulk demand for high-density chassis. Alibaba Cloud's fifth-generation ECS instances, powered by ARM-based Yitian 710 chips, trimmed per-VM cost by 20% relative to x86 predecessors. With Baidu operating more than 500,000 servers and planning 100,000 more in 2026, vendor success hinges on securing hyperscale design wins. This concentration further solidifies purchasing power and shapes customization trends across the China data center server market.
High CapEx and Power-Land Scarcity in Tier 1 Hubs
Land in Beijing's Yizhuang and Shanghai's Lingang averaged CNY 15 million (USD 2.1 million) per acre in 2025, while municipal power caps hold new allocations to 50 MW per project. Shenzhen bans builds with PUE above 1.25, effectively mandating liquid cooling and adding 20% to upfront spend. Operators retrofit telecom exchanges or source capacity in Chengdu and Wuhan where land costs one-third as much, then reserve Tier 1 racks for GPU-dense clusters. The bifurcated strategy increases logistical complexity and slows urban expansion, curbing near-term velocity for the China data center server market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid 5G Roll-Out Catalyzing Edge Data Center Expansion
- Government Digital-Infrastructure Incentives and Subsidies
- Export Controls Limiting Access to Cutting-Edge GPUs and CPUs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 facilities held 71.24% of 2025 installations, underscoring their balance of cost and 99.982% uptime, while Tier 4 capacity is rising at a 20.31% CAGR as finance and public-cloud operators safeguard AI training runs from interruption. In 2025, China Construction Bank reported 12 Tier 4 sites that hosted distributed-ledger settlement workloads without unscheduled outages. Insurance carriers and hospitals follow suit to comply with 99.995% availability mandates. Vendors cater with blade platforms featuring dual-path fabrics and hot-swap everything, elevating ASPs but minimizing downtime penalties.
Price-sensitive SMEs continue to favor Tier 3 colocation racks that cost roughly 30% less than Tier 4 cabinets, fueling resilient refresh for single-supply air-cooled servers. Prefabricated Tier 3 pods, deliverable in six months, suit the rapid iteration culture of Chinese software firms. Consequently, the China data center server market sustains a dual-track mix, where high-margin Tier 4 nodes grow fastest yet Tier 3 still anchors shipment volume.
Hyperscale campuses with more than 10,000 servers commanded 40.54% of installed units in 2025 and are progressing at a 20.14% CAGR as Alibaba Cloud, Tencent Cloud, and Baidu Cloud add greenfield sites inland. Alibaba operated seven such campuses in 2025 and announced two more in Chengdu and Wuhan, each designed for 80,000 liquid-cooled racks. Volume buys secure up to 30% list-price discounts and enable co-design of custom silicon.
Large (1,000-10,000 servers) and medium (100-1,000) facilities remain vital for regional ISPs, provincial governments, and industrial hubs that crave local control but lack hyperscale budgets. Small on-premise rooms are retiring as cloud-first mandates take hold, redirecting replacement demand into shared facilities. The resulting scale polarization concentrates bargaining power and defines roadmaps for the China data center server market.
Complete Report Scope:
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small Data Center
- Medium Data Center
- Large Data Center
- Hyperscale Data Center
- By Data Center Type
- Colocation Data Center
- Hyperscalers Data Center/CSPs
- Enterprise and Edge Data Center
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
List of Companies Covered in this Report:
- Dell Technologies Inc.
- Huawei Technologies Co., Ltd.
- Lenovo Group Limited
- New H3C Technologies Co., Ltd.
- Inspur Group (IEIT Systems Co., Ltd.)
- Dawning Information Industry Co., Ltd. (Sugon)
- Super Micro Computer, Inc.
- Hewlett Packard Enterprise Company
- ZTE Corporation (Server Division)
- NVIDIA Corporation (Server Systems)
- Phytium Technology Co., Ltd.
- Hygon Information Technology Co., Ltd.
- Shanghai Zhaoxin Semiconductor Co., Ltd.
- Alibaba Cloud Computing Co., Ltd.
- Tencent Cloud Computing (Beijing) Co., Ltd.
- Baidu Cloud (Baidu Inc.)
- Cambricon Technologies Corporation Limited
- Foxconn Technology Group (Data Center ODM)
- HiSilicon Technologies Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in AI and GPU-Accelerated Workload Demand
- 4.2.2 Rising Enterprise Cloud Adoption and Public Cloud IaaS Spending
- 4.2.3 Rapid 5G Roll-Out Catalyzing Edge Data Center Expansion
- 4.2.4 Government Digital-Infrastructure Incentives and Subsidies
- 4.2.5 Commercialization of Underwater Data Centers for Sustainable Cooling
- 4.2.6 Factory-Integrated Cabinet Delivery Shortening Deployment Lead Times
- 4.3 Market Restraints
- 4.3.1 High CapEx and Power-Land Scarcity in Tier-1 Hubs
- 4.3.2 Export Controls Limiting Access to Cutting-Edge GPUs and CPUs
- 4.3.3 Advanced Packaging Capacity Bottlenecks for AI Server Components
- 4.3.4 Water-Use Restrictions Challenging Liquid-Cooling Scale-Up
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Tier Type
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Data Center Size
- 5.2.1 Small Data Center
- 5.2.2 Medium Data Center
- 5.2.3 Large Data Center
- 5.2.4 Hyperscale Data Center
- 5.3 By Data Center Type
- 5.3.1 Colocation Data Center
- 5.3.2 Hyperscalers Data Center/CSPs
- 5.3.3 Enterprise and Edge Data Center
- 5.4 By Form Factor
- 5.4.1 Half-height Blades
- 5.4.2 Full-height Blades
- 5.4.3 Quarter-height / Micro-blades
- 5.5 By Application / Workload
- 5.5.1 Virtualisation and Private Cloud
- 5.5.2 High-Performance Computing (HPC)
- 5.5.3 Artificial Intelligence/Machine Learning and Data Analytics
- 5.5.4 Storage-centric
- 5.5.5 Edge / IoT Gateways
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Dell Technologies Inc.
- 6.4.2 Huawei Technologies Co., Ltd.
- 6.4.3 Lenovo Group Limited
- 6.4.4 New H3C Technologies Co., Ltd.
- 6.4.5 Inspur Group (IEIT Systems Co., Ltd.)
- 6.4.6 Dawning Information Industry Co., Ltd. (Sugon)
- 6.4.7 Super Micro Computer, Inc.
- 6.4.8 Hewlett Packard Enterprise Company
- 6.4.9 ZTE Corporation (Server Division)
- 6.4.10 NVIDIA Corporation (Server Systems)
- 6.4.11 Phytium Technology Co., Ltd.
- 6.4.12 Hygon Information Technology Co., Ltd.
- 6.4.13 Shanghai Zhaoxin Semiconductor Co., Ltd.
- 6.4.14 Alibaba Cloud Computing Co., Ltd.
- 6.4.15 Tencent Cloud Computing (Beijing) Co., Ltd.
- 6.4.16 Baidu Cloud (Baidu Inc.)
- 6.4.17 Cambricon Technologies Corporation Limited
- 6.4.18 Foxconn Technology Group (Data Center ODM)
- 6.4.19 HiSilicon Technologies Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

