PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119823

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119823
Europe Food Cold Chain Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, Europe food cold chain logistics market size in 2026 is estimated at USD 81.29 billion, growing from 2025 value of USD 74.70 billion with 2031 projections showing USD 124.14 billion, growing at 8.84% CAGR over 2026-2031.
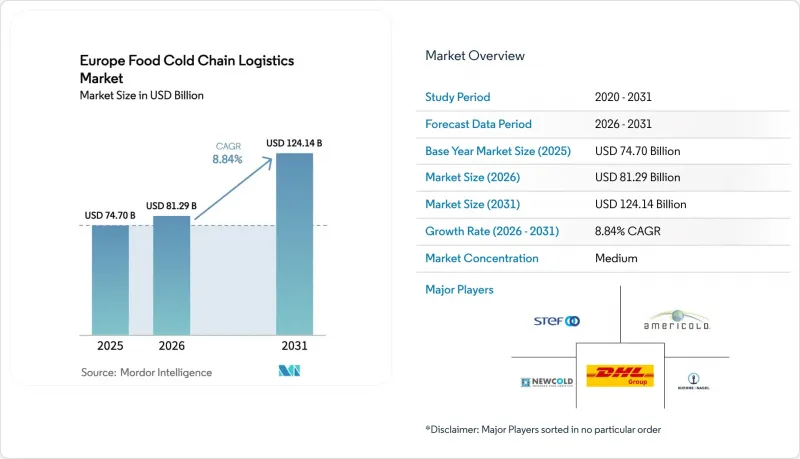
This report is Segmented by Product Type (Frozen Meat & Poultry, Fish & Seafood, Dairy & Ice-Cream and More), by Service Type (Refrigerated Storage, Refrigerated Transportation and Value-Added Services), by Temperature Type (Chilled (0-5 °C), Frozen (-18-0 °C) and Ambient) and by Country (United Kingdom, Germany, France, Italy, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Food Cold Chain Logistics Market Trends and Insights
Europe-wide Shift Toward Omni-Channel Grocery Distribution Networks
European grocers scale click-and-collect and rapid-delivery models that replace single mega-warehouses with dense clusters of micro-fulfilment hubs positioned near city centres. Operators respond by deploying modular buildings with frozen, chilled and ambient zones under one roof, supported by advanced energy-management software that balances refrigeration loads against power-price signals. Robotics adoption in Denmark illustrates the push toward automated pallet handling that compresses order-to-ship cycles without expanding headcount. Success now hinges on securing scarce urban real estate and integrating Internet-of-Things (IoT) sensors that certify temperature compliance in near real time. As these distributed networks mature, third-party logistics providers differentiate through data-driven route optimisation that protects product integrity during same-day deliveries.
Mandatory EU Green Deal Targets Accelerating Natural Refrigerant Adoption
The F-gas phasedown forces warehouse owners to retire high-GWP refrigerants and redesign systems for ammonia or CO2. Initial capital intensity is high, yet operators report lower electricity use once regenerative heat reclaim and variable-speed compressors are in place. The ICCEE programme illustrates industry commitment by targeting 118 GWh of annual primary-energy savings and EUR 64 million of related investments. Larger companies absorb the expense by refinancing on green-bond markets, while smaller firms face merger pressure as compliance deadlines approach. A scarcity of engineers experienced with natural refrigerants adds wage inflation to project budgets but also seeds a specialised labour pool that bolsters long-run technical resilience.
Continental Driver Shortage Inflating Transportation Costs
Europe faces 745,000 unfilled truck-driver slots by 2028, equal to 17% of required capacity. The talent pipeline falters as only 5% of current drivers are under 25 and cross-border routes carry extra administrative burden. IRU data notes 426,000 vacant positions already, pushing wages up and forcing shippers to book capacity weeks earlier than before. Spot-rate premiums on refrigerated lanes have widened relative to ambient lanes due to specialised licence needs and stricter rest-period rules. Modal shift to rail garners interest, yet cold-capable wagons and intermodal plugs are scarce, delaying large-scale migration and keeping road costs elevated.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Capacity Additions in Iberian Peninsula Driven by Export Growth
- Surge in Demand for Ultra-Low-Temperature Storage for Plant-Based Alternatives
- High CAPEX for F-Gas Phasedown Compliance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Europe food cold chain logistics market size for Frozen Meat & Poultry reached the equivalent of 31.05% share in 2025 and remains the largest revenue contributor despite slower incremental growth. Ready Meals & Others posts the highest 8.93% CAGR to 2031, propelled by dual-income households that value heat-and-eat foods compatible with shorter mealtimes. Fish & Seafood maintains resilient demand as aquaculture output scales and retailers promote omega-3 benefits, while Dairy & Ice-cream bookings continue to follow stable consumption patterns tied to established retail promotions. In fruits and vegetables, year-round supply strategies extend cold-chain penetration into previously seasonal categories, stimulating uptake of ethylene-control sachets that preserve freshness during long-haul moves.
Flash-freezing techniques in the Bakery & Confectionery segment allow centralised par-bake production shipped at -18 °C and finished on-site, shifting volume away from daily chilled deliveries. Flash-heat preservation trials for meat products indicate shelf-stable windows of up to 5 days, hinting at future attenuation of cold-chain reliance in selected cuts. Plant-based SKUs, which often blend protein isolates with functional fats, introduce atypical thermal profiles that force operators to recalibrate storage zoning within multi-use chambers. As consumer preferences evolve, agile 3PLs able to match niche temperature regimes widen their service revenue bases across converging product groups.
Complete Report Scope:
- By Product Type
- Frozen Meat & Poultry
- Fish & Seafood
- Dairy & Ice-cream
- Fruits & Vegetables
- Bakery & Confectionery
- Ready Meals & Others
- By Service Type
- Refrigerated Storage
- Refrigerated Transportation
- Road
- Rail
- Sea
- Air
- Value-Added Services
- By Temperature Type
- Chilled (0-5 °C)
- Frozen (-18-0 °C)
- Ambient
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Nordics
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Lineage Logistics Holdings, LLC
- STEF SA
- Americold Logistics, LLC (AGRO Merchants Europe)
- DHL Supply Chain (Deutsche Post DHL Group)
- Kuehne + Nagel International AG
- NewCold Advanced Cold Logistics
- Constellation Cold Logistics
- DSV
- Nagel-Group
- Culina Group
- Rhenus Logistics
- ID Logistics
- Dachser SE
- Tippmann Group
- Bring Frigo (Posten Bring)
- Gist Ltd.
- DFDS Logistics
- Yusen Logistics Co., Ltd.
- Girteka Logistics
- Norfrig Logistics A/S*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Europe-wide shift toward omni-channel grocery distribution networks (esp. click-and-collect formats)
- 4.2.2 Mandatory EU Green Deal targets accelerating adoption of natural refrigerants (NH3, CO2) in food warehouses
- 4.2.3 Rapid capacity additions in Iberian Peninsula driven by agri-food export growth to Northern Europe
- 4.2.4 Surge in demand for ultra-low-temperature storage for plant-based meat analogues
- 4.2.5 Post-Brexit customs friction boosting demand for cross-docking cold hubs near Calais & Rotterdam
- 4.3 Market Restraints
- 4.3.1 Continental driver shortage inflating refrigerated road freight spot rates
- 4.3.2 High CAPEX for F-gas phasedown compliance across legacy facilities (EU 517/2014)
- 4.3.3 Power-price volatility in Germany & Italy squeezing 3PL margins
- 4.3.4 Limited availability of Class-A refrigerated warehouse sites near Tier-1 ports (Felixstowe, Antwerp, Hamburg)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Buyers
- 4.6.1.1 Bargaining Power of Suppliers
- 4.6.1.2 Threat of New Entrants
- 4.6.1.3 Threat of Substitutes
- 4.6.1.4 Competitive Rivalry
- 4.6.1 Bargaining Power of Buyers
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Frozen Meat & Poultry
- 5.1.2 Fish & Seafood
- 5.1.3 Dairy & Ice-cream
- 5.1.4 Fruits & Vegetables
- 5.1.5 Bakery & Confectionery
- 5.1.6 Ready Meals & Others
- 5.2 By Service Type
- 5.2.1 Refrigerated Storage
- 5.2.2 Refrigerated Transportation
- 5.2.2.1 Road
- 5.2.2.2 Rail
- 5.2.2.3 Sea
- 5.2.2.4 Air
- 5.2.3 Value-Added Services
- 5.3 By Temperature Type
- 5.3.1 Chilled (0-5 °C)
- 5.3.2 Frozen (-18-0 °C)
- 5.3.3 Ambient
- 5.4 By Country
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Netherlands
- 5.4.7 Nordics
- 5.4.8 Poland
- 5.4.9 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Lineage Logistics Holdings, LLC
- 6.4.2 STEF SA
- 6.4.3 Americold Logistics, LLC (AGRO Merchants Europe)
- 6.4.4 DHL Supply Chain (Deutsche Post DHL Group)
- 6.4.5 Kuehne + Nagel International AG
- 6.4.6 NewCold Advanced Cold Logistics
- 6.4.7 Constellation Cold Logistics
- 6.4.8 DSV
- 6.4.9 Nagel-Group
- 6.4.10 Culina Group
- 6.4.11 Rhenus Logistics
- 6.4.12 ID Logistics
- 6.4.13 Dachser SE
- 6.4.14 Tippmann Group
- 6.4.15 Bring Frigo (Posten Bring)
- 6.4.16 Gist Ltd.
- 6.4.17 DFDS Logistics
- 6.4.18 Yusen Logistics Co., Ltd.
- 6.4.19 Girteka Logistics
- 6.4.20 Norfrig Logistics A/S*
7 Market Opportunities & Future Outlook

