PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119878

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119878
United Kingdom Data Center Networking - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United Kingdom data center networking market size is expected to grow from USD 1.35 billion in 2025 to USD 1.45 billion in 2026 and is forecast to reach USD 2.07 billion by 2031 at 7.41% CAGR over 2026-2031.
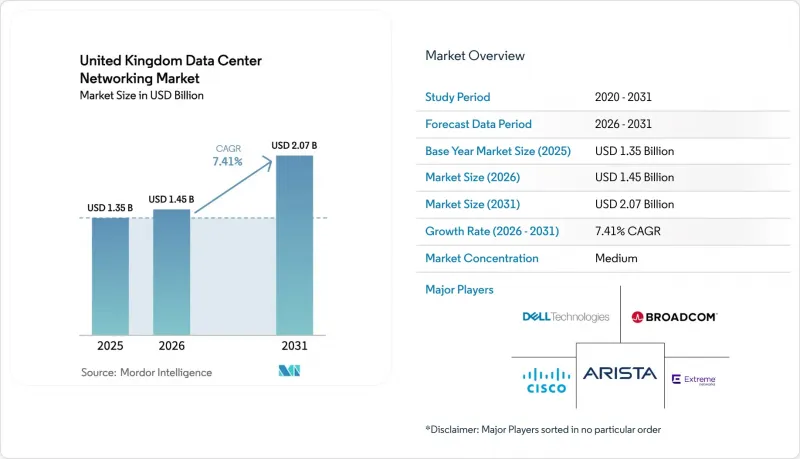
This report is Segmented by Component (Product and Services), End User( IT and Telecommunications, Banking, Financial Services and Insurance (BFSI), Government and Defense and More), Data Center Type (Colocation, Hyperscalers/Cloud Service Providers, Edge/Micro Data Centers), by Bandwidth (<=10 GbE, 25-40 GbE and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Data Center Networking Market Trends and Insights
Surge in AI/ML and HPC driving 400/800 G upgrades
Rising generative-AI clusters require ultra-low-latency fabrics that traditional 10/25 G links cannot sustain. NVIDIA's Spectrum-X platform posts 1.6 X throughput gains versus prior Ethernet fabrics, while Arista's 7060X6 AI Leaf and 7800R4 AI Spine supply up to 51.2 Tbps and 460 Tbps, respectively, to meet pod-level aggregation demand.Meta's adoption of distributed 400 G switches further demonstrates hyperscalers' shift to deeper leaf-spine tiers that shorten east-west paths and minimize tail-flow latency. Cisco's decision to embed Silicon One ASICs inside NVIDIA's Ethernet stack exemplifies convergence between merchant silicon and AI-centric software pipelines that enterprises now consider a prerequisite for future readiness.
Government CNI status and GBP 14 billion AI plan catalyzing spend
The September 2024 CNI designation grants data-center operators priority access to planning and security support, directly unlocking record capital pledges such as Vantage's GBP 12 billion (USD 16.47 billion) multi-campus build and Nscale's USD 2.5 billion sovereign AI facility. The Action Plan also inaugurates AI Growth Zones with dedicated power-allocation corridors, starting in Culham, which accelerates permit approvals that historically delayed capacity. A twentyfold expansion in public compute by 2030, including a GBP 750 million (USD 1029.15 million) Scottish supercomputer, underpins multi-year demand for 800 G interconnects across public-sector and academia workloads.
Grid-power constraints in South-East England
National Grid warns data-center electricity demand could rise sixfold this decade, yet the capital's transmission corridors already operate near capacity. A recent Secretary of State refusal for a West London green belt campus highlights how planning curbs add to grid scarcity, prompting shifts to East London's Romford, where Green Mountain's 30 MW project secured faster hookups. Ofgem's queue-reform program may shave connection wait times, but meaningful substation builds require multi-year cycles, tempering near-term rollout velocities.
Other drivers and restraints analyzed in the detailed report include:
- Cloud and hybrid-multi-cloud traffic explosion
- Sustainability push for spine-leaf architectures
- Cost and lead-time spikes for 800 G optics/ASICs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Products held 76.20% of the United Kingdom data center networking market in 2025, reflecting entrenched demand for switches, routers, application delivery controllers, security appliances, and optical interconnects that anchor physical infrastructure. Cisco's Nexus 9364E-SG2 64-port 800 G switch exemplifies hardware tuned for AI-scale clusters, boasting 51.2 Tbps bandwidth and sizable on-die buffers to mask microbursts. Storage area networks now transition to NVMe-over-Fabrics, while security gateways embed AI-driven inspection engines capable of decrypt-at-line-rate, keeping hardware demand buoyant.
The services segment is smaller yet set for 7.55% CAGR as enterprises outsource design, integration, and managed operations of complex AI fabrics. Consulting firms deploy software-defined controllers such as Cisco ACI or VMware NSX to automate policy across hybrid clouds, whereas open-source OpenDaylight appeals to firms pursuing vendor-agnostic postures. Adoption of silicon-photonics optics like Coherent's 2X400 G-FR4 Lite transceiver further nudges organisations to rely on specialist service providers for optical-layer tuning and lifecycle management.
IT and telecom operators commanded 36.80% share of the United Kingdom data center networking market size in 2025 owing to continual refresh cycles that sustain broadband and cloud service quality. Banks and insurers also invest heavily; Starling Bank's use of Digital Realty interconnects underpins mobile-only operations with sub-20 millisecond transaction latency.
Manufacturing posts the fastest 7.95% CAGR to 2031 as Industry 4.0 ties operational-technology sensors to cloud analytics. Reckitt Group links factory assets via Azure IoT to derive predictive-maintenance insights that cut downtime 10% and energy loads 3%. Government, defence, healthcare, and media verticals likewise pivot to AI-assisted workflows yet trail manufacturing's velocity because of regulatory procurement cycles.
Complete Report Scope:
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- Less than or Equal to 10 GbE
- 25-40 GbE
- 50-100 GbE
- Greater than 100 GbE
List of Companies Covered in this Report:
- Arista Networks Inc.
- Broadcom Inc.
- Cisco Systems Inc.
- Dell Technologies Inc.
- Extreme Networks Inc.
- Hewlett Packard Enterprise (HPE)
- Huawei Technologies Co. Ltd.
- IBM Corporation
- Intel Corporation
- Juniper Networks Inc.
- Lenovo Group Ltd.
- Marvell Technology Group
- NEC Corporation
- NVIDIA Corporation (incl. Cumulus)
- Nokia Corporation
- Schneider Electric SE
- Siemens AG
- Spirent Communications plc
- Supermicro (Super Micro Computer Inc.)
- Corning Incorporated
- CommScope Holding Co.
- Zayo Group
- Equinix Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in AI/ML and HPC driving 400/800 G upgrades
- 4.2.2 Government CNI status and GBP 14 billion AI plan catalyzing spend
- 4.2.3 Cloud and hybrid-multi-cloud traffic explosion
- 4.2.4 Sustainability push for spine-leaf architectures
- 4.2.5 Regional edge DC build-out outside London
- 4.2.6 Silicon-photonic 1.6 T Ethernet roadmap
- 4.3 Market Restraints
- 4.3.1 Grid-power constraints in South-East England
- 4.3.2 Cost and lead-time spikes for 800 G optics/ASICs
- 4.3.3 New energy-/water-use disclosure rules
- 4.3.4 Hyperscaler egress fees and lock-in curb open networking
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Products
- 5.1.1.1 Ethernet Switches
- 5.1.1.2 Routers
- 5.1.1.3 Storage Area Network (SAN)
- 5.1.1.4 Application Delivery Controllers (ADC)
- 5.1.1.5 Network Security Appliances
- 5.1.1.6 Software-Defined Networking (SDN) Controllers
- 5.1.1.7 Optical Interconnects
- 5.1.2 Services
- 5.1.2.1 Installation and Integration
- 5.1.2.2 Training and Consulting
- 5.1.2.3 Support and Maintenance
- 5.1.2.4 Managed Network Services
- 5.1.1 Products
- 5.2 By End-User
- 5.2.1 IT and Telecommunications
- 5.2.2 Banking, Financial Services and Insurance (BFSI)
- 5.2.3 Government and Defense
- 5.2.4 Media and Entertainment
- 5.2.5 Healthcare and Life Sciences
- 5.2.6 Manufacturing and Industrial
- 5.2.7 Other End-Users
- 5.3 By Data-Center Type
- 5.3.1 Colocation
- 5.3.2 Hyperscalers/Cloud Service Providers
- 5.3.3 Edge/Micro Data Centers
- 5.4 By Bandwidth
- 5.4.1 Less than or Equal to 10 GbE
- 5.4.2 25-40 GbE
- 5.4.3 50-100 GbE
- 5.4.4 Greater than 100 GbE
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Arista Networks Inc.
- 6.4.2 Broadcom Inc.
- 6.4.3 Cisco Systems Inc.
- 6.4.4 Dell Technologies Inc.
- 6.4.5 Extreme Networks Inc.
- 6.4.6 Hewlett Packard Enterprise (HPE)
- 6.4.7 Huawei Technologies Co. Ltd.
- 6.4.8 IBM Corporation
- 6.4.9 Intel Corporation
- 6.4.10 Juniper Networks Inc.
- 6.4.11 Lenovo Group Ltd.
- 6.4.12 Marvell Technology Group
- 6.4.13 NEC Corporation
- 6.4.14 NVIDIA Corporation (incl. Cumulus)
- 6.4.15 Nokia Corporation
- 6.4.16 Schneider Electric SE
- 6.4.17 Siemens AG
- 6.4.18 Spirent Communications plc
- 6.4.19 Supermicro (Super Micro Computer Inc.)
- 6.4.20 Corning Incorporated
- 6.4.21 CommScope Holding Co.
- 6.4.22 Zayo Group
- 6.4.23 Equinix Inc.
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

