PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120842

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120842
Thailand Oil And Gas Downstream - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Thailand oil and gas downstream market size is expected to grow from USD 720 million in 2025 to USD 751.7 million in 2026 and is forecast to reach USD 932.2 million by 2031 at 4.41% CAGR over 2026-2031.
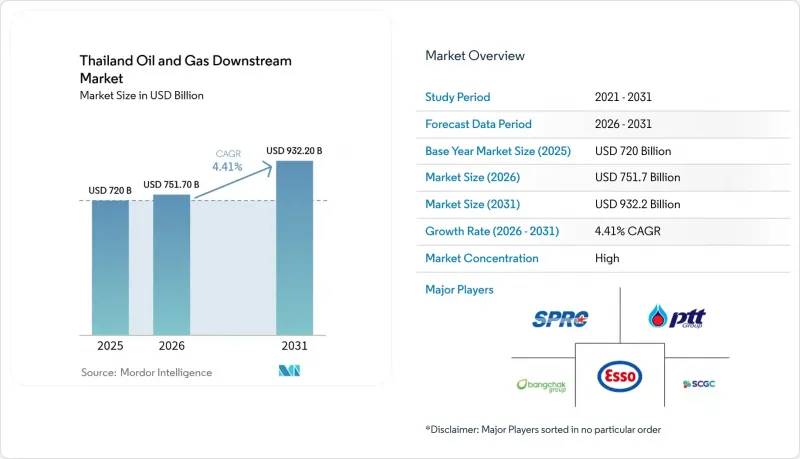
This report is Segmented by Type (Refineries and Petrochemical Plants), Product Type (Refined Petroleum Products, Petrochemicals, and Lubricants), and Distribution Channel (Direct Sales/Wholesale, Distributors/Commercial, and Retail). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Thailand Oil And Gas Downstream Market Trends and Insights
Tourism Recovery Drives Refined Product Demand Resurgence
Jet fuel liftings are nearing pre-pandemic run-rates as international arrivals climb toward the 40 million mark, reviving gasoline and diesel pull through hospitality and logistics services. Last-mile e-commerce fleets add incremental diesel line-haul demand across Bangkok's peri-urban sprawl, extending the utilization window for mid-complexity refineries. Operators that throttled throughput during the pandemic are now executing planned turnarounds early to maximize availability during the 2025-2026 high season. Compared with peers where inbound travel lags, the Thailand oil and gas downstream market enjoys a first-mover demand recovery that supports crack spreads. The country's current 10% EV penetration remains too low to significantly impact aggregate liquid-fuel growth before 2027, creating a multi-year cushion for refiners to recoup upgrade capital expenditures.
Euro-5 Standards Create Margin Expansion Pathway
Mandatory Euro-5 gasoline and diesel specifications, effective January 2027, will widen the pricing gap between compliant and non-compliant supplies by an estimated 5-15%. Complex refineries equipped with new resid-upgrading trains and high-capacity desulfurizers can capture this premium while also reducing carbon tax liabilities. Imported middle-distillate demand from non-compliant ASEAN peers offers an additional outlet, positioning Thailand as a clean-fuel export hub. Project timelines, such as the 400,000 barrels-per-day Clean Fuel Project, are aligned to ramp ahead of enforcement, thereby reinforcing economies of scale. Smaller standalone units face upgrade hurdles, accelerating the shift toward integrated refining and petrochemical super-sites that can recycle hydrogen and process heavier crudes at a lower marginal cost.
China's Petrochemical Overcapacity Pressures Regional Margins
More than 30 million tonnes per annum (mta) of new Chinese ethylene capacity commissioned since 2024 has pulled spot monomer prices toward the bottom quartile of the global cost curve, shrinking Southeast Asian cracker margins to USD 150 per tonne. Thai operators reliant on naphtha feedstock see disproportionate pressure because Chinese complexes run inexpensive coal-to-olefin or ethane-based routes backed by provincial incentives. Margin compression accelerates the strategic pivot toward specialty chemicals, engineering plastics, and downstream integration, where price elasticity is lower, thereby enhancing profitability. While temporary anti-dumping duties offer limited respite, long-run competitiveness hinges on energy-efficiency retrofits and feedstock flexibility-investments already prioritized under the 2023-2027 national petrochemical roadmap.
Other drivers and restraints analyzed in the detailed report include:
- State Oil Plan 2025 Accelerates Efficiency Investments
- Digital Transformation Enhances Retail Profitability
- Carbon Border Measures Threaten Export Competitiveness
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Refineries captured 65.25% of the Thai oil and gas downstream market share in 2025, as 1.24 million barrels per day of installed distillation capacity met resurging mobility fuel demand. The Thailand oil and gas downstream market size for refineries is projected to increase at a 3.68% CAGR through 2031, as Euro-5 compliance premiums and regional jet-fuel deficits support utilization. Petrochemical plants, growing at a 4.85% CAGR, are underpinned by investments such as PTT Global Chemical's USD 4.4 billion "3 Steps Plus" program that adds downstream polyurethane and biodegradable PLA lines. Integrated sites leverage shared utilities and hydrogen networks, trimming operating costs by 5-7% and sharpening their strategic focus toward mixed-feed flexibility. Chinese overcapacity remains the chief headwind; however, Thai complexes counter with specialty niches, including bio-ethylene and high-purity ABS, which command resilient premiums.
A parallel differentiation track is unfolding around carbon intensity. New-build hydrocrackers paired with gas-fired cogeneration units emit 12-15% less CO2 per barrel than decade-old hydroskimmers, thereby cushioning carbon-tax exposure. Retrofits bundling waste-heat recovery and flue-gas desalination further lower compliance costs, attracting green-finance-linked loans at sub-LIBOR spreads. Collectively, these moves help sustain the Thai oil and gas downstream market's refinery core, even as petrochemical earnings outgrow fuel sales.
Complete Report Scope:
- By Type
- Refineries
- Petrochemical Plants
- By Product Type
- Refined Petroleum Products
- Petrochemicals
- Lubricants
- By Distribution Channel
- Direct Sales/Wholesale
- Distributors/Commercial
- Retail
List of Companies Covered in this Report:
- PTT Public Company Limited
- Thai Oil Public Company Limited
- Bangchak Corporation PCL
- Esso (Thailand) Public Company Limited
- Star Petroleum Refining PCL
- IRPC Public Company Limited
- PTT Global Chemical PCL
- SCG Chemicals Co. Ltd
- Caltex (Chevron)
- Royal Dutch Shell PLC
- TotalEnergies Marketing (Thailand)
- PTG Energy PCL
- Indorama Ventures PCL
- BAFS PCL
- OR (PTT Oil & Retail Business)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Gradual recovery in domestic refined-product demand as tourism returns and e-commerce logistics expand
- 4.2.2 Euro-5/clean-fuel upgrades unlocking higher margins post-2026
- 4.2.3 State Oil Plan 2025: carbon-tax phase-in accelerating refinery efficiency projects
- 4.2.4 Rapid service-station network digitalization (EV chargers & retail platforms) boosting downstream profitability
- 4.2.5 Petrochemical feedstock flexibility projects (propane/ethane) mitigating naphtha price shocks
- 4.2.6 Under-the-radar: Sustainable-aviation-fuel (SAF) investments creating a new high-value product pool
- 4.3 Market Restraints
- 4.3.1 China-led petrochemical over-capacity compressing cracker / polymer spreads
- 4.3.2 Rising Single-Pool-Gas feedstock costs squeezing LPG & GSP margins
- 4.3.3 Carbon-border measures (EU CBAM, CORSIA) threatening export economics for high-CO? fuels
- 4.3.4 Under-the-radar: Accelerating EV adoption eroding gasoline demand earlier than forecasts
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Refining Capacity Analysis
- 4.8 Porter's Five Forces
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
- 4.9 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Refineries
- 5.1.2 Petrochemical Plants
- 5.2 By Product Type
- 5.2.1 Refined Petroleum Products
- 5.2.2 Petrochemicals
- 5.2.3 Lubricants
- 5.3 By Distribution Channel
- 5.3.1 Direct Sales/Wholesale
- 5.3.2 Distributors/Commercial
- 5.3.3 Retail
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 PTT Public Company Limited
- 6.4.2 Thai Oil Public Company Limited
- 6.4.3 Bangchak Corporation PCL
- 6.4.4 Esso (Thailand) Public Company Limited
- 6.4.5 Star Petroleum Refining PCL
- 6.4.6 IRPC Public Company Limited
- 6.4.7 PTT Global Chemical PCL
- 6.4.8 SCG Chemicals Co. Ltd
- 6.4.9 Caltex (Chevron)
- 6.4.10 Royal Dutch Shell PLC
- 6.4.11 TotalEnergies Marketing (Thailand)
- 6.4.12 PTG Energy PCL
- 6.4.13 Indorama Ventures PCL
- 6.4.14 BAFS PCL
- 6.4.15 OR (PTT Oil & Retail Business)
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

