PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121543

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121543
Automotive Electro-Hydraulic Power Steering - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
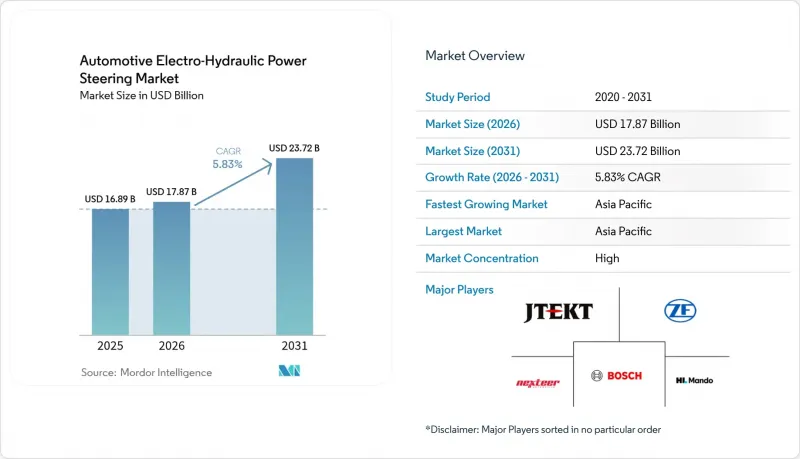
According to Mordor Intelligence, the automotive electro-hydraulic power steering market size was valued at USD 16.89 billion in 2025 and estimated to grow from USD 17.87 billion in 2026 to reach USD 23.72 billion by 2031, at a CAGR of 5.83% during the forecast period (2026-2031).
This report is Segmented by Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Component Type (Steering Motors, Hydraulic Pumps, and More ), Propulsion ( Internal Combustion Engine, and More), Sales Channel (Original Equipment Manufacturer (OEM), Aftermarket), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Electro-Hydraulic Power Steering Market Trends and Insights
Growing EV Production and Higher Auxiliary-12 V Loads
Escalating battery electric and plug-in hybrid volumes raise auxiliary loads for climate, infotainment, and safety functions, which amplifies the efficiency gap between on-demand EHPS pumps and continuously driven hydraulic pumps. Global EV sales reached 14 million units in 2024, with battery electric vehicles taking 73% of deliveries, creating a sizeable addressable base for EHPS systems. Commercial segments follow a similar path as electric buses logged 30% shipment growth in 2024, encouraging the adoption of energy-saving steering solutions. The engineering priority now focuses on pump control algorithms coordinating with vehicle energy management to minimize current draw during steady-state cruising.
OEM Demand for Steering Redundancy for L3+ ADAS
Level 3 and above automated driving creates fail-operational steering requirements under ISO 26262, stipulating ASIL-D integrity for steering control. EHPS architecture, with its dual electric motor and hydraulic assist paths, delivers the redundancy and fault tolerance needed to maintain steerability during power interruptions or actuator faults. Recent production launches such as the steer-by-wire solution in NIO's ET9 highlight how EHPS modules pair with electronic actuation to achieve variable steering ratios and emergency intervention. Suppliers, therefore, align R&D toward diagnostics, sensor fusion, and fallback strategies that satisfy functional safety audits
Supply Chain Volatility of Rare-Earth Permanent Magnet Motors
Neodymium, dysprosium, and terbium supply remains concentrated in small mines, with China accounting for more than 60% of refined output. Export licensing changes in 2024 raised spot prices and strained inventory, prompting automakers to review magnet-free synchronous reluctance motors and to dual-source pump assemblies. Steering suppliers are lengthening safety stocks and entering direct offtake agreements with miners to stabilize lead times.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Electrification of Light Commercial Vehicles
- Integration of Steer-By-Wire Modules With EHPS Pumps
- Up-Front Cost Premium vs Conventional HPS
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars commanded 63.86% of the electric hydraulic power steering market in 2025 on the strength of widespread adoption across compact, mid-size, and luxury platforms. Carmakers integrate EHPS to unlock stop-start compatibility, mild hybrid gains, and growing ADAS content. Electric hydraulic power steering market size for light commercial vehicles is projected to expand at a 7.18% CAGR because parcel fleets favor energy savings during urban duty cycles.
The passenger car share reflects efficient scale, model refresh cadence, and high configuration volumes that absorb the added cost of electronic pumps. Commercial vehicle programs show faster unit growth as final mile delivery regulations tighten in China, Europe, and several United States states. Heavy trucks and buses trail but represent future upside once battery pack economics and high voltage steering actuation converge.
Steering motors held 36.23% electric hydraulic power steering market share in 2025. Their high material value and critical performance role anchor the component mix. Sensors and torque modules will record a 7.61% CAGR through 2031, driven by ISO 26262 redundancy targets that double the number of position and torque sensing channels per system.
Permanent magnet brushless motors remain the industry standard because they deliver high power density and rapid response. Suppliers are investing in ferrite-based or reluctance designs to sidestep rare-earth exposure. Control ECUs migrate toward higher bandwidth microcontrollers as steer-by-wire software layers expand, while sealed pump housings incorporate integrated cooling jackets to extend duty cycles.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Buses and Coaches
- Off-highway and Specialty Vehicles
- By Component Type
- Steering Motors
- Hydraulic Pumps
- Sensors and Torque Modules
- ECU / Controllers
- Reservoirs, Hoses and Others
- By Propulsion Type
- Internal-Combustion Engine (ICE)
- Hybrid Electric Vehicle (HEV)
- Battery Electric Vehicle (BEV)
- Plug-in Hybrid Electric Vehicles
- Fuel-Cell Electric Vehicle (FCEV)
- By Sales Channel
- Original Equipment Manufacturer (OEM)
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Vietnam
- Philippines
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific remains the clear demand center. The region accounted for 47.12% electric hydraulic power steering market share in 2025 and is projected to expand at an 8.63% CAGR through 2031, making it the largest and fastest-growing territory. China's battery-electric and plug-in hybrid production scale drives high pump volumes. India's FAME-II and PLI schemes channel local sourcing toward domestic steer-by-wire and pump facilities. Japan contributes high-reliability sensors and motor controls that meet ISO 26262 targets for export models. Regional suppliers benefit from government incentives that lower landed costs and shorten supply chains for OEM plants clustered in Shanghai, Guangzhou, Chennai, and Nagoya.
North America follows with steady expansion as emissions rules tighten. The EPA's Multi-Pollutant Standards and California's Advanced Clean Cars II program compel automakers to electrify auxiliaries, including steering, to meet fleet targets. Battery-electric delivery van adoption has doubled since 2024, pulling EHPS content into parcel and grocery fleets. Domestic automakers also hedge rare-earth risk by funding ferrite and reluctance motor research, which supports regional electric hydraulic power steering market size resilience against supply shocks. Canada's clean-transport credits mirror United States policy and reinforce cross-border production synergies.
Europe anchors premium vehicle innovation. German, Swedish, and French brands are rolling out steer-by-wire platforms that integrate EHPS pumps as safety-redundant actuators, and ZF began series production for a Chinese luxury marque in early 2025. The European Union target of a 55% fleet-wide CO2 cut by 2030 keeps pressure on suppliers to deliver efficiency gains at component level. As luxury and performance segments migrate to 800 V architectures, EHPS modules with smart energy-recovery algorithms complement brake-by-wire and active suspension systems. Eastern Europe and the Middle East provide emerging assembly bases, but infrastructure gaps and price sensitivity temper near-term penetration, positioning Asia-Pacific as the principal growth engine through the decade.
- JTEKT Corporation
- Robert Bosch GmbH
- ZF Friedrichshafen AG
- Nexteer Automotive Corporation
- Mando Corporation
- NSK Ltd.
- Continental AG
- Thyssenkrupp Presta AG
- Hitachi Astemo
- Showa Corporation
- Knorr-Bremse Commercial Vehicle Systems GmbH
- Shanghai OE Industrial Co., Ltd. (Brogen EV Solutions)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 OEM Demand For Steering Redundancy For L3+ ADAS
- 4.2.2 Growing EV Production and Higher Auxiliary-12 V Loads
- 4.2.3 Rapid Electrification Of Light Commercial Vehicles (Elcv)
- 4.2.4 Tightening CO2 / CAFE Regulations Pushing Steering Efficiency
- 4.2.5 Integration Of Steer-By-Wire Modules With EHPS Pumps
- 4.2.6 Local Sourcing Incentives In China and India (PLI, MIIT, FAME-II)
- 4.3 Market Restraints
- 4.3.1 Supply-Chain Volatility Of Rare-Earth PM Motors
- 4.3.2 Up-Front Cost Premium Vs. Conventional HPS
- 4.3.3 Reliability Concerns In High-Temperature Duty Cycles
- 4.3.4 Competition From Full-Electric Power Steering (EPS) In B-/C-Segment Cars
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Light Commercial Vehicles
- 5.1.3 Heavy Commercial Vehicles
- 5.1.4 Buses and Coaches
- 5.1.5 Off-highway and Specialty Vehicles
- 5.2 By Component Type
- 5.2.1 Steering Motors
- 5.2.2 Hydraulic Pumps
- 5.2.3 Sensors and Torque Modules
- 5.2.4 ECU / Controllers
- 5.2.5 Reservoirs, Hoses and Others
- 5.3 By Propulsion Type
- 5.3.1 Internal-Combustion Engine (ICE)
- 5.3.2 Hybrid Electric Vehicle (HEV)
- 5.3.3 Battery Electric Vehicle (BEV)
- 5.3.4 Plug-in Hybrid Electric Vehicles
- 5.3.5 Fuel-Cell Electric Vehicle (FCEV)
- 5.4 By Sales Channel
- 5.4.1 Original Equipment Manufacturer (OEM)
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Indonesia
- 5.5.4.6 Vietnam
- 5.5.4.7 Philippines
- 5.5.4.8 Australia
- 5.5.4.9 New Zealand
- 5.5.4.10 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 South Africa
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 JTEKT Corporation
- 6.4.2 Robert Bosch GmbH
- 6.4.3 ZF Friedrichshafen AG
- 6.4.4 Nexteer Automotive Corporation
- 6.4.5 Mando Corporation
- 6.4.6 NSK Ltd.
- 6.4.7 Continental AG
- 6.4.8 Thyssenkrupp Presta AG
- 6.4.9 Hitachi Astemo
- 6.4.10 Showa Corporation
- 6.4.11 Knorr-Bremse Commercial Vehicle Systems GmbH
- 6.4.12 Shanghai OE Industrial Co., Ltd. (Brogen EV Solutions)
7 Market Opportunities & Future Outlook

