PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121635

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121635
Middle East And Africa Soft Drinks Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Middle East and Africa soft drinks packaging market size in 2026 is estimated at USD 12.63 billion, growing from 2025 value of USD 12.07 billion with 2031 projections showing USD 15.81 billion, growing at 4.60% CAGR over 2026-2031.
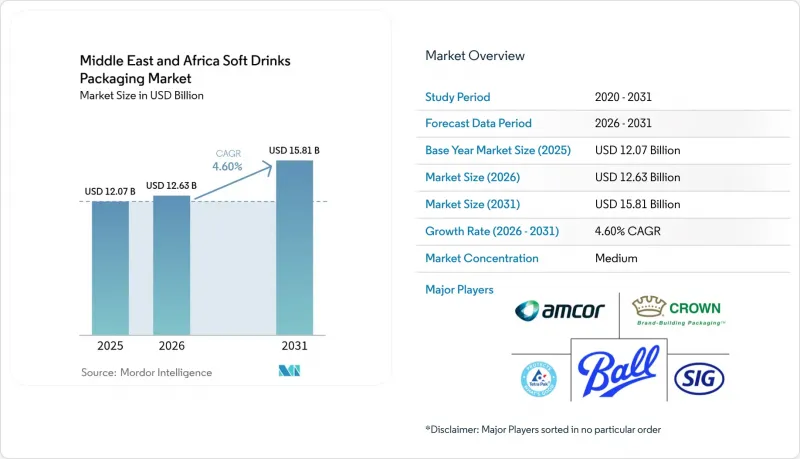
This report is Segmented by Primary Material Used (Plastic, Paper and Paperboard, and More), Packaging Format (Bottles, Cans, and More), Beverage Type (Bottled Water, Juices and Nectars, and More), Pack Capacity (<=330 ML, 331-500 ML, 501-1000 ML, and >1000 ML), and Region. The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Soft Drinks Packaging Market Trends and Insights
Rising Bottled-Water Consumption in GCC
Persistent water-scarcity concerns and variable municipal supply quality continue to steer Gulf households toward packaged hydration. Saudi Arabia's National Water Strategy 2030 has prioritized diversified sourcing, indirectly sustaining bottled water demand as utilities modernize. Sidel's 80,000-bph PET lines, deployed with regional bottlers, illustrate how plant investments capture this surge. A youthful population, more than 60% under 30, gravitates to premium and functional waters, lifting packaging value per unit and reinforcing the primacy of PET containers in the Middle East and Africa soft drinks packaging market.
Surge in Demand for Convenience and On-the-Go Single-Serve Packs
Compressed work routines and the expansion of convenience retail have made sub-330 mL packs commonplace. Unit volumes in this size band are rising at a 5.8% CAGR, outpacing larger formats as consumers blend portion control with mobility. SIG's DomeMini carton bottle (180-350 mL) pairs portability with aseptic integrity, making carton options viable for on-the-go consumption. Uptake concentrates in Riyadh, Dubai, and Johannesburg, where busy lifestyles and food-service channels intersect, propelling the Middle East and Africa soft drinks packaging market toward higher-margin, single-serve applications.
Heightened EPR Fees and Potential Plastic-Tax Roll-out in UAE and KSA
Pilot EPR schemes in the UAE already lift compliance costs for high-volume segments such as bottled water. Legislators plan broader single-use plastic bans by 2026, sharpening price pressure on PET packaging. Saudi Arabia is evaluating comparable levies within its circular-economy roadmap, injecting uncertainty that could delay capital deployment or push brands toward aluminum and paperboard options. The Middle East and Africa soft drinks packaging market accordingly faces margin compression on legacy formats while sustainable alternatives gain traction.
Other drivers and restraints analyzed in the detailed report include:
- Hydrocarbon-to-Polymer Capacity Expansions Lowering PET Cost
- Brand Shift Toward Tethered and Lightweight Caps
- Chronic Deficit in Food-Grade rPET Collection Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic retained a 52.05% share of the Middle East and Africa soft drinks packaging market in 2025, supported by abundant Gulf feedstocks and established PET blowing infrastructure. Favorable resin economics make PET the default for bottled water, carbonates, and sports drinks. However, paper and paperboard registered a 6.05% CAGR, accelerating on the back of plant-based beverage launches that leverage cartons' extended shelf life and sustainable positioning.
Rising EPR fees and tethered-cap requirements push brand owners to diversify substrates, elevating carton suppliers as strategic partners. SIG's Egyptian recycling pilot and Pulpac collaborations on paper closures exemplify innovation cycles aimed at lowering total environmental impact. Glass continues to serve premium juice and craft soda lines, whereas aluminum garners attention for energy drinks and premium waters. The material mix shift underscores how regulatory and consumer expectations reshape vendor roadmaps within the Middle East and Africa soft drinks packaging market.
Bottles commanded 61.10% of 2025 revenues, anchored by the widespread PET base and familiarity among fillers and consumers. Large-scale lines such as Sidel's 80,000-bph systems keep throughput high and unit costs low. Yet cartons and aseptic bricks grew fastest, clocking a 5.78% CAGR as dairy alternatives, probiotic drinks, and premium juices move into ambient-stable packs that signal sustainability.
SIG's DomeMini bottle confirms how carton technology now targets traditionally plastic-dominated convenience occasions. Aluminum cans hold steady due to infinite recyclability, particularly for carbonates and energy drinks promoted through sports marketing. Pouches and sachets serve rural and price-sensitive shoppers, highlighting the divergent needs the Middle East and Africa soft drinks packaging market must satisfy across socio-economic tiers.
Complete Report Scope:
- By Primary Material Used
- Plastic
- Paper and Paperboard
- Glass
- Metal
- Others
- By Packaging Format
- Bottles
- Cans
- Cartons / Aseptic Bricks
- Pouches and Sachets
- Others
- By Beverage Type
- Bottled Water
- Juices and Nectars
- Carbonated Soft Drinks
- Ready-to-Drink Tea and Coffee
- Sports and Energy Drinks
- Others
- By Pack Capacity
- <=330 mL
- 331 - 500 mL
- 501 - 1 000 mL
- >1 000 mL
- By Region
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Tetra Pak International SA
- SIG Group AG
- Amcor plc
- Ball Corporation
- Crown Holdings Inc.
- ALPLA Werke Alwin Lehner GmbH and Co KG
- Plastipak Holdings Inc.
- Nampak Ltd.
- Takween Advanced Industries Co.
- Arabian Plastic Industrial Co. (Apico)
- GZI Industries Ltd.
- Huhtamaki Oyj
- Owens-Illinois Inc.
- Ardagh Metal Packaging S.A.
- Krones AG
- Sidel Group
- Mondi plc
- Greif Inc.
- Vetropack Holding AG
- AL-Jomaih Beverage Cans and Ends Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising bottled-water consumption in GCC
- 4.2.2 Surge in demand for convenience and on-the-go single-serve packs
- 4.2.3 Hydrocarbon-to-polymer capacity expansions lowering PET cost
- 4.2.4 Brand shift toward tethered and lightweight caps to meet EU-style rules
- 4.2.5 Localisation incentives under Saudi Vision 2030 encouraging can lines
- 4.2.6 Growth of aseptic filling hubs for fermented and plant-based drinks
- 4.3 Market Restraints
- 4.3.1 Heightened EPR fees and potential plastic-tax roll-out in UAE and KSA
- 4.3.2 Chronic deficit in food-grade rPET collection infrastructure
- 4.3.3 Water-scarcity policies discouraging high-volume PET bottling licences
- 4.3.4 Rising aluminium feedstock price volatility impacting can adoption
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products and Services
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Primary Material Used
- 5.1.1 Plastic
- 5.1.2 Paper and Paperboard
- 5.1.3 Glass
- 5.1.4 Metal
- 5.1.5 Others
- 5.2 By Packaging Format
- 5.2.1 Bottles
- 5.2.2 Cans
- 5.2.3 Cartons / Aseptic Bricks
- 5.2.4 Pouches and Sachets
- 5.2.5 Others
- 5.3 By Beverage Type
- 5.3.1 Bottled Water
- 5.3.2 Juices and Nectars
- 5.3.3 Carbonated Soft Drinks
- 5.3.4 Ready-to-Drink Tea and Coffee
- 5.3.5 Sports and Energy Drinks
- 5.3.6 Others
- 5.4 By Pack Capacity
- 5.4.1 <=330 mL
- 5.4.2 331 - 500 mL
- 5.4.3 501 - 1 000 mL
- 5.4.4 >1 000 mL
- 5.5 By Region
- 5.5.1 Middle East
- 5.5.1.1 Saudi Arabia
- 5.5.1.2 United Arab Emirates
- 5.5.1.3 Qatar
- 5.5.1.4 Rest of Middle East
- 5.5.2 Africa
- 5.5.2.1 South Africa
- 5.5.2.2 Egypt
- 5.5.2.3 Nigeria
- 5.5.2.4 Rest of Africa
- 5.5.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Tetra Pak International SA
- 6.4.2 SIG Group AG
- 6.4.3 Amcor plc
- 6.4.4 Ball Corporation
- 6.4.5 Crown Holdings Inc.
- 6.4.6 ALPLA Werke Alwin Lehner GmbH and Co KG
- 6.4.7 Plastipak Holdings Inc.
- 6.4.8 Nampak Ltd.
- 6.4.9 Takween Advanced Industries Co.
- 6.4.10 Arabian Plastic Industrial Co. (Apico)
- 6.4.11 GZI Industries Ltd.
- 6.4.12 Huhtamaki Oyj
- 6.4.13 Owens-Illinois Inc.
- 6.4.14 Ardagh Metal Packaging S.A.
- 6.4.15 Krones AG
- 6.4.16 Sidel Group
- 6.4.17 Mondi plc
- 6.4.18 Greif Inc.
- 6.4.19 Vetropack Holding AG
- 6.4.20 AL-Jomaih Beverage Cans and Ends Co.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

