PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123508

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123508
Global Blood Warmer Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the blood warmer devices market size is expected to grow from USD 1.35 billion in 2025 to USD 1.45 billion in 2026 and is forecast to reach USD 2.05 billion by 2031 at 7.19% CAGR over 2026-2031.
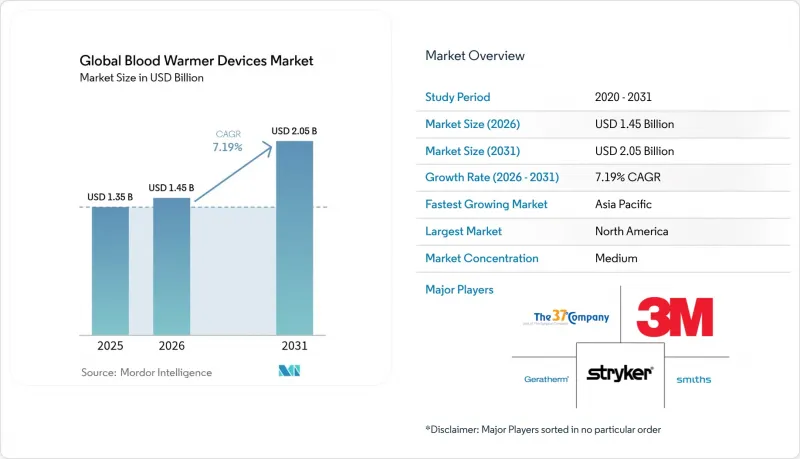
This report is Segmented by Product Type (Intravenous In-Line, Surface/Convective Fluid and More), by Modality (Portable and Stationary), by Application (Surgery & Peri-Operative Care, Critical Care (ICU/ER) and More) and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Blood Warmer Devices Market Trends and Insights
Rising Trauma & Emergency Surgery Volumes
Global trauma caseloads keep climbing, driven by road accidents, ageing populations and prolonged conflict zones. The U.S. Joint Trauma System recorded a 44% drop in battlefield deaths once automated blood-warming logistics became standard practice health.mil. Emergency-department studies show prehospital transfusion programs could benefit as many as 900,000 U.S. patients annually, underscoring the need for reliable warmers that avert hypothermia-related mortality. Mass-transfusion protocols now embed warming requirements, making the blood warmer devices market central to hospital trauma-care budgets.
Stringent Peri-operative Normothermia Guidelines
Updated AORN guidelines mandate continuous warming from pre-induction through recovery, threatening legal exposure for facilities that fail to comply. Complementary FDA test-protocols released in March 2024 standardise thermal-effect evaluation, accelerating procurement of systems with automatic shut-off and +-0.1 °C accuracy. Clinical evidence ties uncorrected peri-operative hypothermia to 9% higher complication rates and a 14% lift in acute kidney injury, further motivating hospitals to deploy state-of-the-art devices.
Risk of Hemolysis & Protein Denaturation
Temperatures exceeding 46 °C cause measurable red-cell rupture, while proteins begin denaturing at 43 °C after two-hour exposure. Trials on irradiated leukoreduced units warmed to 60 °C recorded sharp potassium release, elevating cardiac-arrest risk in neonates. Device makers now integrate triple sensors, automatic bypass and instant shut-off, which add cost and raise validation hurdles but are essential for patient safety.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Portable Warmers in Military & EMS
- Integration of IoT Temperature Logging for Compliance
- Capital-Cost Sensitivity in LMIC Hospitals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Intravenous in-line systems controlled 40.02% of 2025 revenue, demonstrating the blood warmer devices market preference for seamless integration and tight temperature control. Units such as 3M's Ranger 245 reach set-point in 45 seconds and manage concurrent infusions between 37 °C and 41 °C, making them the workhorse for operating-theatre and trauma-bay protocols. Surface warmers, although niche in absolute sales, register an 8.05% CAGR, propelled by EMS crews that value flexible wrapping pads deployable inside ambulances or aircraft.
Clinical evidence underlines why in-line models dominate. Comparative trials show fresh blood warmed at 47 °C for one hour displayed no cell damage, whereas immersion baths showed higher variability. Cabinet units such as Sarstedt's SAHARA-III still serve blood banks needing large-volume processing without water immersion, yet growth pivots to smaller, agile devices for point-of-care use.
Complete Report Scope:
- by Product Type (Value)
- Intravenous In-Line
- Surface/Convective Fluid
- Enclosure Cabinet Warmers
- by Modality (Value)
- Portable
- Stationary
- by Application (Value)
- Surgery & Peri-operative Care
- Critical Care (ICU/ER)
- Blood Banks & Apheresis Centers
- Military & EMS Use
- Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America led with 44.68% of 2025 revenue, reflecting mature reimbursement, stringent FDA oversight and a well-funded EMS network that already fields blood on board in 23 states. Medicare payment updates for 2025-2026 increase quality incentives tied to normothermia compliance, driving new hospital upgrades federalregister.gov. Pentagon innovations such as the Automated Battlefield Trauma System, which delivered a 44% mortality reduction, spill over into civilian care and sustain upstream demand.
Europe shows balanced expansion as harmonised Medical Device Regulation and intensive-care society guidelines reinforce thermal-management standards. Consensus on targeted temperature control for traumatic brain injury, adopted by leading centres in Germany, France and the United Kingdom, secures a steady cadence of procurement despite supply-chain frictions triggered by regional geopolitical tensions
Asia-Pacific delivers the fastest compound growth at 9.98%, propelled by massive trauma caseloads and government infrastructure programmes in China, India and Southeast Asia. While venture funding dips curtailed some local start-ups, state procurement of battlefield-grade equipment after natural-disaster responses keeps the adoption curve steep. Price-sensitive public hospitals increasingly trial lower-cost portable units, opening new avenues for manufacturers that can tier offerings without diluting accuracy.
- 3M
- Stryker Corporation (Belmont)
- ICU Medical
- Barkey
- Belmont Medical Technologies
- Fresenius
- GE HealthCare Technologies Inc.
- Gentherm Medical
- Vyaire Medical
- Princeton Medical Scientific Inc.
- Emit Corporation
- The 37Company B.V.
- SOMATEX Medical Technologies GmbH
- Keewell Medical Technology Co. Ltd.
- Qingdao Flux Medical
- ThermoGenesis Holdings Inc.
- Sarstedt
- Smiths Group
- Inspiration Healthcare Group plc
- Enthermics Medical Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising trauma & emergency surgery volumes
- 4.2.2 Stringent peri-operative normothermia guidelines
- 4.2.3 Adoption of portable, battery-operated warmers in military & EMS
- 4.2.4 Integration of IoT temperature logging for compliance
- 4.2.5 AI-assisted real-time perfusion monitoring (under-the-radar)
- 4.2.6 Stem-cell & apheresis therapy growth needing large-volume warming (under-the-radar)
- 4.3 Market Restraints
- 4.3.1 Risk of hemolysis & protein denaturation at supra-physiologic temps
- 4.3.2 Capital cost sensitivity in LMIC hospitals
- 4.3.3 Disposable set incompatibility across brands (under-the-radar)
- 4.3.4 Supply-chain fragility for heating elements rare-earths (under-the-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 by Product Type (Value)
- 5.1.1 Intravenous In-Line
- 5.1.2 Surface/Convective Fluid
- 5.1.3 Enclosure Cabinet Warmers
- 5.2 by Modality (Value)
- 5.2.1 Portable
- 5.2.2 Stationary
- 5.3 by Application (Value)
- 5.3.1 Surgery & Peri-operative Care
- 5.3.2 Critical Care (ICU/ER)
- 5.3.3 Blood Banks & Apheresis Centers
- 5.3.4 Military & EMS Use
- 5.4 Geography (Value)
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 3M Company
- 6.3.2 Stryker Corporation (Belmont)
- 6.3.3 ICU Medical Inc. (Smiths Medical)
- 6.3.4 Barkey GmbH & Co. KG
- 6.3.5 Belmont Medical Technologies
- 6.3.6 Fresenius SE & Co. KGaA
- 6.3.7 GE HealthCare Technologies Inc.
- 6.3.8 Gentherm Medical
- 6.3.9 Vyaire Medical Inc.
- 6.3.10 Princeton Medical Scientific Inc.
- 6.3.11 Emit Corporation
- 6.3.12 The 37Company B.V.
- 6.3.13 SOMATEX Medical Technologies GmbH
- 6.3.14 Keewell Medical Technology Co. Ltd.
- 6.3.15 Qingdao Flux Medical
- 6.3.16 ThermoGenesis Holdings Inc.
- 6.3.17 Sarstedt AG & Co. KG
- 6.3.18 Smiths Group plc
- 6.3.19 Inspiration Healthcare Group plc
- 6.3.20 Enthermics Medical Systems
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

