PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125616

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125616
United States Industrial Wood Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United States industrial wood coatings market size is expected to grow from 276.39 kilotons in 2025 to 284.29 kilotons in 2026 and is forecast to reach 331.98 kilotons by 2031 at a 3.15% CAGR over 2026-2031.
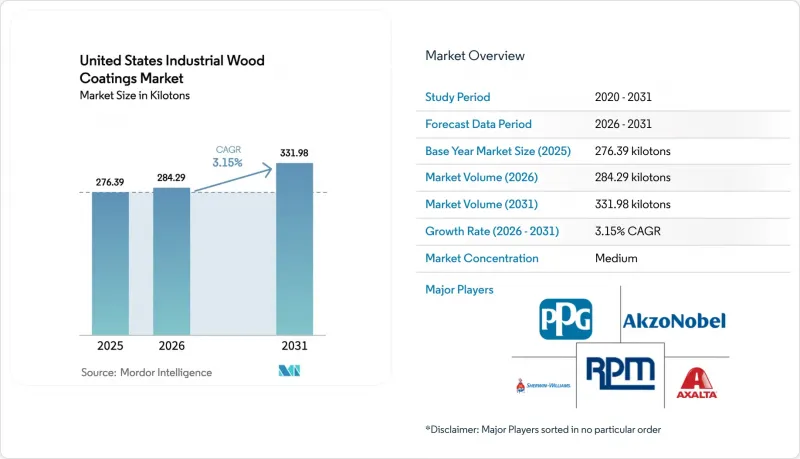
This report is Segmented by Resin Type (Epoxy, Acrylic, Alkyd, Polyurethane, Polyester, and Others), Technology (Water-Borne, Solvent-Borne, UV-Curable, and Powder), End-User Industry (Wooden Furniture, Joinery, Flooring and Decking, and Others). Market Forecasts are Provided in Terms of Volume (Tons).
United States Industrial Wood Coatings Market Trends and Insights
Rising U.S. Furniture and Cabinetry Production
Domestic furniture output slipped 4.6 % between Q3 2024 and Q3 2025, yet commercial office furniture and custom cabinetry volumes expanded 3-5 %, underscoring a shift toward made-to-order programs that favor fast-cure water-borne coats. Mill shops are shortening order-to-ship windows to 24-48 hours, leaving little tolerance for solvent flash-off. As a result, wooden furniture demand is tracking a 3.61 % CAGR and steadily widening its contribution to overall industrial wood coatings market growth. Suppliers are reallocating research and development budgets toward high-solids acrylics and low-temperature UV systems that cure in minutes, enabling shops to reclaim floor space and accelerate cash cycles. The production bifurcation also incentivizes inventory-light business models that require universally compliant, multi-substrate products.
Residential Remodeling Boom Post-COVID
Remodeling outlays stayed elevated through 2025, buoyed by accumulated home-equity gains even as borrowing costs edged higher. Cabinet-refacing contractors-now 12-15 % of total coating volume-prefer water-borne acrylics and LED-UV systems that allow same-day re-installation. The Congressional Budget Office's forecast of 1.68 million annual housing starts from 2025-2029 underpins sustained millwork demand well into the next decade. The remodeling channel's appetite for zero-VOC, odor-free finishes is accelerating the transition away from solvent-heavy legacies within the industrial wood coatings market. Regional paint makers with agile tinting infrastructure are capitalizing on this shift, picking up share from national brands encumbered by big-box distribution.
Stringent Federal and State VOC/HAP Ceilings (SCAQMD, CARB)
Maintaining discrete SKUs for California, the Northeast OTR, and the broader U.S. fragments production runs and lifts unit costs. Each new formulation cycle demands 12-18 months and USD 50,000-150,000 in lab, field, and emissions testing. Smaller brands consequently withdraw from complex jurisdictions or cede toll-manufacturing to national competitors, hastening consolidation. The regulatory squeeze weighs heaviest on solvent-borne polyurethanes, nudging specifiers toward water-borne systems that meet limits yet trade off peak durability. Over time, the compliance gap will narrow the addressable solvent-borne pool inside the industrial wood coatings market.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push Toward Low-VOC Formulations (OTC/EPA)
- Adoption of Robotics and Conveyorized Spray Lines
- Volatile Petro-Resin and TiO2 Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyurethane held 60.15 % of 2025 volume and will track a 3.69 % CAGR to 2031, sustained by abrasion-resistant flooring and sun-fast exterior joinery. The industrial wood coatings market size for polyurethane is projected to expand in tandem with Build-to-Rent demand for durable, factory-finished millwork. Water-borne acrylics, though faster curing, cede high-traffic niches to polyurethanes but win interior cabinetry jobs where odor and insurance costs matter more than ultimate scratch resistance. Alkyds persist in decorative glazing, while epoxies protect laboratory benches and food-service tables from chemical abuse. Polyester resins, paired with UV-cure and low-temperature powder, are opening throughput gains five to ten times higher than legacy bake systems, creating sub-segments where performance and sustainability align.
Specialty nitrocellulose lacquers remain staples for musical instruments, enabling thin-film builds that resonate acoustically and ease refinishing. These niche chemistries command two to three times the per-gallon price of mainstream products, sustaining robust margins despite negligible volume. Overall, polyurethanes will retain the largest slice of the industrial wood coatings market share, yet the value growth narrative will steadily migrate toward water-borne, UV, and powder innovations that carry higher price points and regulatory headroom.
Complete Report Scope:
- By Resin Type
- Epoxy
- Acrylic
- Alkyd
- Polyurethane
- Polyester
- Others (Nitrocellulose, etc.)
- By Technology
- Water-Borne
- Solvent-Borne
- UV-Curable
- Powder
- By End-User Industry
- Wooden Furniture
- Joinery (Windows, Doors, Molding)
- Flooring and Decking
- Others (Musical instruments, Sports goods)
List of Companies Covered in this Report:
- Akzo Nobel N.V.
- Axalta Coating Systems
- Benjamin Moore & Co.
- CERAMIC INDUSTRIAL COATINGS
- Diamond Vogel
- Hempel A/S
- ICP Industrial Solutions Group
- Jotun A/S
- PPG Industries Inc.
- RPM International Inc.
- Stiles Industrial Coatings
- Teknos Group
- The Sherwin William Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising U.S. furniture and cabinetry production
- 4.2.2 Residential remodeling boom post-COVID
- 4.2.3 Regulatory push toward low-VOC formulations (OTC/EPA)
- 4.2.4 Adoption of robotics and conveyorised spray lines
- 4.2.5 "Build-to-Rent" housing boosts pre-finished millwork
- 4.3 Market Restraints
- 4.3.1 Stringent federal and state VOC/HAP ceilings (SCAQMD, CARB)
- 4.3.2 Volatile petro-resin and TiO2 prices
- 4.3.3 Intermittent polyester-polyol shortages
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Resin Type
- 5.1.1 Epoxy
- 5.1.2 Acrylic
- 5.1.3 Alkyd
- 5.1.4 Polyurethane
- 5.1.5 Polyester
- 5.1.6 Others (Nitrocellulose, etc.)
- 5.2 By Technology
- 5.2.1 Water-Borne
- 5.2.2 Solvent-Borne
- 5.2.3 UV-Curable
- 5.2.4 Powder
- 5.3 By End-User Industry
- 5.3.1 Wooden Furniture
- 5.3.2 Joinery (Windows, Doors, Molding)
- 5.3.3 Flooring and Decking
- 5.3.4 Others (Musical instruments, Sports goods)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/ Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)}
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Axalta Coating Systems
- 6.4.3 Benjamin Moore & Co.
- 6.4.4 CERAMIC INDUSTRIAL COATINGS
- 6.4.5 Diamond Vogel
- 6.4.6 Hempel A/S
- 6.4.7 ICP Industrial Solutions Group
- 6.4.8 Jotun A/S
- 6.4.9 PPG Industries Inc.
- 6.4.10 RPM International Inc.
- 6.4.11 Stiles Industrial Coatings
- 6.4.12 Teknos Group
- 6.4.13 The Sherwin William Company
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

