PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2071362
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2071362
Semiconductor Plant Construction Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
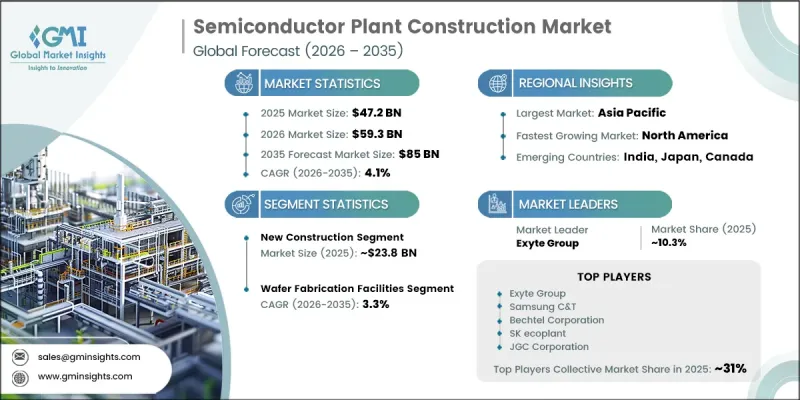
The Global Semiconductor Plant Construction Market was valued at USD 47.2 billion in 2025 and is estimated to grow at a CAGR of 4.1% to reach USD 85 billion by 2035.
Growth is fueled by rapid digital transformation, increasing semiconductor intensity in next-generation technologies, and large-scale investments aimed at strengthening supply chain resilience. Manufacturers are aggressively expanding production capacity through both new facility development and modernization of existing fabs to meet escalating global demand for high-performance chips. Government-led initiatives are also playing a crucial role, with policy support, incentives, and funding programs designed to enhance domestic semiconductor ecosystems and reduce reliance on concentrated production hubs. Wafer fabrication facilities remain central to the industry, given their role in enabling precision-driven manufacturing processes required for advanced integrated circuits. Continuous innovation in process nodes, coupled with increasing adoption of energy-efficient and high-yield production environments, is further driving construction activity across global semiconductor ecosystems.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $47.2 Billion |
| Forecast Value | $85 Billion |
| CAGR | 4.1% |
The new construction segment accounted for USD 23.8 billion in 2025 and is projected to grow at a CAGR of 2.6% through 2035. This segment continues to dominate due to the expansion of global chip manufacturing capacity and the rising need for advanced production infrastructure. Strong investments from both public and private stakeholders are supporting greenfield fabrication projects aimed at enhancing supply chain stability and meeting growing demand from multiple end-use industries.
The wafer fabrication facilities segment held 77.7% share in 2025 and is expected to grow at a CAGR of 3.3% through 2035. This segment leads the market due to its essential role in semiconductor manufacturing, where wafers undergo highly complex processes such as lithography, doping, etching, and deposition. Increasing demand for advanced chips used in artificial intelligence, electric mobility, telecommunications, and high-performance computing is driving continuous investment in wafer fab construction.
China Semiconductor Plant Construction Market reached USD 8.4 billion in 2025 and is projected to grow at a CAGR of 4.2% through 2035. Market expansion is strongly supported by national strategies focused on strengthening domestic semiconductor production capabilities and reducing dependence on imported chips. Large-scale investments are being directed toward expanding fabrication infrastructure across both mature and advanced process technologies, driven by demand from consumer electronics, telecommunications, and industrial applications.
Key companies operating in the global semiconductor plant construction market include Bechtel Corporation, Exyte, Fluor Corporation, Jacobs Engineering Group, SK ecoplant, Samsung C&T Corporation, JGC Corporation, DPR Construction, Gilbane Building Company, Mortenson, Hoffman Construction, Kajima Corporation, Obayashi Corporation, Tata Projects Limited, Skanska, PCL Construction, Hensel Phelps, Austin Industries, Sundt Construction, Kiewit Corporation, and McCarthy Building Companies. Market participants are strengthening their competitive positioning through large-scale EPC capabilities and advanced cleanroom construction expertise tailored for semiconductor fabrication environments. Companies are investing in high-precision engineering solutions to support next-generation process nodes and ultra-clean manufacturing requirements. Strategic collaborations with semiconductor manufacturers and technology providers are enabling long-term project pipelines and improved execution efficiency. Firms are also focusing on modular construction techniques and digital project management tools to reduce build times and improve cost efficiency. Expansion into new geographic markets supported by government-backed semiconductor programs is further enhancing growth opportunities.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Construction Type
- 2.2.3 Facility
- 2.2.4 Equipment
- 2.2.5 Project Delivery Model
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid expansion of semiconductor demand from AI, 5G, automotive, and data centers
- 3.2.1.2 Government incentives and strategic national semiconductor programs
- 3.2.1.3 Reshoring and supply chain diversification initiatives
- 3.2.2 Pitfalls & Challenges
- 3.2.2.1 Extremely high capital investment and long construction timelines
- 3.2.2.2 Complex engineering requirements for cleanrooms and precision environments
- 3.2.3 Opportunities
- 3.2.3.1 Expansion of semiconductor manufacturing capacity in Asia Pacific and North America
- 3.2.3.2 Adoption of AI-driven construction planning and digital twin technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Future market trends
- 3.5 Technology and innovation landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Regulatory landscape
- 3.6.1 Standards and compliance requirements
- 3.6.2 Regional regulatory frameworks
- 3.6.3 Certification standards
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Pricing analysis (solution core) (driven by primary research)
- 3.9.1 Historical price trend analysis (driven by primary research)
- 3.9.2 Pricing strategy by project scale (small/medium/large-scale fabs) (driven by primary research)
- 3.10 Impact of AI and generative AI on the market
- 3.10.1 AI-driven disruption of existing construction models
- 3.10.2 GenAI use cases and adoption roadmap
- 3.10.3 Generative design for fab layouts
- 3.10.4 AI-powered scheduling and resource optimization
- 3.10.5 Predictive maintenance for construction equipment
- 3.10.6 Risks, limitations and regulatory considerations
- 3.11 Capacity and production landscape (driven by primary research)
- 3.11.1 Installed global fab capacity by region and technology node (driven by primary research)
- 3.11.2 Capacity utilization rates and expansion pipelines (driven by primary research)
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By Region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.1 By Region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Construction Type, 2022 - 2035, (USD Billion) (Thousand Units)
- 5.1 Key trends
- 5.2 New construction
- 5.3 Expansion
- 5.4 Renovation
Chapter 6 Market Estimates & Forecast, By Facility, 2022 - 2035, (USD Billion) (Thousand Units)
- 6.1 Key trends
- 6.2 Wafer fabrication facilities
- 6.3 Assembly & test facilities
- 6.4 Research & development facilities
Chapter 7 Market Estimates & Forecast, By Equipment, 2022 - 2035, (USD Billion) (Thousand Units)
- 7.1 Key trends
- 7.2 Lithography
- 7.3 Deposition
- 7.4 Etching
- 7.5 Chemical mechanical planarization (CMP)
- 7.6 Cleaning
- 7.7 Others
Chapter 8 Market Estimates & Forecast, By Project Delivery Model, 2022 - 2035, (USD Billion) (Thousand Units)
- 8.1 Key trends
- 8.2 EPC/Turnkey
- 8.3 Design-Build
- 8.4 Construction Management
- 8.5 Joint Venture/Consortium
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035, (USD Billion) (Thousand Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 South Korea
- 9.4.5 Australia
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 Saudi Arabia
- 9.6.2 UAE
- 9.6.3 South Africa
Chapter 10 Company Profiles
- 10.1 Top Global Players
- 10.1.1 Bechtel Corporation
- 10.1.2 Exyte
- 10.1.3 Fluor Corporation
- 10.1.4 Jacobs Engineering Group
- 10.1.5 Samsung C&T Corporation
- 10.1.6 SK ecoplant
- 10.1.7 JGC Corporation
- 10.2 Regional Champions
- 10.2.1 DPR Construction
- 10.2.2 Gilbane Building Company
- 10.2.3 Tata Projects Limited
- 10.2.4 Hoffman Construction
- 10.2.5 Kajima Corporation
- 10.2.6 Obayashi Corporation
- 10.2.7 Mortenson
- 10.3 Emerging & Specialized Players
- 10.3.1 PCL Construction
- 10.3.2 Hensel Phelps
- 10.3.3 Skanska
- 10.3.4 Austin Industries
- 10.3.5 Sundt Construction
- 10.3.6 Kiewit Corporation
- 10.3.7 McCarthy Building Companies

