PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2045786
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2045786
Autonomous Marine Vehicle Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
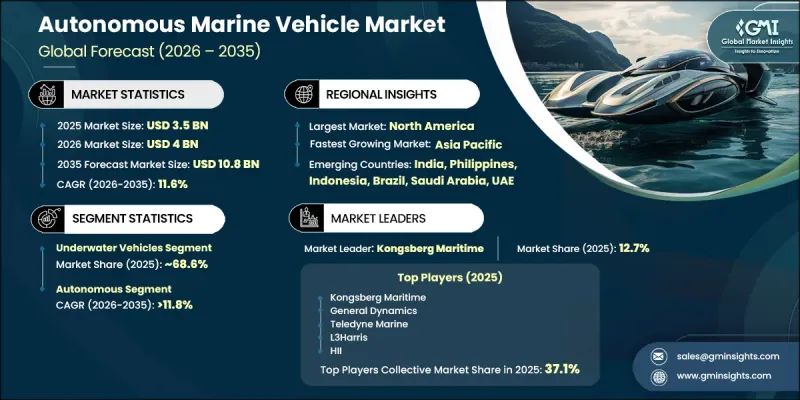
The Global Autonomous Marine Vehicle Market was valued at USD 3.5 billion in 2025 and is estimated to grow at a CAGR of 11.6% to reach USD 10.8 billion by 2035.
The industry is undergoing a rapid technological shift as maritime operations increasingly adopt automation, driven by rising demand for unmanned ocean missions and continuous improvements in artificial intelligence, sensor fusion, and underwater communication systems. Traditional reliance on crewed vessels is steadily declining as the sector transitions toward autonomous and semi-autonomous platforms capable of executing complex tasks with minimal human input. Modern autonomous marine vehicles integrate sonar systems, satellite connectivity, AI-based navigation, LiDAR, advanced imaging payloads, and real-time monitoring capabilities, significantly improving mission efficiency, operational endurance, and situational awareness across commercial, defense, and scientific applications. Expanding focus on offshore infrastructure monitoring, maritime security enhancement, and ocean data collection is accelerating the deployment of autonomous underwater and surface vehicles. Governments, naval forces, and offshore operators are increasingly investing in intelligent marine systems to reduce operational risks, improve surveillance efficiency, and enable extended missions in remote and hazardous marine environments. In addition, advances in collision avoidance and autonomous navigation technologies are improving safety, lowering manpower dependency, and enabling more cost-efficient marine operations. Offshore energy activities, including subsea inspections, pipeline monitoring, offshore wind maintenance, and underwater asset evaluation, are also significantly contributing to rising demand.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.5 Billion |
| Forecast Value | $10.8 Billion |
| CAGR | 11.6% |
The underwater vehicle category held a 68.6% share in 2025 and is projected to grow at a CAGR of 12.1% through 2035. This segment remains dominant due to increasing deployment of autonomous underwater vehicles and remotely operated systems across defense, offshore energy, scientific exploration, and subsea inspection applications. These systems are widely used for mine detection operations, underwater surveillance, seabed mapping, pipeline assessment, hydrographic surveying, and oceanographic data acquisition. Their ability to operate efficiently in deep-sea and high-risk environments with minimal human intervention enhances safety, extends mission duration, and improves data precision, making them indispensable in both military and commercial marine operations.
The fully autonomous segment accounted for 74% share in 2025 and is expected to grow at a CAGR of 11.8% between 2026 and 2035. This dominance is attributed to growing demand for independent marine systems that can function without continuous human control across defense, offshore energy, scientific research, and commercial maritime operations. Autonomous platforms deliver higher operational efficiency, reduced workforce dependency, extended mission capability, and safe performance in remote or hazardous marine zones. Their expanding use in underwater surveillance, mine countermeasure operations, offshore asset inspection, hydrographic mapping, and environmental monitoring continue to drive global adoption.
U.S. Autonomous Marine Vehicle Market held an 83.6% share in 2025 generating USD 1,127.3 million. Rising geopolitical tensions and the growing need for maritime situational awareness are driving increased procurement of unmanned marine systems capable of operating in deep and high-risk waters with minimal human involvement. Market expansion is further supported by rapid advancements in artificial intelligence, sonar imaging, underwater communication systems, and autonomous navigation technologies. Expanding offshore energy development, oceanographic research initiatives, and environmental monitoring programs are also strengthening commercial adoption of autonomous marine vehicles. In addition, the strong presence of defense contractors, marine robotics developers, and government-supported maritime innovation programs continues to enhance technological progress and domestic market growth.
Key companies operating in the Global Autonomous Marine Vehicle Market include Kongsberg Maritime, General Dynamics, Teledyne Marine, L3Harris, HII (REMUS), BAE Systems, Thales, Boeing, Lockheed Martin, and Atlas Elektronik. Companies in the autonomous marine vehicle market are focusing on strengthening their competitive position through continuous investment in artificial intelligence integration, advanced sensor fusion, and high-precision navigation systems. Strategic partnerships with defense agencies, offshore energy operators, and research institutions are enabling faster commercialization and wider deployment of autonomous platforms. Firms are also prioritizing modular and scalable vehicle designs to support diverse mission requirements across commercial and military applications. Expanding research and development in battery efficiency, underwater communication, and long-endurance autonomy is improving operational performance. Additionally, companies are adopting cloud-based data analytics and real-time monitoring systems to enhance mission intelligence.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast Model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product Type
- 2.2.3 Type
- 2.2.4 Sub-system
- 2.2.5 Application
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing Naval Modernization and Maritime Security Investments
- 3.2.1.2 Growing Demand for Oceanographic and Environmental Monitoring
- 3.2.1.3 Expansion of Offshore Energy Infrastructure
- 3.2.1.4 Advancements in AI, Sensor Fusion, and Autonomous Navigation
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Development and Deployment Costs
- 3.2.2.2 Limited Underwater Communication Capability.
- 3.2.3 Market opportunities
- 3.2.3.1 Growing Adoption of Autonomous Fleets for Ocean Mapping
- 3.2.3.2 Expansion in Offshore Wind Farm Inspection Services
- 3.2.3.3 Integration of Swarm Robotics and Collaborative Missions
- 3.2.3.4 Rising Smart Ocean and Digital Maritime Initiatives.
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory guideline
- 3.6.1 North America
- 3.6.1.1 U.S.: U.S. Coast Guard (USCG) Unmanned Maritime Systems Guidelines, Maritime Transportation Security Act (MTSA), NOAA Autonomous
- 3.6.1.2 Canada: Canada Shipping Act, Transport Canada Marine Safety Regulations, Ocean Protection Plan Framework
- 3.6.2 Europe
- 3.6.2.1 Germany: Federal Maritime and Hydrographic Agency (BSH) Maritime Regulations, EU Maritime Safety Agency (EMSA) Autonomous Vessel Framework
- 3.6.2.2 UK: Maritime and Coastguard Agency (MCA) Maritime Autonomy Regulations, UK Marine Safety Code
- 3.6.2.3 France: Code des Transports Maritimes, National Maritime Strategy for Autonomous Navigation
- 3.6.2.4 Italy: Italian Coast Guard Maritime Safety Rules, EU Marine Equipment Directive (MED)
- 3.6.3 Asia Pacific
- 3.6.3.1 China: Maritime Safety Administration (MSA) Smart Shipping Regulations, China Classification Society (CCS) Autonomous Vessel Guidelines
- 3.6.3.2 India: Directorate General of Shipping (DGS) Maritime Regulations, Sagarmala Maritime Modernization Framework
- 3.6.3.3 Japan: Japan Maritime Bureau Autonomous Ship Guidelines, MLIT Smart Navigation Policies
- 3.6.3.4 Australia: Australian Maritime Safety Authority (AMSA) Marine Autonomy Framework, Navigation Act Compliance Standards
- 3.6.4 Latin America
- 3.6.4.1 Brazil: Brazilian Navy Maritime Authority Standards (NORMAM), National Waterway Transportation Policies
- 3.6.4.2 Mexico: Secretariat of the Navy (SEMAR) Maritime Regulations, Federal Marine Navigation Standards
- 3.6.4.3 Argentina: National Naval Prefecture Regulations, Maritime Safety and Navigation Framework
- 3.6.5 MEA
- 3.6.5.1 UAE: UAE Maritime Law, Dubai Maritime City Authority (DMCA) Smart Marine Regulations
- 3.6.5.2 Saudi Arabia: Saudi Ports Authority (MAWANI) Maritime Digitalization Framework, Vision 2030 Maritime Strategy
- 3.6.5.3 South Africa: South African Maritime Safety Authority (SAMSA) Marine Vessel Regulations, National Ports Act
- 3.6.1 North America
- 3.7 PESTEL analysis
- 3.8 Patent Landscape (Driven by Primary Research)
- 3.9 Trade Data Analysis (Based on Paid Database)
- 3.9.1 Import/Export Volume & Value Trends
- 3.9.2 Key Trade Corridors & Tariff Impact
- 3.10 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.10.1 AI-Driven Disruption of Existing Business Models
- 3.10.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10.3 Risks, Limitations & Regulatory Considerations
- 3.11 Capacity & Production Landscape (Driven by Primary Research)
- 3.11.1 Production Capacity by Region & Key Producer
- 3.11.2 Capacity Utilization Rates & Expansion Pipelines
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case - Key Macro & Industry Variables Driving CAGR
- 3.13.2 Optimistic Scenarios - Favourable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company Tier Benchmarking
- 4.6.1 Tier Classification Criteria & Qualifying Thresholds
- 4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5 Market Estimates & Forecast, By Product Type, 2022 - 2035 ($Bn, Units)
- 5.1 Key trends
- 5.2 Surface vehicles
- 5.3 Underwater vehicles
Chapter 6 Market Estimates & Forecast, By Type, 2022 - 2035 ($Bn, Units)
- 6.1 Key trends
- 6.2 Semi-Autonomous
- 6.3 Autonomous
Chapter 7 Market Estimates & Forecast, By Sub-system, 2022 - 2035 ($Bn, Units)
- 7.1 Key trends
- 7.2 Propulsion
- 7.3 Drive system
- 7.4 Collision avoidance
- 7.5 Payloads & imaging
- 7.6 Communication & navigation
Chapter 8 Market Estimates & Forecast, By Application, 2022 - 2035 ($Bn, Units)
- 8.1 Key trends
- 8.2 Military & defence
- 8.3 Oil & gas
- 8.4 Environment monitoring
- 8.5 Oceanography
- 8.6 Archaeology & exploration
- 8.7 Search & salvage operation
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($Bn, Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Russia
- 9.3.7 Netherlands
- 9.3.8 Belgium
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Philippines
- 9.4.7 Indonesia
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Players
- 10.1.1 Kongsberg Maritime
- 10.1.2 Teledyne Marine
- 10.1.3 General Dynamics Mission Systems
- 10.1.4 L3Harris Technologies
- 10.1.5 Boeing
- 10.1.6 Saab Seaeye
- 10.1.7 BAE Systems
- 10.1.8 Thales
- 10.1.9 Oceanalpha
- 10.1.10 Exail
- 10.2 Regional Players
- 10.2.1 Huntington Ingalls
- 10.2.2 Lockheed Martin
- 10.2.3 ST Engineering
- 10.2.4 Maritime Robotics
- 10.2.5 Textron Systems
- 10.2.6 Elbit Systems
- 10.2.7 Atlas Elektronik
- 10.2.8 ISE
- 10.2.9 Subsea Tech
- 10.2.10 Yunzhou Tech
- 10.3 Emerging Players
- 10.3.1 Ocean Infinity
- 10.3.2 Sea Machines Robotics
- 10.3.3 Cellula Robotics
- 10.3.4 AutoNaut
- 10.3.5 Seabed BV

