PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2071386
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2071386
Firearms Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
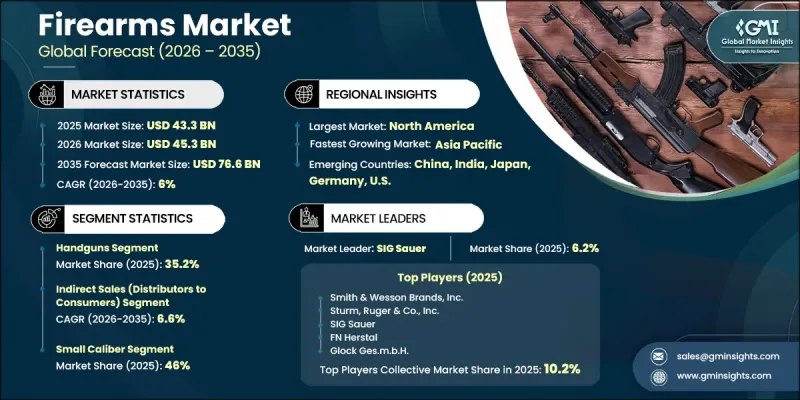
The Global Firearms Market was valued at USD 43.3 billion in 2025 and is estimated to grow at a CAGR of 6% to reach USD 76.6 billion by 2035.
Market growth is driven by rising defense modernization initiatives, increasing demand for personal protection, ongoing advancements in weapon technologies, and the expanding role of law enforcement agencies. Firearms continue to serve critical roles across military, civilian, security, and sporting applications, supporting both tactical and recreational needs. The market is further supported by escalating geopolitical tensions and increased defense investments by governments focused on strengthening national security capabilities. Demand for advanced firearms is rising as defense agencies prioritize operational precision, combat readiness, and modernization of armed forces. Civilian demand is also expanding due to heightened concerns around personal safety, crime rates, and self-defense, where legally permitted ownership of handguns, pistols, and sporting rifles is increasing. Technological advancements in firearm design, including lightweight structures and ergonomic improvements, are enhancing usability, safety, and performance for both professional and civilian users.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $43.3 Billion |
| Forecast Value | $76.6 Billion |
| CAGR | 6% |
The rifles segment is expected to grow at a CAGR of 7.2% throughout 2035, driven by rising defense procurement programs, modernization of military arsenals, and increasing participation in recreational shooting and hunting activities. Armed forces and law enforcement agencies are increasingly adopting advanced tactical rifles, supporting segment expansion. Continuous innovation in modular rifle systems, precision targeting technologies, and lightweight materials is improving operational efficiency and driving broader adoption across defense and civilian applications.
The indirect sales channel accounted for 60.5% share in 2025 and is projected to grow at a CAGR of 6.6% through 2035. This channel remains dominant due to the wide accessibility offered by licensed dealers, distributors, and retail firearm networks, which serve military, law enforcement, and civilian buyers. These channels also support compliance with regulatory frameworks while expanding product availability and after-sales support. The increasing presence of structured firearm retail ecosystems continues to strengthen market reach and consumer access across regions.
North America Firearms Market held a 33.9% share in 2025. Regional growth is supported by strong defense modernization programs, widespread civilian firearm ownership, and active law enforcement procurement. The region benefits from advanced defense infrastructure, high military spending, and rapid adoption of modern firearm technologies. Demand is further reinforced by homeland security requirements, recreational shooting activities, and continuous upgrades in tactical weapon systems.
Major players operating in the firearms industry include SIG Sauer, Sturm, Ruger & Co., Inc., Smith & Wesson Brands, Inc., Glock Ges.m.b.H., FN Herstal, Heckler & Koch, Beretta Holding S.A., Colt CZ Group SE, Colt's Manufacturing Company LLC, Taurus Armas S.A., Norinco (China North Industries Corporation), Kalashnikov Concern, IWI (Israel Weapon Industries), Howa Machinery Ltd., Daniel Defense, Inc., Kel-Tec CNC Industries, Inc., Savage Arms, Inc., Canik (Samsun Yurt Savunma), and Caracal International LLC. Companies in the firearms market are focusing on continuous product innovation, emphasizing improved ergonomics, modular designs, and enhanced precision systems to meet evolving user requirements. Manufacturers are investing heavily in advanced materials and manufacturing technologies to improve durability, weight reduction, and performance. Strategic partnerships with defense agencies and law enforcement bodies are supporting long-term procurement contracts. Firms are also expanding distribution networks through licensed retail and authorized dealer channels to improve market reach.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Caliber trends
- 2.2.2 Type trends
- 2.2.3 Distribution trends
- 2.2.4 End-user industry trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising defense modernization and military procurement programs
- 3.2.1.2 Growing demand for civilian firearms for personal safety and self-defense
- 3.2.1.3 Expansion of law enforcement and homeland security activities
- 3.2.1.4 Technological advancements in smart and lightweight firearm systems
- 3.2.1.5 Rising popularity of recreational shooting and hunting activities
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Strict government regulations and firearm control policies
- 3.2.2.2 Growing concerns regarding firearm-related violence and misuse
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing adoption of advanced firearms by defense and law enforcement agencies
- 3.2.3.2 Expansion of shooting sports and firearm training infrastructure
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Type, 2022 - 2035 (USD Billion)
- 5.1 Key trends
- 5.2 Handguns
- 5.2.1 Pistols
- 5.2.2 Revolvers
- 5.3 Rifles
- 5.3.1 Semi-Automatic Rifles
- 5.3.2 Bolt-Action Rifles
- 5.3.3 Assault Rifles
- 5.3.4 Sniper Rifles
- 5.4 Shotguns
- 5.4.1 Pump-Action Shotguns
- 5.4.2 Semi-Automatic Shotguns
- 5.4.3 Double-Barrel Shotguns
- 5.4.4 Single-Shot Shotguns
- 5.5 Machine Guns
- 5.6 Submachine Guns
- 5.7 Others
Chapter 6 Market Estimates and Forecast, By Caliber, 2022 - 2035 (USD Billion)
- 6.1 Key trends
- 6.2 Small Caliber
- 6.3 Medium Caliber
- 6.4 Large Caliber
- 6.5 Shotgun Gauges
Chapter 7 Market Estimates and Forecast, By Distribution Channel, 2022 - 2035 (USD Billion)
- 7.1 Key trends
- 7.2 Direct Sales (Manufacturer to Consumer)
- 7.3 Indirect Sales (Distributors to Consumers)
- 7.4 Online
- 7.5 Offline
Chapter 8 Market Estimates and Forecast, By End-User Industry, 2022 - 2035 (USD Billion)
- 8.1 Key trends
- 8.2 Military & Defense Forces
- 8.3 Law Enforcement Agencies
- 8.4 Civilians
- 8.5 Private Security Firms
- 8.6 Shooting Ranges and Clubs
- 8.7 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Billion)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 SIG Sauer
- 10.1.2 Smith & Wesson Brands, Inc.
- 10.1.3 Sturm, Ruger & Co., Inc.
- 10.1.4 FN Herstal
- 10.1.5 Glock Ges.m.b.H.
- 10.1.6 Beretta Holding S.A.
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Colt CZ Group SE
- 10.2.1.2 Taurus Armas S.A.
- 10.2.1.3 Savage Arms, Inc.
- 10.2.1.4 Daniel Defense, Inc.
- 10.2.1.5 Heckler & Koch
- 10.2.2 Asia Pacific
- 10.2.2.1 Norinco (China North Industries Corporation)
- 10.2.2.2 Howa Machinery Ltd.
- 10.2.2.3 Canik (Samsun Yurt Savunma) Ltd.
- 10.2.3 Europe
- 10.2.3.1 Kalashnikov Concern
- 10.2.3.2 IWI (Israel Weapon Industries)
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Kel-Tec CNC Industries, Inc.
- 10.3.2 Caracal International LLC

