PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2101676
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2101676
Automotive Torque Actuator Motor Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
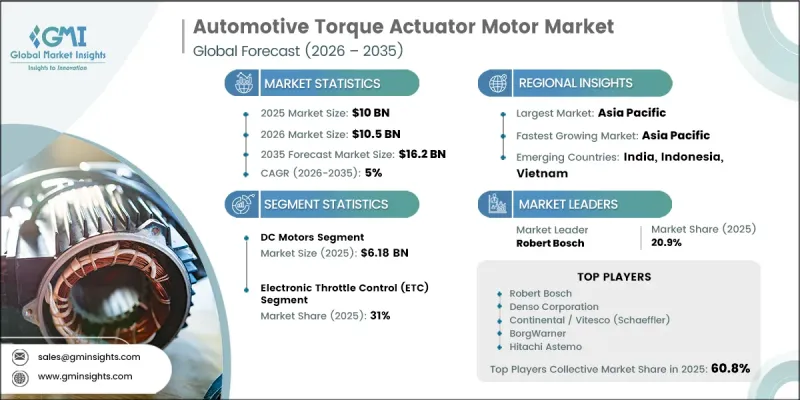
The Global Automotive Torque Actuator Motor Market was valued at USD 10 billion in 2025 and is estimated to grow at a CAGR of 5% to reach USD 16.2 billion by 2035.
The automotive torque actuator motor market continues to expand as vehicle manufacturers accelerate the transition toward electronically controlled vehicle systems across conventional, hybrid, and battery electric vehicle platforms. The increasing integration of advanced electronic architectures is driving demand for precision actuator motors that support improved vehicle efficiency, enhanced safety, and greater system responsiveness. Battery electric vehicles generally require a higher number of actuator motors than internal combustion engine vehicles, creating additional growth opportunities as electric mobility adoption continues to rise globally. Regulatory initiatives encouraging cleaner transportation and improved vehicle performance are further supporting the implementation of electronically controlled automotive systems. The ongoing replacement of mechanical and hydraulic components with electrically operated alternatives is reshaping vehicle design while enabling greater software integration, improved packaging flexibility, and enhanced automation capabilities. In addition, manufacturers are increasingly incorporating intelligent actuator technologies equipped with integrated sensing, diagnostic functions, and electronic control capabilities, strengthening the long-term growth outlook for the automotive torque actuator motor market as the automotive industry advances toward more connected and technologically sophisticated vehicles.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $10 Billion |
| Forecast Value | $16.2 Billion |
| CAGR | 5% |
The DC motor segment accounted for 62% share, generating USD 6.18 billion in 2025. The segment is projected to reach USD 9.31 billion by 2035, growing at a CAGR of 4.2%. Its leading position is supported by the extensive use of permanent magnet DC motors across high-volume automotive applications where manufacturers continue to prioritize proven performance, cost efficiency, and long-term operational reliability. Their widespread adoption across vehicle production programs reinforces the segment's dominant contribution to overall market revenue.
The electronic throttle control (ETC) segment held 31% share in 2025. The broad implementation of electronic throttle control across internal combustion engine, hybrid electric, and plug-in hybrid vehicle platforms continues to support consistent demand. However, future growth remains comparatively moderate due to the absence of throttle control systems in fully battery electric vehicle architectures and the already high penetration of ETC technologies across established automotive markets.
Asia Pacific Automotive Torque Actuator Motor Market held 61% share, generating USD 6.09 billion in 2025, supported by its large-scale automotive manufacturing industry, expanding production of electrified vehicles, and favorable regulatory initiatives that continue to encourage the adoption of advanced vehicle technologies.
Major companies operating in the global automotive torque actuator motor market include Denso Corporation, Robert Bosch GmbH, BorgWarner Inc., Johnson Electric Holdings, Valeo SE, Continental/Vitesco (Schaeffler), and Hitachi Astemo (Astemo Ltd.). Companies operating in the automotive torque actuator motor market are strengthening their competitive position by investing in advanced motor technologies, expanding manufacturing capabilities, and developing high-performance actuator solutions that meet evolving vehicle requirements. Manufacturers are increasing research and development efforts to improve motor efficiency, durability, precision, and integration with advanced electronic vehicle systems. Strategic collaborations with automotive manufacturers and Tier-1 suppliers continue to support long-term supply agreements and accelerate product development. Companies are also expanding their global manufacturing footprint and optimizing supply chains to improve production flexibility and meet rising regional demand.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Motor Type
- 2.2.2 Powertrain
- 2.2.3 Vehicle Type
- 2.2.4 Sales Channel
- 2.2.5 Application
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Cost structure
- 3.1.3 Profit margin
- 3.1.4 Value addition at each stage
- 3.1.5 Vertical integration trends
- 3.1.6 Disruptors
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing Vehicle Electrification
- 3.2.1.2 Stringent Emission and Fuel Efficiency Regulations
- 3.2.1.3 Rising Adoption of Drive-by-Wire Technologies
- 3.2.1.4 Increasing Integration of Smart Actuation Systems
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 Declining Engine Actuator Demand in BEVs
- 3.2.2.2 High Reliability and Functional Safety Requirements
- 3.2.2.3 Cost Pressure Across the Supply Chain
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of Thermal Management Systems in EVs
- 3.2.3.2 Growth in Software-Defined Vehicles
- 3.2.3.3 Increasing Adoption of Active Aerodynamics
- 3.2.3.4 Vehicle Electrification and Platform Modernization
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technologies
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 FMVSS (US)
- 3.6.1.2 EPA Tier 3 Emission Standards (US)
- 3.6.1.3 CARB LEV III Regulations (US)
- 3.6.1.4 SAE J1939 Standards (US)
- 3.6.2 Europe
- 3.6.2.1 Euro 7 Emission Regulation
- 3.6.2.2 UNECE R10 (EMC)
- 3.6.2.3 UNECE R155 (Cybersecurity)
- 3.6.2.4 RoHS & REACH
- 3.6.3 Asia-Pacific
- 3.6.3.1 China VI Emission Standards (China)
- 3.6.3.2 GB/T Automotive Standards (China)
- 3.6.3.3 Japan Road Vehicle Safety Standards (Japan)
- 3.6.3.4 BS VI Emission Standards (India)
- 3.6.3.5 Australian Design Rules (ADR)
- 3.6.4 Latin America
- 3.6.4.1 PROCONVE L7/L8 (Brazil)
- 3.6.4.2 NOM Vehicle Standards (Mexico)
- 3.6.5 Middle East & Africa
- 3.6.5.1 UAE Vehicle Safety Regulations
- 3.6.5.2 SASO Vehicle Standards (Saudi Arabia)
- 3.6.5.3 SANS Vehicle Standards (South Africa)
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by Primary Research)
- 3.10 Trade Data Analysis (Driven by paid database)
- 3.10.1 Import/export volume & value trends
- 3.10.2 Key trade corridors & tariff impact
- 3.11 Cost breakdown analysis
- 3.12 Capacity & Production Landscape (Driven by Primary Research)
- 3.12.1 Installed Capacity by Region & Key Producer
- 3.12.2 Capacity Utilization Rates & Expansion Pipelines
- 3.13 Impact of AI & generative AI on the market
- 3.13.1 AI Driven Disruption of Existing Business Models
- 3.13.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.13.3 Risks Limitations and Regulatory Considerations
- 3.14 Sustainability and environmental aspects
- 3.14.1 Sustainable practices
- 3.14.2 Waste reduction strategies
- 3.14.3 Energy efficiency in production
- 3.14.4 Eco-friendly Initiatives
- 3.14.5 Carbon footprint considerations
- 3.15 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.15.1 Base Case key macro & industry variables driving CAGR
- 3.15.2 Optimistic Scenarios Favorable Macro and Industry Tailwinds
- 3.15.3 Pessimistic Scenario Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia-Pacific
- 4.2.4 Latin America
- 4.2.5 Middle East & Africa
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Motor Type, 2022 - 2035 ($Mn, Units)
- 5.1 Key trends
- 5.2 DC Motor
- 5.3 Stepper Motor
- 5.4 Servo Motor
- 5.5 Others
Chapter 6 Market Estimates & Forecast, By Powertrain, 2022 - 2035 ($Mn, Units)
- 6.1 Key trends
- 6.2 Internal Combustion Engine (ICE)
- 6.3 Hybrid Electric Vehicle (HEV) / Plug-in Hybrid Electric Vehicle (PHEV)
- 6.4 Battery Electric Vehicle (BEV)
- 6.5 Fuel Cell Electric Vehicle (FCEV)
Chapter 7 Market Estimates & Forecast, By Vehicle Type, 2022 - 2035 ($Mn, Units)
- 7.1 Key trends
- 7.2 Passenger Vehicles
- 7.2.1 Hatchback
- 7.2.2 Sedan
- 7.2.3 SUV
- 7.3 Commercial Vehicles
- 7.3.1 Light Commercial Vehicle (LCV)
- 7.3.2 Medium Commercial Vehicle (MCV)
- 7.3.3 Heavy Commercial Vehicle (HCV)
Chapter 8 Market Estimates & Forecast, By Sales Channel, 2022 - 2035 ($Mn, Units)
- 8.1 Key trends
- 8.2 Original Equipment Manufacturer (OEM)
- 8.3 Aftermarket
Chapter 9 Market Estimates & Forecast, By Application, 2022 - 2035 ($Mn, Units)
- 9.1 Key trends
- 9.2 Electronic Throttle Control (ETC)
- 9.3 Turbocharger Actuation
- 9.4 Exhaust Gas Recirculation (EGR)
- 9.5 Variable Valve Timing (VVT)
- 9.6 Intake Manifold Runner Control (IMRC)
- 9.7 Transmission Actuation
- 9.8 Active Grille Shutter (AGS)
- 9.9 HVAC Blend Door Actuation
- 9.10 Others
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 10.1 North America
- 10.1.1 US
- 10.1.2 Canada
- 10.2 Europe
- 10.2.1 UK
- 10.2.2 Germany
- 10.2.3 France
- 10.2.4 Italy
- 10.2.5 Spain
- 10.2.6 Belgium
- 10.2.7 Netherlands
- 10.2.8 Sweden
- 10.2.9 Russia
- 10.3 Asia Pacific
- 10.3.1 China
- 10.3.2 India
- 10.3.3 Japan
- 10.3.4 Australia
- 10.3.5 Singapore
- 10.3.6 South Korea
- 10.3.7 Vietnam
- 10.3.8 Indonesia
- 10.3.9 Thailand
- 10.4 Latin America
- 10.4.1 Brazil
- 10.4.2 Mexico
- 10.4.3 Argentina
- 10.5 MEA
- 10.5.1 South Africa
- 10.5.2 Saudi Arabia
- 10.5.3 UAE
- 10.5.4 Turkey
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 Aptiv
- 11.1.2 BorgWarner
- 11.1.3 Continental
- 11.1.4 Denso
- 11.1.5 Hitachi Astemo
- 11.1.6 Johnson Electric Holdings
- 11.1.7 Marelli
- 11.1.8 Mitsubishi Electric
- 11.1.9 Nidec
- 11.1.10 Robert Bosch
- 11.1.11 Valeo
- 11.1.12 Vitesco Technologies
- 11.1.13 ZF Friedrichshafen
- 11.2 Regional Players
- 11.2.1 HELLA
- 11.2.2 Aisan Industry
- 11.2.3 Mabuchi Motor
- 11.2.4 Mikuni
- 11.3 Emerging Players / Disruptors
- 11.3.1 Inzi Controls
- 11.3.2 Ningbo Tuopu
- 11.3.3 Shinano Kenshi

