PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109214
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109214
Display Module Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
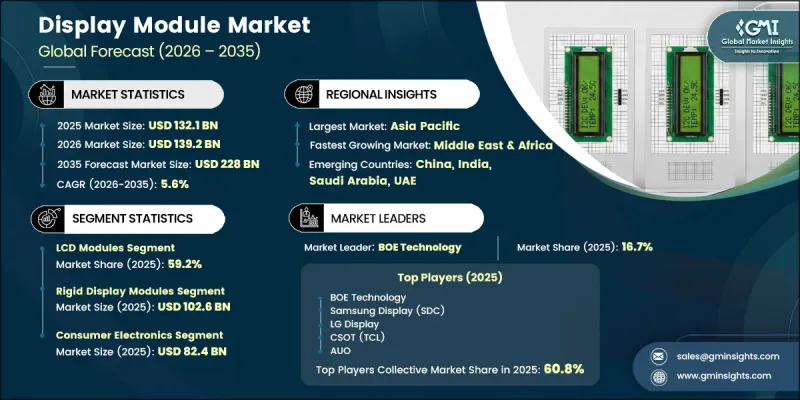
The Global Display Module Market was valued at USD 132.1 billion in 2025 and is estimated to grow at a CAGR of 5.6% to reach USD 228 billion by 2035.
Market growth is supported by the increasing adoption of advanced display technologies, expanding integration of digital displays in modern vehicles, and rising demand for high-quality visual interfaces across consumer electronics and computing devices. The rapid proliferation of artificial intelligence-enabled products is further accelerating the need for display modules that deliver enhanced image quality, energy efficiency, and improved user experiences. In addition, government investments aimed at strengthening domestic display and semiconductor manufacturing capabilities continue to create favorable conditions for industry expansion. Growing emphasis on sustainable electronics and energy-efficient product design is also encouraging manufacturers to develop display modules with greater durability, longer operational life, improved repairability, and lower power consumption. These trends are reshaping product development priorities while supporting broader adoption across commercial, industrial, automotive, healthcare, and consumer applications. As manufacturers continue investing in next-generation display technologies and production capabilities, the display module market is expected to witness sustained demand driven by continuous innovation and expanding digital transformation across multiple industries.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $132.1 Billion |
| Forecast Value | $228 Billion |
| CAGR | 5.6% |
Government support continues to play an important role in advancing the display module market by encouraging domestic manufacturing and strengthening local production capabilities for display technologies. Public investments are helping expand manufacturing infrastructure while reducing dependence on external supply chains. At the same time, increasingly stringent environmental regulations are driving manufacturers to develop more energy-efficient and environmentally responsible display modules. Compliance with evolving sustainability standards is encouraging improvements in product efficiency, operational lifespan, maintenance capabilities, and overall environmental performance, creating additional opportunities for market growth.
The LCD modules segment accounted for 59.2% share in 2025, making it the leading product category. The segment continues to maintain its strong position due to cost competitiveness, a well-established manufacturing ecosystem, and widespread adoption across a broad range of electronic products. Ongoing improvements in display quality, resolution, and production technologies continue to support demand, while consistent adoption in mid-range electronic devices further reinforces the segment's market leadership.
The rigid display modules segment generated USD 102.6 billion in 2025. Broad deployment across commercial, industrial, automotive, healthcare, and consumer electronics applications continues to support segment growth. High durability, reliable performance, cost efficiency, and a mature manufacturing ecosystem make rigid display modules a preferred solution for high-volume production across numerous end-use industries.
North America Display Module Market accounted for 22% share in 2025. Regional growth is supported by increasing investments in semiconductor manufacturing, expanding adoption of AI-enabled electronic devices, and rising demand for advanced display technologies across automotive, healthcare, commercial, and consumer sectors. Government initiatives promoting domestic electronics manufacturing continue to strengthen regional supply chains, while ongoing investments in next-generation display technologies are creating new opportunities for manufacturers serving a wide range of industrial and commercial applications.
Major companies operating in the global display module market include AU Optronics Corp. (AUO), BOE Technology Group Co., Ltd., CSOT (China Star Optoelectronics Technology), Emerging Display Technologies Corp. (EDT), Evervision Electronics, Innolux Corporation, Japan Display Inc. (JDI), Kyocera Corporation, LG Display Co., Ltd., Microtips Technology, Newhaven Display International, Raystar Optronics, Royole Corporation, Samsung Display Co., Ltd., Sharp Corporation (Foxconn Group), Tianma Microelectronics Co., Ltd., Truly International Holdings Ltd., Visionox Technology Inc., and WiseChip Semiconductor Inc. Companies operating in the display module market are focusing on product innovation, manufacturing expansion, and continuous technology development to strengthen their competitive position. Leading manufacturers invest extensively in research and development to improve display performance, energy efficiency, durability, and image quality while addressing evolving customer requirements. Strategic partnerships with electronics manufacturers, automotive companies, and industrial equipment providers help expand market reach and accelerate product adoption. Businesses also prioritize capacity expansion, supply chain optimization, and automation to improve production efficiency and meet growing global demand.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Display technology trends
- 2.2.2 Physical construction trends
- 2.2.3 Touch interface trends
- 2.2.4 Application trends
- 2.2.5 Display size trends
- 2.2.6 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising adoption of OLED and advanced display technologies
- 3.2.1.2 Growing deployment of automotive digital cockpit displays
- 3.2.1.3 Government support for semiconductor and display manufacturing
- 3.2.1.4 Expansion of AI-enabled PCs and premium consumer electronics
- 3.2.1.5 Increasing focus on energy-efficient and sustainable displays
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High manufacturing cost of advanced display technologies
- 3.2.2.2 Supply chain dependency for semiconductor and display components
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of automotive smart cockpit and autonomous vehicle displays
- 3.2.3.2 Growing investments in AI-enabled and energy-efficient display technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Display Technology, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 LCD Modules
- 5.3 OLED Modules
- 5.4 Micro-LED Modules
- 5.5 E-Paper / E-Ink Modules
- 5.6 Others
Chapter 6 Market Estimates and Forecast, By Physical Construction, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Rigid Display Modules
- 6.3 Flexible / Foldable Display Modules
- 6.4 Transparent Display Modules
Chapter 7 Market Estimates and Forecast, By Touch Interface, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Touch-Enabled Display Modules
- 7.3 Non-Touch Display Modules
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Consumer Electronics
- 8.3 Automotive
- 8.4 Industrial & Manufacturing
- 8.5 Healthcare & Medical
- 8.6 Retail & Digital Signage
- 8.7 Aerospace & Defense
- 8.8 Others
Chapter 9 Market Estimates and Forecast, By Display Size, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 Microdisplays (< 1 inch)
- 9.3 Small Displays (1-9 inches)
- 9.4 Medium Displays (9-32 inches)
- 9.5 Large Displays (> 32 inches)
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Russia
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.4.6 Taiwan
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 BOE Technology
- 11.1.2 Samsung Display (SDC)
- 11.1.3 LG Display
- 11.1.4 CSOT (TCL)
- 11.1.5 AUO
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Newhaven Display International
- 11.2.2 Asia Pacific
- 11.2.2.1 Japan Display Inc. (JDI)
- 11.2.2.2 Kyocera Corporation
- 11.2.2.3 Truly International Holdings Ltd.
- 11.2.2.4 Visionox Technology Inc.
- 11.2.2.5 Royole Corporation
- 11.2.2.6 WiseChip Semiconductor Inc.
- 11.2.2.7 Raystar Optronics
- 11.2.2.8 Evervision Electronics
- 11.2.2.9 Innolux Corporation
- 11.2.2.10 Tianma Microelectronics Co., Ltd.
- 11.2.2.11 Sharp Corporation (Foxconn Group)
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 Emerging Display Technologies Corp. (EDT)
- 11.3.2 Microtips Technology

