PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109224
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109224
Airborne Early Warning and Control (AEWandC) System Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
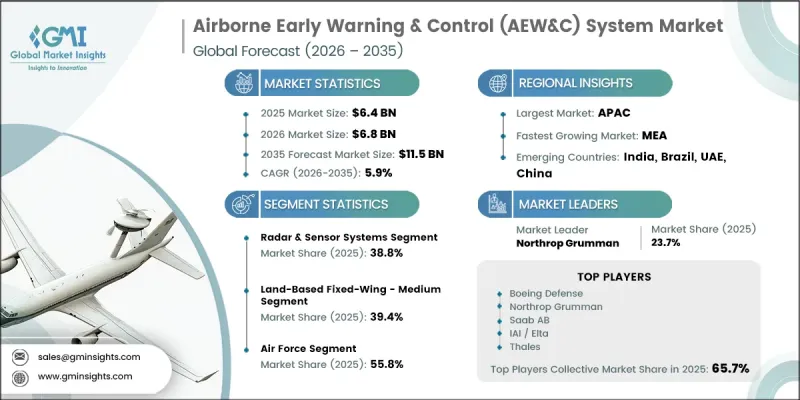
The Global Airborne Early Warning & Control (AEW&C) System Market was valued at USD 6.4 billion in 2025 and estimated to grow at a CAGR of 5.9% to reach USD 11.5 billion by 2035.
Market growth is driven by rising geopolitical uncertainties, increasing global defense spending, and continuous modernization of airborne surveillance capabilities across defense organizations. The replacement of aging airborne surveillance fleets, combined with the growing need to strengthen airspace monitoring and operational readiness, continues to support long-term procurement activities. Expanding defense modernization initiatives and increasing investments in advanced surveillance technologies are also creating favorable growth opportunities. In addition, the rising complexity of modern aerial threats and the growing emphasis on integrated, network-centric military operations are encouraging defense agencies to invest in next-generation airborne command and surveillance systems. Increasing efforts to strengthen domestic defense manufacturing capabilities across several regions are further supporting market expansion. The airborne early warning & control (AEW&C) system market is also benefiting from continuous advancements in avionics, surveillance technologies, mission systems, and digital communications that enhance operational efficiency, improve situational awareness, and support more effective defense coordination across increasingly complex operational environments.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.4 Billion |
| Forecast Value | $11.5 Million |
| CAGR | 5.9% |
Growing defense budgets continue to provide long-term support for the airborne early warning & control (AEW&C) system market, enabling governments to invest in advanced airborne surveillance platforms and modern defense capabilities. The ongoing retirement of aging aircraft and the need to maintain operational readiness are creating consistent replacement opportunities that remain relatively unaffected by short-term budget fluctuations. At the same time, advancements in airborne surveillance technologies and evolving mission requirements are encouraging the development of more flexible and efficient platform configurations, supporting continuous innovation and expanding procurement opportunities across global defense markets.
The radar and sensor systems segment accounted for 38.8% share in 2025. This leadership is supported by the essential role of radar and sensor technologies in aircraft detection, surveillance, tracking, and mission effectiveness. These systems represent a significant portion of overall program investment due to their technical complexity and performance requirements. Increasing demand for enhanced detection capabilities, improved tracking accuracy, and stronger surveillance performance continues to support sustained investments in advanced radar and sensor technologies for both new aircraft and modernization programs.
The land-based fixed-wing - medium segment held 39.4% share in 2025. The segment continues to lead the market by offering an effective balance of operational range, surveillance capability, payload capacity, and overall operating costs. Medium-sized fixed-wing platforms provide greater deployment flexibility, improved maintenance efficiency, and strong mission performance, making them an attractive solution for national defense organizations seeking cost-effective airborne surveillance capabilities. Their adaptability to a wide range of operational requirements continues to support growing adoption across multiple regions.
North America Airborne Early Warning & Control (AEW&C) System Market accounted for 29.5% share in 2025. Regional growth is supported by sustained investments in defense modernization, continued procurement of advanced airborne surveillance platforms, and long-term military capability enhancement programs. Ongoing efforts to improve operational readiness, strengthen airspace surveillance, and expand integrated defense capabilities continue to create stable demand for advanced AEW&C systems. Long-term defense planning and consistent investments in strategic surveillance technologies are expected to support continued market growth throughout the forecast period.
Major companies operating in the global airborne early warning & control (AEW&C) system market include Airbus Defence & Space, Boeing Defense, Space & Security, Elbit Systems, Embraer Defence & Security, General Atomics Aeronautical Systems, Hindustan Aeronautics Limited (HAL), Indra Sistemas, Israel Aerospace Industries (IAI) / Elta Systems, L3Harris Technologies, Leonardo S.p.A., Northrop Grumman Corporation, Raytheon Intelligence & Space (RTX), Saab AB, Thales Group, Turkish Aerospace Industries (TAI/TUSAS), and Viasat Inc. Companies operating in the airborne early warning & control (AEW&C) system market are focusing on continuous technology innovation, platform modernization, and strategic partnerships to strengthen their competitive position. Leading manufacturers are investing in research and development to enhance surveillance capabilities, mission systems, digital communications, and operational efficiency while meeting evolving defense requirements. Businesses are expanding collaboration with defense agencies, aircraft manufacturers, and technology providers to accelerate product development and improve program execution. Companies also prioritize long-term maintenance, upgrade, and lifecycle support services to strengthen customer relationships and generate recurring revenue.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Component trends
- 2.2.2 Platform Type trends
- 2.2.3 Application trends
- 2.2.4 End-user trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Escalating Geopolitical Tensions and Rising Defense Budgets Worldwide
- 3.2.1.2 Modernization and Replacement of Aging AEW&C Fleets
- 3.2.1.3 Increasing Threat from Drones, Cruise Missiles, and Low-Observable Aircraft
- 3.2.1.4 Growing Demand for Network-Centric, Interoperable Coalition Operations
- 3.2.1.5 Expansion of Indigenous Defense Manufacturing in Asia-Pacific (India, China, South Korea, Japan)
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Procurement, Development, and Maintenance Costs
- 3.2.2.2 Aging Fleets with Long Delivery Timelines and Rising Sustainment Costs
- 3.2.3 Market opportunities
- 3.2.3.1 Rise of Missionized Business Jets as Cost-Effective AEW&C Platforms
- 3.2.3.2 Integration of AI and Manned-Unmanned Teaming Technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research)
- 3.4.1 Historical Price Trend Analysis
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.2 Europe
- 3.5.3 Asia Pacific
- 3.5.4 Latin America
- 3.5.5 Middle East & Africa
- 3.6 Porter’s analysis
- 3.7 PESTEL analysis
- 3.8 Trade Data Analysis (Based on Paid Database)
- 3.8.1 Import/Export Volume & Value Trends
- 3.8.2 Key Trade Corridors & Tariff Impact
- 3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.9.1 AI-Driven Disruption of Existing Business Models
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Production Capacity by Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Company market share analysis, 2025
- 4.1.1 By Region
- 4.1.1.1 North America
- 4.1.1.2 Europe
- 4.1.1.3 Asia-Pacific
- 4.1.1.4 Latin America
- 4.1.1.5 Middle East and Africa
- 4.1.2 Market Concentration Analysis
- 4.1.1 By Region
- 4.2 Competitive analysis of major market players
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Component, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Radar & Sensor Systems
- 5.3 Mission Systems & Software
- 5.4 Communication & Data Link Systems
- 5.5 Electronic Support Measures (ESM)
- 5.6 Identification Friend or Foe (IFF)
Chapter 6 Market Estimates and Forecast, By Platform Type, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Land-Based Fixed-Wing - Large (Transport-Class)
- 6.3 Land-Based Fixed-Wing - Medium
- 6.4 Land-Based Fixed-Wing - Light
- 6.5 Carrier-Based Fixed-Wing
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Air Defense & Threat Detection
- 7.3 Command, Control & Battle Management (C2/BM)
- 7.4 Maritime Domain Awareness
- 7.5 Border & Homeland Security
Chapter 8 Market Estimates and Forecast, By End-User, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Air Force
- 8.3 Navy
- 8.4 Joint & Allied Defense Commands
- 8.5 Homeland Security & Border Agencies
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Boeing Defense, Space & Security
- 10.1.2 Northrop Grumman Corporation
- 10.1.3 Thales Group
- 10.1.4 Airbus Defence & Space
- 10.1.5 Raytheon Intelligence & Space (RTX)
- 10.1.6 Israel Aerospace Industries (IAI) / Elta Systems
- 10.1.7 Elbit Systems
- 10.1.8 Embraer Defence & Security
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 L3Harris Technologies
- 10.2.2 Asia Pacific
- 10.2.2.1 Hindustan Aeronautics Limited (HAL)
- 10.2.3 Europe
- 10.2.3.1 Saab AB
- 10.2.3.2 Leonardo S.p.A.
- 10.2.3.3 Indra Sistemas
- 10.2.3.4 Turkish Aerospace Industries (TAI/TUSAS)
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 General Atomics Aeronautical Systems
- 10.3.2 Viasat Inc.

