PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109308

PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109308
Confectionery Ingredients Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
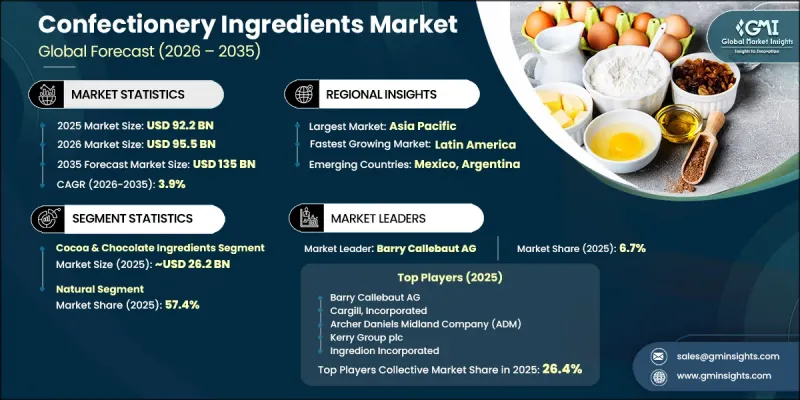
The Global Confectionery Ingredients Market was valued at USD 92.2 billion in 2025 and is estimated to grow at a CAGR of 3.9% to reach USD 135 billion by 2035.
Rising consumer preference for premium, artisanal, and high-quality confectionery products is driving steady demand for advanced ingredient solutions across global markets. Manufacturers are increasingly utilizing premium raw materials, naturally derived ingredients, and specialty formulations to enhance product quality and meet evolving consumer expectations. One of the most significant structural shifts influencing the confectionery ingredients market is the growing replacement of artificial colors, flavors, emulsifiers, and sweeteners with naturally sourced alternatives. This transition is reshaping product development strategies and encouraging ingredient innovation across the industry. At the same time, digital technologies powered by artificial intelligence and machine learning are transforming ingredient formulation by accelerating product development, improving formulation precision, and enhancing sensory optimization. These advanced development platforms enable manufacturers to evaluate ingredient combinations more efficiently, significantly reducing development timelines while improving product consistency. As demand for clean-label products, premium ingredients, and innovative confectionery formulations continues to increase, the confectionery ingredients market is expected to maintain stable growth throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $92.2 Billion |
| Forecast Value | $135 Billion |
| CAGR | 3.9% |
The cocoa and chocolate ingredients segment accounted for a 28.4% share in 2025, generating USD 26.2 billion, and is expected to grow at a CAGR of 3.8% through 2035. The segment continues to dominate due to consistent demand for cocoa-based ingredients across both industrial-scale and artisanal confectionery production. Sweeteners remain the second-largest ingredient category, with manufacturers increasingly incorporating alternative sweetening solutions to support product reformulation initiatives. Milk and dairy ingredients also remain essential for premium confectionery applications, where high-quality raw materials continue to play a critical role in product differentiation.
The natural ingredients segment held a 57.4% share in 2025. Demand for naturally sourced ingredients continues to accelerate as manufacturers respond to consumer preferences for clean-label products, sustainability objectives, and evolving regulatory expectations. This industry-wide transition is driving greater adoption of minimally processed, fermentation-derived, and naturally sourced ingredients. Plant-based emulsifiers, natural color solutions, and botanical sweeteners are increasingly replacing synthetic alternatives, reinforcing the long-term shift toward more natural ingredient formulations.
North America Confectionery Ingredients Market accounted for 21.5% share in 2025. Market growth across the region is primarily supported by increasing demand for clean-label ingredient formulations and stricter sourcing standards throughout the confectionery supply chain. Manufacturers are placing greater emphasis on natural, traceable, and sustainably sourced ingredients while expanding premium product offerings to meet changing consumer preferences. Continued focus on product transparency and ingredient quality is expected to support steady market development across the region.
Key players operating in the global confectionery ingredients market include Archer Daniels Midland Company (ADM), Balchem Corporation, Barry Callebaut AG, Cargill, Incorporated, Corbion N.V., DSM-Firmenich AG, Ingredion Incorporated, Kerry Group plc, Natra S.A., Olam Food Ingredients (OFI), Prova SAS, Puratos Group, Sensient Technologies Corporation, and Tate & Lyle PLC. Companies operating in the confectionery ingredients market are strengthening their competitive position by expanding premium ingredient portfolios, investing in research and development, and introducing innovative clean-label solutions that align with evolving consumer preferences. Manufacturers are increasing investments in natural ingredients, sustainable sourcing programs, and advanced formulation technologies to improve product quality and accelerate innovation. Strategic collaborations with food manufacturers, ingredient suppliers, and distribution partners are helping companies broaden market reach and strengthen customer relationships. Businesses are also enhancing production capabilities, improving supply chain efficiency, and developing customized ingredient solutions tailored to changing formulation requirements.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Ingredient type
- 2.2.3 Source
- 2.2.4 Form
- 2.2.5 Application
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By ingredient type
- 3.8 Future market trends
- 3.9 Technology and innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Ingredient Type, 2022–2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 Cocoa & chocolate ingredients
- 5.3 Dairy ingredients
- 5.4 Sweeteners
- 5.5 Emulsifiers, stabilizers & hydrocolloids
- 5.6 Oils & shortenings
- 5.7 Flavors & colors
- 5.8 Malts & cereal ingredients
- 5.9 Nuts & fruits
- 5.10 Others
Chapter 6 Market Estimates and Forecast, By Source, 2022–2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Natural
- 6.3 Synthetic
Chapter 7 Market Estimates and Forecast, By Form, 2022–2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Dry/powder
- 7.3 Liquid
- 7.4 Gel/paste
Chapter 8 Market Estimates and Forecast, By Application, 2022–2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 Chocolate confectionery
- 8.2.1 Dark chocolate
- 8.2.2 Milk chocolate
- 8.2.3 White & ruby chocolate
- 8.2.4 Compound & filled chocolate products
- 8.3 Sugar confectionery
- 8.3.1 Hard candies & lollipops
- 8.3.2 Caramels, toffees & fudge
- 8.3.3 Marshmallows, fondants & nougat
- 8.4 Bakery confectionery
- 8.4.1 Chocolate-filled & enrobed pastries
- 8.4.2 Cream-filled cookies, biscuits & wafers
- 8.4.3 Confectionery cake decorations & glazing coatings
- 8.5 Chewing gum & jelly confectionery
- 8.5.1 Chewing gum & bubble gum
- 8.5.2 Gummy candies & soft jellies
- 8.5.3 Pectin-based & gelatin-based confections
- 8.6 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022–2035 (USD Billion) (Kilo Tons)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Rest of Europe
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Rest of Asia Pacific
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Rest of Latin America
- 9.6 Middle East and Africa
- 9.6.1 Saudi Arabia
- 9.6.2 South Africa
- 9.6.3 UAE
- 9.6.4 Rest of Middle East and Africa
Chapter 10 Company Profiles
- 10.1 Archer Daniels Midland Company (ADM)
- 10.2 Balchem Corporation
- 10.3 Barry Callebaut AG
- 10.4 Cargill, Incorporated
- 10.5 Corbion N.V.
- 10.6 DSM-Firmenich AG
- 10.7 Ingredion Incorporated
- 10.8 Kerry Group plc
- 10.9 Natra S.A.
- 10.10 Olam Food Ingredients (OFI)
- 10.11 Prova SAS
- 10.12 Puratos Group
- 10.13 Sensient Technologies Corporation
- 10.14 Tate & Lyle PLC

