PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121134
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121134
North America Pet Grooming Products Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
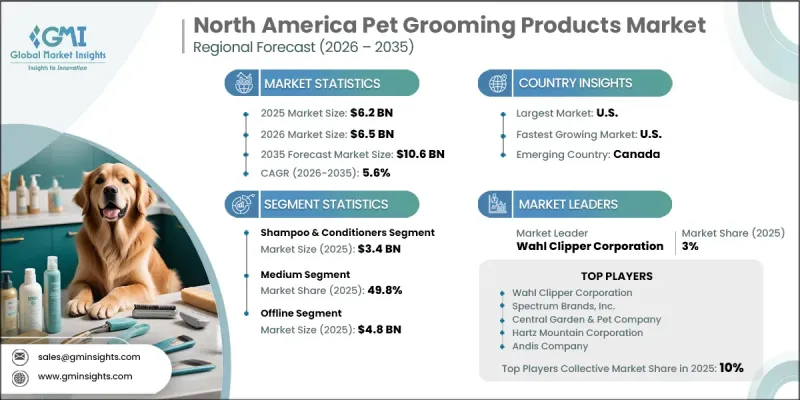
North America PET Grooming Products Market was valued at USD 6.2 billion in 2025 and is estimated to grow at a CAGR of 5.6% to reach USD 10.6 billion by 2035.
North America pet grooming products industry continues to experience steady growth as pet owners increasingly regard companion animals as integral members of the family, resulting in greater spending on premium care and hygiene products. Consumers across the United States and Canada are placing stronger emphasis on maintaining their pets' health, appearance, and overall well-being through regular grooming routines conducted both at home and through professional services. The market is also benefiting from the growing shift toward preventive pet care, where grooming products are viewed as essential components of long-term wellness rather than products intended solely for appearance. Rising demand for formulations that support skin health, coat protection, paw care, and oral hygiene continues to reshape product development across the industry. Premiumization remains another significant growth driver, particularly among younger pet owners who are willing to invest in higher-quality grooming solutions that offer enhanced safety, improved ingredients, and specialized benefits. As consumer expectations continue to evolve, manufacturers are expanding product innovation to address diverse pet care requirements while strengthening the long-term outlook for the North America pet grooming products market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.2 Billion |
| Forecast Value | $10.6 Billion |
| CAGR | 5.6% |
The shampoos and conditioners segment generated USD 3.4 billion in 2025 as cleansing products remain an essential and frequently purchased part of routine pet care across virtually every pet-owning household. Ongoing innovation in product formulations, ingredient quality, and specialized grooming solutions has further strengthened demand across various consumer segments. Manufacturers continue to introduce products tailored to different coat types, life stages, skin sensitivities, and wellness requirements, allowing consumers to select grooming solutions that better match the individual needs of their pets. This growing level of product specialization continues to reinforce the segment's leading position within the overall market.
The medium-priced segment accounted for 49.8% share in 2025. This price tier appeals to the broadest customer base by offering a balance between product quality, brand reputation, and affordability. Consumers seeking dependable grooming products with quality formulations continue to favor mid-priced offerings without transitioning to premium or clinical-grade alternatives. Strong consumer confidence in established brands, combined with accessible pricing and broad product availability through multiple retail channels, continues to support the segment's market leadership. The combination of consistent performance, perceived value, and widespread availability enables this segment to maintain steady demand across the region.
U.S. Pet Grooming Products Market held an 82.1% share, generating USD 5.1 billion in 2025. The United States remains the region's largest and most mature market, supported by high rates of pet ownership, strong consumer spending on pet care, and a highly developed retail landscape. Extensive product availability across specialty pet stores, veterinary clinics, mass retail outlets, and rapidly expanding e-commerce platforms continues to improve consumer accessibility across all pricing categories. The country's well-established distribution infrastructure, combined with growing demand for premium pet care products, continues to create favorable growth opportunities for manufacturers and retailers operating within the market.
Major companies operating in the North America pet grooming products market include Spectrum Brands, Inc., Central Garden & Pet Company, Wahl Clipper Corporation, Hartz Mountain Corporation, Andis Company, TropiClean, Oster Animal Care, SynergyLabs, Bio-Groom, Compana Pet Brands, Nature's Specialties Manufacturing, Double K Industries, Earthbath (Earthwhile Endeavors), Chris Christensen Systems, Warren London, Isle of Dogs, 4Legger, Nootie (Nootie LLC), OPAWZ, Thera-Clean, and Pure and Natural Pet. Companies participating in the North America pet grooming products market are strengthening their competitive position by investing in premium product development, expanding specialized grooming portfolios, and introducing formulations designed to address evolving pet wellness needs. Manufacturers continue to focus on research and development to improve ingredient quality, product safety, and performance while responding to increasing consumer demand for natural and functional grooming solutions. Strategic partnerships with retailers, veterinary channels, grooming professionals, and online platforms are helping companies broaden market reach and improve customer engagement.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope & definitions
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Base estimates and calculations
- 1.3.1 Base year calculation
- 1.3.2 Market estimates & forecasts parameters
- 1.4 Forecast Model
- 1.4.1 Key trends for market estimates
- 1.4.2 Quantified market impact analysis
- 1.4.2.1 Mathematical impact of growth parameters on forecast
- 1.4.3 Scenario analysis framework
- 1.5 Primary research and validation
- 1.5.1 Some of the primary sources (but not limited to)
- 1.6 Data mining sources
- 1.6.1 Paid Sources
- 1.7 Primary research and validation
- 1.7.1 Primary sources
- 1.8 Research Trail & confidence scoring
- 1.8.1 Research trail components
- 1.8.2 Scoring components
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Country
- 2.2.2 Product type
- 2.2.3 Pet type
- 2.2.4 Price
- 2.2.5 End user
- 2.2.6 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing pet humanization
- 3.2.1.2 Growing focus on pet health & hygiene
- 3.2.1.3 Premiumization of pet care
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 Intense market competition
- 3.2.2.2 Product safety concerns
- 3.2.3 Opportunities
- 3.2.3.1 Natural & organic grooming products
- 3.2.3.2 Personalized grooming solutions
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory framework
- 3.4.1 Ingredient safety standards (EPA, EU Cosmetics Regulation, REACH)
- 3.4.2 Labeling & packaging compliance requirements
- 3.4.3 Cruelty-free & vegan certification standards
- 3.4.4 Regional regulatory divergence & trade implications
- 3.5 Pricing analysis (driven by primary research)
- 3.5.1 Historical price trend analysis (2022-2025)
- 3.5.2 Pricing strategy by player type (premium / value / cost-plus)
- 3.6 Trade data analysis (driven by paid database)
- 3.6.1 Import/export volume & value trends by product category
- 3.6.2 Key trade corridors & tariff impact on pet grooming products
- 3.7 Impact of AI & generative AI on the market
- 3.7.1 AI-driven disruption of existing business models
- 3.7.2 GenAI use cases & adoption roadmap by segment
- 3.7.3 Risks, limitations & regulatory considerations for AI in pet care
- 3.8 Distribution infrastructure & channel penetration landscape (driven by primary research)
- 3.8.1 Channel coverage by region & format (online vs. offline penetration rates)
- 3.8.2 Last-mile infrastructure gaps & emerging channel shifts
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By country
- 4.2.1.1 U.S.
- 4.2.1.2 Canada
- 4.2.1 By country
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Product Type, 2022 – 2035 (USD Billion) (Thousand Units)
- 5.1 Key trends
- 5.2 Shampoos & conditioners
- 5.3 Shear & trimming tools
- 5.4 Combs & brushes
- 5.5 Nail care products
- 5.6 Grooming wipes & sprays
- 5.7 Grooming kits & accessories
- 5.8 Others (ear cleaners, dental care, paw balms)
Chapter 6 Market Estimates and Forecast, By Pet Type, 2022 – 2035 (USD Billion) (Thousand Units)
- 6.1 Key trends
- 6.2 Dogs
- 6.3 Cats
- 6.4 Small pets (rabbits, guinea pigs, hamsters)
- 6.5 Birds
- 6.6 Others (reptiles, exotic pets)
Chapter 7 Market Estimates and Forecast, By Price, 2022 – 2035 (USD Billion) (Thousand Units)
- 7.1 Key trends
- 7.2 Low
- 7.3 Medium
- 7.4 High
Chapter 8 Market Estimates and Forecast, By End User, 2022 – 2035 (USD Billion) (Thousand Units)
- 8.1 Key trends
- 8.2 Individual/household pet owners
- 8.3 Professional grooming salons
- 8.4 Veterinary clinics
Chapter 9 Market Estimates and Forecast, By Distribution Channel, 2022 – 2035 (USD Billion) (Thousand Units)
- 9.1 Key trends
- 9.2 Offline
- 9.2.1 Supermarkets & hypermarkets
- 9.2.2 Specialty pet stores
- 9.2.3 Veterinary clinics & pet hospitals
- 9.2.4 Others
- 9.3 Online
- 9.3.1 E-commerce websites
- 9.3.2 Company websites
Chapter 10 Market Estimates and Forecast, By Country, 2022 – 2035 (USD Million) (Million Units)
- 10.1 Key trends
- 10.2 U.S.
- 10.3 Canada
Chapter 11 Company Profiles
- 11.1 Global players
- 11.1.1 Spectrum Brands, Inc.
- 11.1.2 Central Garden & Pet Company
- 11.1.3 Wahl Clipper Corporation
- 11.1.4 Hartz Mountain Corporation
- 11.1.5 Andis Company
- 11.1.6 TropiClean
- 11.1.7 Oster Animal Care
- 11.2 Regional players
- 11.2.1 SynergyLabs
- 11.2.2 Bio-Groom
- 11.2.3 Compana Pet Brands
- 11.2.4 Nature's Specialties Manufacturing
- 11.2.5 Double K Industries
- 11.2.6 Earthbath (Earthwhile Endeavors)
- 11.2.7 Chris Christensen Systems
- 11.3 Emerging players
- 11.3.1 Warren London
- 11.3.2 Isle of Dogs
- 11.3.3 4Legger
- 11.3.4 Nootie (Nootie LLC)
- 11.3.5 OPAWZ
- 11.3.6 Thera-Clean
- 11.3.7 Pure and Natural Pet

