PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2130447
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2130447
Maritime Safety System Market by Offering (Hardware, Software, Services), Safety Application (Navigation & Collision Prevention, Vessel Traffic & Situational Awareness), Operating Environment (Onboard Vessel, Onshore) - Global Forecast to 2031
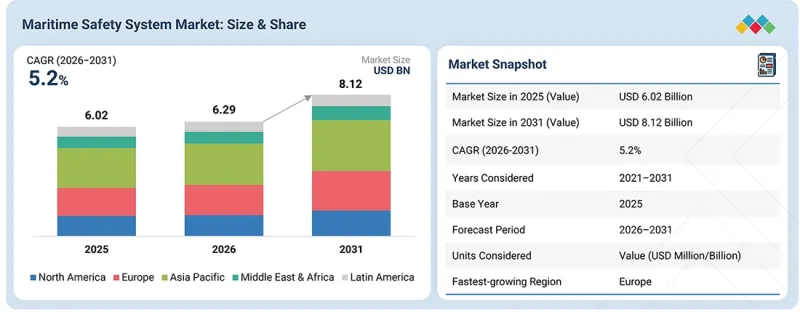
The maritime safety system market is projected to grow from USD 6.29 billion in 2026 to USD 8.12 billion by 2031, at a CAGR of 5.2% during the forecast period. AI-enabled navigation and collision prevention represent a significant opportunity in the maritime safety system market as vessel operators increasingly seek to improve situational awareness, reduce human-error-related incidents, and support safer decision-making in complex and congested maritime environments.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | USD Million/Billion |
| Segments | Offering, Safety Application, Operating Environment, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
AI, machine learning, computer vision, sensor fusion, and advanced analytics can combine inputs from radar, AIS, cameras, LiDAR, GNSS, ECDIS, and other onboard sensors to detect and classify surrounding vessels, obstacles, and potential hazards in real time. These capabilities enable systems to identify abnormal vessel behavior, predict potential collision risks, generate early warnings, and support navigators with decision-support recommendations. The opportunity is particularly strong for commercial shipping, passenger vessels, offshore vessels, ports, and autonomous or remotely operated vessels, where continuous monitoring and rapid response are critical. Companies developing AI-based perception, autonomous navigation, and collision-avoidance solutions can also expand beyond standalone applications by integrating their technologies with existing bridge systems, ECDIS, VTS, and shore-based monitoring platforms.
"Navigation & positioning equipment to be fastest-growing hardware, driven by regulatory requirements and increasing adoption of digital navigation technologies"
By safety application, navigation & collision prevention is expected to account for the largest share of the maritime safety system market in 2026. The segment is supported by the mandatory and safety-critical nature of navigation functions, including radar, ECDIS, AIS, GNSS, navigation sensors, collision-avoidance systems, and related decision-support technologies. The transition toward digital and interoperable navigation is further strengthening demand. The IHO's S-100 framework became operational in January 2026, with S-101 Electronic Navigational Charts, S-102 bathymetric data, S-104 water-level information, S-111 surface currents, S-124 navigational warnings, and S-129 under-keel clearance management entering into force as Phase 1 product specifications. IMO also defines e-navigation around the integration, exchange, presentation, and analysis of marine information to enhance safety of navigation, supporting continued investment in integrated navigation and collision-prevention systems.
"Hardware segment to account for the largest market share in 2026, supported by mandatory carriage requirements and vessel modernization"
By offering, the hardware segment is estimated to account for the largest share of the maritime safety system market in 2026. Maritime safety remains strongly dependent on physical equipment such as navigation and positioning systems, communication and distress equipment, fire and hazard protection equipment, emergency and life-saving equipment, and vessel traffic and monitoring equipment. These systems are subject to regulatory, type-approval, and vessel-specific requirements, creating a relatively stable replacement and upgrade market. At the same time, hardware is increasingly being integrated with software, connectivity, and shore-based services rather than operating as standalone equipment. The transition to S-100-compatible ECDIS is expected to support modernization of navigation hardware, with IHO standards requiring applicable ECDIS equipment to support the relevant S-100 framework.
"Asia Pacific to account for the largest share of the maritime safety system market, driven by stringent regulatory frameworks, advanced shipbuilding, and strong adoption of digital navigation technologies"
Asia Pacific is expected to account for the largest share of the global maritime safety system market, supported by the region's extensive coastline, high concentration of major commercial ports, growing maritime trade, and increasing vessel traffic across key shipping routes. Countries such as China, Japan, India, South Korea, Singapore, and Australia are investing significantly in port modernization, fleet upgrades, vessel monitoring, navigation, and maritime security infrastructure. The region's growing adoption of Automatic Identification Systems (AIS), Global Maritime Distress and Safety Systems (GMDSS), radar and surveillance systems, vessel monitoring solutions, and integrated navigation technologies is further strengthening market demand. In addition, increasing concerns related to maritime accidents, piracy, illegal fishing, coastal security, environmental risks, and vessel traffic management are encouraging governments and shipping companies to deploy advanced safety solutions. Rapid digitalization is also creating opportunities for AI, IoT, real-time monitoring, autonomous navigation, predictive analytics, and connected maritime safety platforms, with IMO actively promoting digitalization and e-navigation across the Asia-Pacific region.
"Europe to register the fastest growth during the forecast period, driven by fleet expansion, shipbuilding activity, digitalization, and autonomous-vessel development"
Europe is the fastest-growing region in the maritime safety system market, supported by a combination of stringent maritime safety regulations, accelerated digitalization, modernization of vessel traffic management, and increasing adoption of advanced navigation and monitoring technologies. The European Union has been actively strengthening its maritime safety framework through the 2024-2025 Maritime Safety Package and the enhanced mandate of the European Maritime Safety Agency (EMSA), with greater emphasis on maritime surveillance, cybersecurity resilience, crisis preparedness, digital systems, and safety enforcement. At the same time, the EU is expanding digital maritime infrastructure through initiatives such as the European Maritime Single Window environment (EMSWe), which became applicable in August 2025 and integrates maritime information exchange across Member States, while SafeSeaNet and other EMSA platforms provide continuous vessel-tracking and operational information to authorities. Regulatory tightening is also directly stimulating demand for vessel monitoring and situational-awareness systems, with the European Commission strengthening Mandatory Ship Reporting Systems to improve monitoring and investigation of unsafe vessels operating in EU waters.
Breakdown of Primaries
In-depth interviews were conducted with chief executive officers (CEOs), innovation and technology directors, system integrators, and executives from various key organizations operating in the maritime safety system market.
- By Company: Tier 1 - 25%, Tier 2 - 41%, and Tier 3 - 34%
- By Designation: Directors - 31%, Managers - 46%, and Others - 23%
- By Region: North America - 39%, Europe - 22%, Asia Pacific - 28%, Middle East & Africa - 4%, and Latin America - 7%
FURUNO (Japan), Kongsberg Maritime (Norway), Wartsila (Finland), Japan Radio Co. (JRC) (Japan), Tokyo Keiki (Japan), Sperry Marine (USA), SRT Marine Systems (UK), Consilium Safety (Sweden), Drager (Germany), NAVTOR (Norway), Marlink (France), Viasat/Inmarsat Maritime (USA), Iridium Communications (USA), Cobham Satcom (UK), VIKING Life-Saving Equipment (Denmark), Survitec (UK), Orca AI (Israel), Avikus (South Korea), SEA.AI (Austria), M2Intelligence (South Korea), Hefring Marine (Iceland), NAPA (Finland), Maritime Optima (Norway), Seaber (France), Clearbot (Hong Kong), FleetMon (Germany), Sea Machines Robotics (USA), and Captain AI (Belgium) are some of the key players in the maritime safety system market.
The study includes an in-depth competitive analysis of these key players in the maritime safety system market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the maritime safety system market by offering (hardware (navigation & positioning equipment, communication & distress equipment, emergency & life-saving equipment, fire & hazard protection equipment and vessel traffic & monitoring equipment), software (navigation & collision avoidance software, vessel traffic & situational awareness software, safety management & monitoring software and emergency response & decision support software)), and services (professional services (installation & integration services, implementation & configuration services, consulting & advisory services, inspection, testing & certification services, training & simulation services)) (managed services (remote safety monitoring services and remote operations & support services)); safety application (navigation & collision prevention, vessel traffic & situational awareness, communication & distress management, emergency response & life safety, fire & hazard protection and vessel & crew safety monitoring); operating environment (onboard vessel, onshore and offshore installation); and region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America). The scope of the report covers detailed information regarding the major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the maritime safety system market. A detailed analysis of the key industry players has been done to provide insights into their business overview, solutions, and services; key strategies; contracts, partnerships, agreements; new product & service launches; mergers & acquisitions; and recent developments associated with the maritime safety system market. Competitive analysis of upcoming startups in the market ecosystem is covered in this report.
Reasons to Buy This Report
The report will provide market leaders and new entrants with information on the closest approximations of the revenue numbers for the overall maritime safety system market and its subsegments. It would help stakeholders understand the competitive landscape and gain more insights to position their business better and plan suitable go-to-market strategies. It also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Increasing maritime safety regulations and compliance requirements, Digitalization of navigation and vessel operations), restraints (High installation and integration costs, Complex certification requirements), opportunities (AI-enabled navigation and collision prevention, S-100-based digital maritime navigation), and challenges (Reliability of AI in safety-critical applications, Integration of heterogeneous systems)
- Product Development/Innovation: Detailed insights into emerging technologies, AI-powered collision avoidance systems, autonomous navigation platforms, satellite communication solutions, integrated bridge systems, remote monitoring platforms, ongoing research & development activities, and new product and service launches in the maritime safety system market
- Market Development: Comprehensive information about high-growth market opportunities, evolving fleet digitalization and autonomous-vessel adoption trends, and regional analysis across North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- Market Diversification: Exhaustive information about new hardware and software solutions, emerging safety applications, untapped end-user segments, regional expansion strategies, and investments across the maritime safety system market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, partnerships, acquisitions, product innovations, and service offerings of FURUNO (Japan), Kongsberg Maritime (Norway), Wartsila (Finland), Japan Radio Co. (JRC) (Japan), Sperry Marine (USA), Consilium Safety (Sweden), Drager (Germany), NAVTOR (Norway), VIKING Life-Saving Equipment (Denmark), Survitec (UK), Orca AI (Israel), and other leading companies operating in the maritime safety system market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.2.1 INCLUSIONS AND EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN MARITIME SAFETY SYSTEM MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES IN MARITIME SAFETY SYSTEM MARKET
- 3.2 MARITIME SAFETY SYSTEM MARKET, BY REGION
- 3.3 MARITIME SAFETY SYSTEM MARKET, BY OFFERING
- 3.4 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OFFERING AND OPERATING ENVIRONMENT
- 3.5 MARITIME SAFETY SYSTEM MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing maritime safety regulations and compliance requirements
- 4.2.1.2 Digitalization of navigation and vessel operations
- 4.2.1.3 Growing maritime traffic and collision risks
- 4.2.1.4 Adoption of autonomous and remotely operated vessels
- 4.2.2 RESTRAINTS
- 4.2.2.1 High installation and integration costs
- 4.2.2.2 Complex certification requirements
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 AI-enabled navigation and collision prevention
- 4.2.3.2 S-100-based digital maritime navigation
- 4.2.3.3 Digital VTS and shore-based safety infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Reliability of AI in safety-critical applications
- 4.2.4.2 Integration of heterogeneous systems
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN MARITIME SAFETY SYSTEMS
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 EVOLUTION OF MARITIME SAFETY SYSTEM
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.2.2 BARGAINING POWER OF SUPPLIERS
- 5.2.3 BARGAINING POWER OF BUYERS
- 5.2.4 THREAT OF SUBSTITUTES
- 5.2.5 THREAT OF NEW ENTRANTS
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN MARITIME SAFETY AND NAVIGATION INDUSTRY
- 5.3.4 TRENDS IN AI, AUTOMATION, AND MARITIME DIGITAL INTELLIGENCE
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 VESSEL TRAFFIC & SITUATIONAL AWARENESS SYSTEM VENDORS
- 5.5.2 MARITIME E-NAVIGATION & DIGITAL SAFETY SOFTWARE VENDORS
- 5.5.3 MARITIME E-NAVIGATION & DIGITAL SAFETY SOFTWARE VENDORS
- 5.5.4 MARITIME SAFETY HARDWARE & MARINE ELECTRONICS VENDORS
- 5.5.5 MARITIME SAFETY SOFTWARE & ANALYTICS VENDORS
- 5.5.6 MARITIME SAFETY CONNECTIVITY & DIGITAL SERVICE PROVIDERS
- 5.5.7 MARITIME SAFETY SYSTEM INTEGRATORS & SERVICE PROVIDERS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE OF OFFERINGS, BY KEY PLAYER, 2026
- 5.6.2 AVERAGE SELLING PRICE OF SAFETY APPLICATIONS, 2026
- 5.7 TRADE ANALYSIS
- 5.7.1 EXPORT SCENARIO OF COMPUTER PROCESSING UNITS (HSN: 847150)
- 5.7.2 IMPORT SCENARIO OF RADIO NAVIGATIONAL AID APPARATUS UNITS (HSN: 852691)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 M2INTELLIGENCE AND NEWPORT SHIP MANAGEMENT: DIGITAL TRANSFORMATION OF MARITIME OPERATIONS
- 5.11.2 WARTSILA ENHANCES VESSEL TRAFFIC MANAGEMENT AND SAFETY AT PORT OF CALLAO
- 5.11.3 JRC ENABLES SAFER NAVIGATION THROUGH J-MARINE NECST AND ECDIS INTEGRATION
- 5.11.4 ST ENGINEERING DEPLOYS AUTONOMOUS NAVIGATION AND COLLISION AVOIDANCE FOR SMAV
- 5.11.5 SAAB UPGRADES VESSEL TRAFFIC SERVICES AT SCHELDT RADAR NETWORK
- 5.11.6 KONGSBERG NORCONTROL DELIVERS VESSEL TRAFFIC SERVICE SYSTEM TO PORT OF LONDON AUTHORITY
- 5.11.7 FURUNO DEPLOYS SURVEILLANCE RADAR FOR YOKOHAMA VESSEL MANAGEMENT CENTRE
- 5.11.8 MARLINK PROTECTS HOPPER DREDGER'S CRITICAL NAVIGATION SYSTEMS
- 5.11.9 AVIKUS ENABLES AUTONOMOUS NAVIGATION ON PRISM COURAGE LNG CARRIER
- 5.12 IMPACT OF 2025 US TARIFF - MARITIME SAFETY SYSTEM MARKET
- 5.12.1 INTRODUCTION
- 5.12.1.1 Tariff/Trade policy updates (January-June 2026)
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.3.1 Strategic shifts and emerging trends
- 5.12.4 IMPACT ON COUNTRIES/REGIONS
- 5.12.4.1 US
- 5.12.4.2 Europe
- 5.12.4.3 China
- 5.12.4.4 Asia Pacific (excluding China)
- 5.12.5 IMPACT ON SAFETY APPLICATIONS
- 5.12.5.1 Navigation & collision prevention
- 5.12.5.2 Vessel traffic & situational awareness
- 5.12.5.3 Communication & distress management
- 5.12.5.4 Emergency response & life safety
- 5.12.5.5 Fire & hazard protection
- 5.12.5.6 Vessel & crew safety monitoring
- 5.12.1 INTRODUCTION
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 RADAR & ADVANCED SENSING TECHNOLOGIES
- 6.1.2 POSITIONING & NAVIGATION TECHNOLOGIES
- 6.1.3 AUTOMATIC IDENTIFICATION & TRACKING TECHNOLOGIES
- 6.1.4 COMMUNICATION & CONNECTIVITY TECHNOLOGIES
- 6.1.5 INTERNET OF THINGS (IOT) & EDGE COMPUTING
- 6.1.6 ARTIFICIAL INTELLIGENCE & MACHINE LEARNING
- 6.1.7 AUTOMATION & AUTONOMOUS NAVIGATION
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 COMPUTER VISION
- 6.2.2 DIGITAL TWINS & SIMULATION
- 6.2.3 ADVANCED DATA ANALYTICS
- 6.2.4 CYBERSECURITY & CYBER-RESILIENCE
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 MARITIME CYBERSECURITY
- 6.3.2 PORT AUTOMATION
- 6.3.3 OFFSHORE INFRASTRUCTURE MONITORING
- 6.3.4 AUTONOMOUS UNDERWATER VEHICLES & REMOTELY OPERATED VEHICLES
- 6.3.5 MARITIME ENVIRONMENTAL MONITORING
- 6.3.6 PREDICTIVE MAINTENANCE
- 6.3.7 QUANTUM POSITIONING & COMMUNICATION
- 6.4 PRODUCT ROADMAP
- 6.5 PATENT ANALYSIS
- 6.5.1 METHODOLOGY
- 6.5.2 PATENTS FILED, BY DOCUMENT TYPE, 2016-2026
- 6.5.3 INNOVATION AND PATENT APPLICATIONS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AI-ENABLED MARITIME DECISION SUPPORT
- 6.6.2 AUTONOMOUS & REMOTELY OPERATED VESSELS
- 6.6.3 S-100 & DIGITAL E-NAVIGATION SERVICES
- 6.6.4 INTELLIGENT VESSEL TRAFFIC SERVICES (VTS)
- 6.6.5 DIGITAL TWIN & PREDICTIVE SAFETY MANAGEMENT
- 6.7 IMPACT OF AI/GEN AI ON MARITIME SAFETY SYSTEM MARKET
- 6.7.1 BEST PRACTICES IN MARITIME SAFETY SYSTEM MARKET
- 6.7.2 CASE STUDIES OF AI IMPLEMENTATION IN MARITIME SAFETY SYSTEM MARKET
- 6.7.3 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN MARITIME SAFETY SYSTEM MARKET
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.8.1 KONGSBERG MARITIME: AI-ENABLED MARITIME SITUATIONAL AWARENESS
- 6.8.2 JRC: AI-BASED INTEGRATED NAVIGATION SUPPORT
7 TARIFF ANALYSIS AND REGULATORY LANDSCAPE
- 7.1 TARIFF RELATED TO MARITIME NAVIGATION AND SAFETY EQUIPMENT
- 7.1.1 TARIFF RELATED TO RADIO NAVIGATIONAL AID APPARATUS (HSN: 852691)
- 7.2 REGIONAL REGULATIONS AND COMPLIANCE
- 7.2.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.2.2 KEY REGULATIONS
- 7.2.2.1 North America
- 7.2.2.1.1 US Navigation Safety Regulations - 33 CFR Part 164 (US)
- 7.2.2.1.2 Navigation Safety Regulations, 2020 - Canada
- 7.2.2.2 Europe
- 7.2.2.2.1 Directive 2002/59/EC - Vessel Traffic Monitoring and Information System (EU)
- 7.2.2.2.2 Directive 2009/45/EC - Safety Rules and Standards for Passenger Ships (EU)
- 7.2.2.2.3 Merchant Shipping (Safety of Navigation) Regulations 2020 - UK
- 7.2.2.3 Asia Pacific
- 7.2.2.3.1 SOLAS Convention - Safety of Life at Sea
- 7.2.2.3.2 COLREG 1972 - International Regulations for Preventing Collisions at Sea
- 7.2.2.3.3 STCW Convention - Standards of Training, Certification and Watchkeeping for Seafarers
- 7.2.2.4 Middle East & Africa (MEA)
- 7.2.2.4.1 Riyadh Memorandum of Understanding on Port State Control
- 7.2.2.4.2 Abuja Memorandum of Understanding on Port State Control
- 7.2.2.4.3 Indian Ocean Memorandum of Understanding on Port State Control
- 7.2.2.5 Latin America
- 7.2.2.5.1 Acuerdo de Vina del Mar - Port State Control
- 7.2.2.5.2 Caribbean Memorandum of Understanding on Port State Control
- 7.2.2.1 North America
- 7.2.3 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS INDUSTRY APPLICATIONS
9 MARITIME SAFETY SYSTEM MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 DRIVERS: MARITIME SAFETY SYSTEM MARKET, BY OFFERING
- 9.2 HARDWARE
- 9.2.1 NAVIGATION & POSITIONING EQUIPMENT
- 9.2.1.1 Enabling real-time navigation, situational awareness, and decision support
- 9.2.2 COMMUNICATION & DISTRESS EQUIPMENT
- 9.2.2.1 Supporting reliable distress alerting, emergency response, and ship-shore information exchange
- 9.2.3 EMERGENCY & LIFE-SAVING EQUIPMENT
- 9.2.3.1 Enhancing maritime emergency systems for safety and reliability
- 9.2.4 FIRE & HAZARD PROTECTION EQUIPMENT
- 9.2.4.1 Addressing emerging fire and hazardous conditions across increasingly complex vessel environments
- 9.2.5 VESSEL TRAFFIC & MONITORING EQUIPMENT
- 9.2.5.1 Providing continuous vessel tracking, enhanced situational awareness, and reliable maritime traffic management across complex operating environments
- 9.2.1 NAVIGATION & POSITIONING EQUIPMENT
- 9.3 SOFTWARE
- 9.3.1 NAVIGATION & COLLISION-AVOIDANCE SOFTWARE
- 9.3.1.1 Increasing adoption of digital navigation, integrated bridge systems, and advanced collision-risk detection to drive segment
- 9.3.2 VESSEL TRAFFIC & SITUATIONAL AWARENESS SOFTWARE
- 9.3.2.1 Growing vessel traffic and need for real-time maritime-domain awareness to drive segment
- 9.3.3 SAFETY MANAGEMENT & MONITORING SOFTWARE
- 9.3.3.1 Increasing demand for centralized monitoring of vessel systems, safety conditions, and operational risks to drive segment
- 9.3.4 EMERGENCY RESPONSE & DECISION-SUPPORT SOFTWARE
- 9.3.4.1 Rising requirements for faster incident detection, emergency coordination, and data-driven response to drive segment
- 9.3.1 NAVIGATION & COLLISION-AVOIDANCE SOFTWARE
- 9.4 SERVICES
- 9.4.1 PROFESSIONAL SERVICES
- 9.4.1.1 Increasing demand for installation, system integration, retrofit, certification, training, and commissioning to drive segment
- 9.4.1.2 Installation & integration services
- 9.4.1.3 Implementation & configuration services
- 9.4.1.4 Consulting & advisory services
- 9.4.1.5 Inspection, testing, & certification services
- 9.4.1.6 Training & simulation services
- 9.4.2 MANAGED SERVICES
- 9.4.2.1 Growing adoption of remote monitoring, predictive maintenance, remote technical support, and connected ship-shore operations to drive segment
- 9.4.2.2 Remote safety monitoring services
- 9.4.2.3 Remote operations & support services
- 9.4.1 PROFESSIONAL SERVICES
10 MARITIME SAFETY SYSTEM MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.1.1 DRIVERS: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION
- 10.2 NAVIGATION & COLLISION PREVENTION
- 10.2.1 INCREASING VESSEL TRAFFIC AND NEED FOR IMPROVING COLLISION-RISK DETECTION TO DRIVE ADOPTION OF ADVANCED NAVIGATION AND COLLISION-PREVENTION SYSTEMS
- 10.3 VESSEL TRAFFIC & SITUATIONAL AWARENESS
- 10.3.1 GROWING MARITIME TRAFFIC AND NEED FOR REAL-TIME VESSEL TRACKING TO DRIVE DEMAND FOR VTS, AIS, RADAR, AND INTEGRATED SITUATIONAL-AWARENESS SYSTEMS
- 10.4 COMMUNICATION & DISTRESS MANAGEMENT
- 10.4.1 MODERNIZATION OF GMDSS AND NEED FOR RELIABLE GLOBAL DISTRESS COMMUNICATIONS TO DRIVE DEMAND FOR ADVANCED MARITIME COMMUNICATION AND SAFETY SYSTEMS
- 10.5 EMERGENCY RESPONSE & LIFE SAFETY
- 10.5.1 INCREASING FOCUS ON EMERGENCY PREPAREDNESS AND RAPID RESPONSE TO DRIVE DEMAND FOR LIFE-SAVING AND EMERGENCY-RESPONSE SYSTEMS
- 10.6 FIRE & HAZARD PROTECTION
- 10.6.1 STRICTER FIRE-SAFETY REQUIREMENTS AND EMERGENCE OF NEW VESSEL FUELS AND CARGO RISKS TO DRIVE DEMAND FOR ADVANCED FIRE DETECTION, SUPPRESSION, AND HAZARD-PROTECTION SYSTEMS
- 10.7 VESSEL & CREW SAFETY MONITORING
- 10.7.1 GROWING DEMAND FOR CONTINUOUS MONITORING OF VESSEL AND CREW CONDITIONS TO DRIVE ADOPTION OF CONNECTED SENSORS, REMOTE MONITORING, AND REAL-TIME SAFETY-MANAGEMENT SYSTEMS
11 MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT
- 11.1 INTRODUCTION
- 11.1.1 DRIVERS: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT
- 11.2 ONBOARD VESSEL
- 11.2.1 FLEET MODERNIZATION, REGULATORY COMPLIANCE, AND REPLACEMENT OF AGING ONBOARD SAFETY SYSTEMS DRIVING ADOPTION
- 11.3 ONSHORE
- 11.3.1 PORT EXPANSION, VTS MODERNIZATION, AND INCREASING SHIP-SHORE INFORMATION EXCHANGE DRIVING DEMAND FOR ONSHORE SAFETY SYSTEMS
- 11.4 OFFSHORE INSTALLATION
- 11.4.1 GROWING OFFSHORE OPERATIONS AND NEED FOR RELIABLE MONITORING, COMMUNICATION, EMERGENCY RESPONSE, AND HAZARD PROTECTION DRIVING ADOPTION
12 MARITIME SAFETY SYSTEM MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET DRIVERS
- 12.2.2 US
- 12.2.2.1 Strengthening maritime safety adoption through fleet modernization, port infrastructure investment, and cybersecurity requirements
- 12.2.3 CANADA
- 12.2.3.1 Driving maritime safety adoption through vessel traffic services modernization, coastal and Arctic operations, and investment in navigation and monitoring infrastructure
- 12.3 EUROPE
- 12.3.1 EUROPE: MARITIME SAFETY SYSTEM MARKET DRIVERS
- 12.3.2 UK
- 12.3.2.1 Accelerating maritime safety adoption through digital navigation, maritime autonomy initiatives, fleet modernization, and advanced vessel traffic and safety technologies
- 12.3.3 GERMANY
- 12.3.3.1 Strengthening maritime safety adoption through advanced port infrastructure, autonomous shipping development, and modernization of navigation and vessel traffic systems
- 12.3.4 FRANCE
- 12.3.4.1 Expanding maritime safety adoption through dense shipping activity, port digitalization, and modernization of navigation systems
- 12.3.5 ITALY
- 12.3.5.1 Driving maritime safety adoption through VTS modernization, extensive passenger and commercial vessel activity, and investment in maritime surveillance and safety infrastructure
- 12.3.6 SPAIN
- 12.3.6.1 Scaling maritime safety adoption through port digitalization, navigation safety programs, and continued investment in surveillance and emergency-response capabilities
- 12.3.7 GREECE
- 12.3.7.1 Strengthening maritime safety through fleet dominance, digital surveillance, and navigation modernization
- 12.3.8 REST OF EUROPE
- 12.4 ASIA PACIFIC
- 12.4.1 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET DRIVERS
- 12.4.2 CHINA
- 12.4.2.1 Strengthening maritime safety adoption through smart-shipping initiatives, autonomous-vessel development, digital maritime infrastructure, and navigation systems modernization
- 12.4.3 INDIA
- 12.4.3.1 Driving maritime safety adoption through port modernization, digital maritime governance, coastal and inland navigation development, and stronger navigation and communication infrastructure
- 12.4.4 JAPAN
- 12.4.4.1 Advancing maritime safety through autonomous-shipping standards, digital navigation, advanced marine electronics, and modernization of communication and search-and-rescue systems
- 12.4.5 SOUTH KOREA
- 12.4.5.1 Accelerating maritime safety technology through AI-enabled navigation, intelligent maritime traffic systems, autonomous vessels, and digital maritime infrastructure
- 12.4.6 AUSTRALIA & NEW ZEALAND
- 12.4.6.1 Supporting maritime safety modernization through autonomous-vessel development, digitalization, port and harbor safety upgrades, and strengthened regulatory frameworks
- 12.4.7 REST OF ASIA PACIFIC
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET DRIVERS
- 12.5.2 SAUDI ARABIA
- 12.5.2.1 Expanding maritime safety capabilities through port development, digital maritime infrastructure, navigation modernization, and stronger regulatory and compliance programs
- 12.5.3 UAE
- 12.5.3.1 Strengthening maritime safety through major port infrastructure, digital maritime services, vessel traffic management, and advanced navigation and monitoring systems
- 12.5.4 SOUTH AFRICA
- 12.5.4.1 Advancing maritime safety through digital maritime services, Maritime Single Window initiatives, port-system modernization, and stronger vessel monitoring and operational capabilities
- 12.5.5 QATAR
- 12.5.5.1 Developing maritime safety capabilities through navigation and communication modernization, maritime regulatory compliance, search-and-rescue preparedness, and digital maritime technologies
- 12.5.6 REST OF MIDDLE EAST & AFRICA
- 12.6 LATIN AMERICA
- 12.6.1 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET DRIVERS
- 12.6.2 BRAZIL
- 12.6.2.1 Expanding maritime safety adoption through port modernization, coastal and inland navigation development, offshore operations, and technology-enabled maritime infrastructure
- 12.6.3 MEXICO
- 12.6.3.1 Strengthening maritime safety through commercial port and offshore activity, maritime surveillance, regulatory enforcement, and modernization of navigation and communication systems
- 12.6.4 ARGENTINA
- 12.6.4.1 Advancing maritime safety through AIS-based vessel monitoring, fishing-vessel safety regulation, maritime surveillance, and modernization of navigation and emergency-response capabilities
- 12.6.5 REST OF LATIN AMERICA
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYER COMPETITIVE STRATEGIES, 2021-2026
- 13.3 REVENUE ANALYSIS, 2021-2025
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.4.1 MARKET RANKING ANALYSIS, 2025
- 13.5 PRODUCT COMPARISON
- 13.5.1 COMPARATIVE ANALYSIS OF MARITIME SAFETY SYSTEM PLATFORMS
- 13.5.1.1 Kongsberg Maritime's K-Bridge Integrated Bridge System
- 13.5.1.2 FURUNO VOYAGER / Marine Radar & ECDIS
- 13.5.1.3 JRC Marine Navigation & Communication Systems
- 13.5.1.4 M2Intelligence ECDISmart
- 13.5.1 COMPARATIVE ANALYSIS OF MARITIME SAFETY SYSTEM PLATFORMS
- 13.6 COMPANY EVALUATION MATRIX: INTEGRATED NAVIGATION, COMMUNICATION, & VESSEL SAFETY SYSTEMS, 2025
- 13.6.1 STARS
- 13.6.2 EMERGING LEADERS
- 13.6.3 PERVASIVE PLAYERS
- 13.6.4 PARTICIPANTS
- 13.6.5 COMPANY FOOTPRINT: INTEGRATED NAVIGATION, COMMUNICATION, & VESSEL SAFETY SYSTEMS, 2025
- 13.6.5.1 Company footprint
- 13.6.5.2 Regional footprint
- 13.6.5.3 Offering footprint
- 13.6.5.4 Application footprint
- 13.6.5.5 Operating environment footprint
- 13.7 COMPANY EVALUATION MATRIX: EMERGENCY, LIFE, & HAZARD SAFETY SYSTEMS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: EMERGENCY, LIFE, & HAZARD SAFETY SYSTEMS, 2025
- 13.7.5.1 Company footprint
- 13.7.5.2 Regional footprint
- 13.7.5.3 Offering footprint
- 13.7.5.4 Application footprint
- 13.7.5.5 Operating environment footprint
- 13.8 COMPANY EVALUATION MATRIX: INTELLIGENT & AUTONOMOUS MARITIME SAFETY SYSTEMS, 2025
- 13.8.1 STARS
- 13.8.2 EMERGING LEADERS
- 13.8.3 PERVASIVE PLAYERS
- 13.8.4 PARTICIPANTS
- 13.8.5 COMPANY FOOTPRINT: INTELLIGENT & AUTONOMOUS MARITIME SAFETY SYSTEMS, 2025
- 13.8.5.1 Company footprint
- 13.8.5.2 Regional footprint
- 13.8.5.3 Offering footprint
- 13.8.5.4 Application footprint
- 13.8.5.5 Operating environment footprint
- 13.9 COMPANY VALUATION AND FINANCIAL METRICS
- 13.10 COMPETITIVE SCENARIO
- 13.10.1 PRODUCT LAUNCHES/ENHANCEMENTS
- 13.10.2 DEALS
14 COMPANY PROFILES
- 14.1 INTRODUCTION
- 14.2 MAJOR PLAYERS
- 14.2.1 KONGSBERG MARITIME
- 14.2.1.1 Business overview
- 14.2.1.2 Products/Solutions/Services offered
- 14.2.1.3 Recent developments
- 14.2.1.3.1 Product launches/enhancements
- 14.2.1.3.2 Deals
- 14.2.1.3.3 Other developments
- 14.2.1.4 MnM view
- 14.2.1.4.1 Key strengths
- 14.2.1.4.2 Strategic choices
- 14.2.1.4.3 Weaknesses and competitive threats
- 14.2.2 FURUNO ELECTRIC CO., LTD.
- 14.2.2.1 Business overview
- 14.2.2.2 Products/Solutions/Services offered
- 14.2.2.3 Recent developments
- 14.2.2.3.1 Product launches/enhancements
- 14.2.2.3.2 Deals
- 14.2.2.3.3 Other developments
- 14.2.2.4 MnM view
- 14.2.2.4.1 Key strengths
- 14.2.2.4.2 Strategic choices
- 14.2.2.4.3 Weaknesses and competitive threats
- 14.2.3 JAPAN RADIO CO., LTD. (JRC)
- 14.2.3.1 Business overview
- 14.2.3.2 Products/Solutions/Services offered
- 14.2.3.3 Recent developments
- 14.2.3.3.1 Product launches/enhancements
- 14.2.3.3.2 Deals
- 14.2.3.4 MnM view
- 14.2.3.4.1 Key strengths
- 14.2.3.4.2 Strategic choices
- 14.2.3.4.3 Weaknesses and competitive threats
- 14.2.4 NAVICO GROUP
- 14.2.4.1 Business overview
- 14.2.4.2 Products/Solutions/Services offered
- 14.2.4.3 Recent developments
- 14.2.4.3.1 Product launches/enhancements
- 14.2.4.3.2 Deals
- 14.2.4.4 MnM view
- 14.2.4.4.1 Key strengths
- 14.2.4.4.2 Strategic choices
- 14.2.4.4.3 Weaknesses and competitive threats
- 14.2.5 GARMIN
- 14.2.5.1 Business overview
- 14.2.5.2 Products/Solutions/Services offered
- 14.2.5.3 Recent developments
- 14.2.5.3.1 Product launches/enhancements
- 14.2.5.3.2 Deals
- 14.2.5.4 MnM view
- 14.2.5.4.1 Key strengths
- 14.2.5.4.2 Strategic choices
- 14.2.5.4.3 Weaknesses and competitive threats
- 14.2.6 CONSILIUM SAFETY
- 14.2.6.1 Business overview
- 14.2.6.2 Products/Solutions/Services offered
- 14.2.6.3 Recent developments
- 14.2.6.3.1 Product launches/enhancements
- 14.2.6.3.2 Deals
- 14.2.7 ANSCHUTZ
- 14.2.7.1 Business overview
- 14.2.7.2 Products/Solutions/Services offered
- 14.2.7.3 Recent developments
- 14.2.7.3.1 Deals
- 14.2.8 TOKYO KEIKI INC.
- 14.2.8.1 Business overview
- 14.2.8.2 Products/Solutions/Services offered
- 14.2.8.3 Recent developments
- 14.2.8.3.1 Product launches/enhancements
- 14.2.8.3.2 Deals
- 14.2.8.3.3 Other developments
- 14.2.9 COBHAM SATCOM
- 14.2.9.1 Business overview
- 14.2.9.2 Products/Solutions/Services offered
- 14.2.9.3 Recent developments
- 14.2.9.3.1 Product launches/enhancements
- 14.2.9.3.2 Deals
- 14.2.9.3.3 Other developments
- 14.2.10 SPERRY MARINE
- 14.2.10.1 Business overview
- 14.2.10.2 Products/Solutions/Services offered
- 14.2.10.3 Recent developments
- 14.2.10.3.1 Product launches/enhancements
- 14.2.10.3.2 Deals
- 14.2.10.3.3 Other developments
- 14.2.1 KONGSBERG MARITIME
- 14.3 OTHER PLAYERS
- 14.3.1 M2INTELLIGENCE
- 14.3.1.1 Business overview
- 14.3.1.2 Products/Solutions/Services offered
- 14.3.1.3 Recent developments
- 14.3.1.3.1 Product launches/enhancements
- 14.3.1.4 MnM view
- 14.3.1.4.1 Key strengths
- 14.3.1.4.2 Strategic choices
- 14.3.1.4.3 Weaknesses and competitive threats
- 14.3.2 VIKING LIFE-SAVING EQUIPMENT
- 14.3.3 SRT MARINE SYSTEMS PLC
- 14.3.4 IRIDIUM COMMUNICATIONS INC.
- 14.3.5 ORCA AI
- 14.3.6 AVIKUS
- 14.3.7 SEA.AI
- 14.3.8 NAPA
- 14.3.9 HEFRING MARINE
- 14.3.10 MARITIME OPTIMA
- 14.3.11 FLEETMON
- 14.3.12 SEABER
- 14.3.13 SEA MACHINES ROBOTICS
- 14.3.14 CLEARBOT
- 14.3.15 CAPTAIN AI
- 14.3.16 OCEAN INFINITY
- 14.3.17 SEA MACHINES ROBOTICS
- 14.3.18 ORION/SAT
- 14.3.19 NAUTICUS ROBOTICS
- 14.3.20 BUFFALO AUTOMATION
- 14.3.21 SHIPIN SYSTEMS
- 14.3.22 SHONE
- 14.3.23 DIMEQ
- 14.3.24 AETHER NORDIC
- 14.3.1 M2INTELLIGENCE
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Breakup of primary profiles
- 15.1.2.2 Key industry insights
- 15.2 MARKET BREAKUP AND DATA TRIANGULATION
- 15.3 MARKET SIZE ESTIMATION
- 15.3.1 TOP-DOWN APPROACH
- 15.3.2 BOTTOM-UP APPROACH
- 15.4 MARKET FORECAST
- 15.5 RESEARCH ASSUMPTIONS
- 15.6 RESEARCH LIMITATIONS
16 ADJACENT AND RELATED MARKETS
- 16.1 INTRODUCTION
- 16.2 SMART TRANSPORTATION MARKET - GLOBAL FORECAST TO 2032
- 16.2.1 MARKET DEFINITION
- 16.2.2 MARKET OVERVIEW
- 16.2.2.1 Smart transportation market, by transportation mode
- 16.2.2.2 Smart transportation market, by end user
- 16.2.2.3 Smart transportation market, by region
- 16.3 TRANSPORTATION MANAGEMENT SYSTEM MARKET - GLOBAL FORECAST TO 2030
- 16.3.1 MARKET DEFINITION
- 16.3.2 MARKET OVERVIEW
- 16.3.2.1 Transportation management system market, by offering
- 16.3.2.2 Transportation management system market, by transportation mode
- 16.3.2.3 Transportation management system market, by end user
- 16.3.2.4 Transportation management system market, by region
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS
List of Tables
- TABLE 1 MARITIME SAFETY SYSTEM MARKET DETAILED SEGMENTATION
- TABLE 2 USD EXCHANGE RATE, 2023-2025
- TABLE 3 IMPACT OF PORTER'S FIVE FORCES ON MARITIME SAFETY SYSTEM MARKET
- TABLE 4 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2022-2031
- TABLE 5 ROLE OF COMPANIES IN MARITIME SAFETY SYSTEM MARKET ECOSYSTEM
- TABLE 6 AVERAGE SELLING PRICE OF OFFERINGS, BY KEY PLAYER, 2026
- TABLE 7 AVERAGE SELLING PRICE OF SAFETY APPLICATIONS, 2026
- TABLE 8 MARITIME SAFETY SYSTEM MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 9 TARIFF/TRADE POLICY UPDATES (JANUARY-JUNE 2026)
- TABLE 10 US ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 11 PATENTS FILED, 2016-2026
- TABLE 12 LIST OF TOP PATENTS IN MARITIME SAFETY SYSTEM MARKET, 2026
- TABLE 13 TOP USE CASES AND MARKET POTENTIAL
- TABLE 14 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 15 MARITIME SAFETY SYSTEM MARKET: CASE STUDIES RELATED TO AI AND ADVANCED TECHNOLOGY IMPLEMENTATION
- TABLE 16 TARIFF RELATED TO RADIO NAVIGATIONAL AID APPARATUS (HSN: 852691), 2026
- TABLE 17 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 LATIN AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 GLOBAL INDUSTRY STANDARDS FOR MARITIME SAFETY SYSTEMS
- TABLE 23 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE APPLICATIONS
- TABLE 24 KEY BUYING CRITERIA FOR TOP THREE APPLICATIONS
- TABLE 25 UNMET NEEDS IN MARITIME SAFETY SYSTEM MARKET, BY APPLICATION
- TABLE 26 MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 27 MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 28 HARDWARE: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2021-2025 (USD MILLION)
- TABLE 29 HARDWARE: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 30 HARDWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 31 HARDWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 32 NAVIGATION & POSITIONING EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 33 NAVIGATION & POSITIONING EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 34 COMMUNICATION & DISTRESS EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 35 COMMUNICATION & DISTRESS EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 36 EMERGENCY & LIFE-SAVING EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 37 EMERGENCY & LIFE-SAVING EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 38 FIRE & HAZARD PROTECTION EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 39 FIRE & HAZARD PROTECTION EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 40 VESSEL TRAFFIC & MONITORING EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 41 VESSEL TRAFFIC & MONITORING EQUIPMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 42 SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2021-2025 (USD MILLION)
- TABLE 43 SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 44 SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 45 SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 46 NAVIGATION & COLLISION-AVOIDANCE SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 47 NAVIGATION AND COLLISION-AVOIDANCE SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 48 VESSEL TRAFFIC & SITUATIONAL AWARENESS SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 49 VESSEL TRAFFIC & SITUATIONAL AWARENESS SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 50 SAFETY MANAGEMENT & MONITORING SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 51 SAFETY MANAGEMENT & MONITORING SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 52 EMERGENCY RESPONSE & DECISION-SUPPORT SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 53 EMERGENCY RESPONSE & DECISION-SUPPORT SOFTWARE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 54 SERVICES: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2021-2025 (USD MILLION)
- TABLE 55 SERVICES: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 56 SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 57 SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 58 PROFESSIONAL SERVICES: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2021-2025 (USD MILLION)
- TABLE 59 PROFESSIONAL SERVICES: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 60 PROFESSIONAL SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 61 PROFESSIONAL SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 62 INSTALLATION & INTEGRATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 63 INSTALLATION & INTEGRATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 64 IMPLEMENTATION & CONFIGURATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 65 IMPLEMENTATION & CONFIGURATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 66 CONSULTING & ADVISORY SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 67 CONSULTING & ADVISORY SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 68 INSPECTION, TESTING, & CERTIFICATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 69 INSPECTION, TESTING, & CERTIFICATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 70 TRAINING & SIMULATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 71 TRAINING & SIMULATION SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 72 MANAGED SERVICES: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2021-2025 (USD MILLION)
- TABLE 73 MANAGED SERVICES: MARITIME SAFETY SYSTEM MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 74 MANAGED SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 75 MANAGED SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 76 REMOTE SAFETY MONITORING SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 77 REMOTE SAFETY MONITORING SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 78 REMOTE OPERATIONS & SUPPORT SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 79 REMOTE OPERATIONS & SUPPORT SERVICES: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 80 MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 81 MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 82 NAVIGATION & COLLISION PREVENTION: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 83 NAVIGATION & COLLISION PREVENTION: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 84 VESSEL TRAFFIC & SITUATIONAL AWARENESS: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 85 VESSEL TRAFFIC & SITUATIONAL AWARENESS: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 86 COMMUNICATION & DISTRESS MANAGEMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 87 COMMUNICATION & DISTRESS MANAGEMENT: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 88 EMERGENCY RESPONSE & LIFE SAFETY: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 89 EMERGENCY RESPONSE & LIFE SAFETY: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 90 FIRE & HAZARD PROTECTION: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 91 FIRE & HAZARD PROTECTION: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 92 VESSEL & CREW SAFETY MONITORING: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 93 VESSEL & CREW SAFETY MONITORING: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 94 MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 95 MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 96 ONBOARD VESSEL: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 97 ONBOARD VESSEL: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 98 ONSHORE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 99 ONSHORE: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 100 OFFSHORE INSTALLATION: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 101 OFFSHORE INSTALLATION: MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 102 MARITIME SAFETY SYSTEM MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 103 MARITIME SAFETY SYSTEM MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 104 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 105 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 106 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 107 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 108 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 109 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 110 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 111 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 112 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 113 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 114 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 115 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 116 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 117 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 118 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 119 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 120 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 121 NORTH AMERICA: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 122 US: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 123 US: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 124 US: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 125 US: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 126 US: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 127 US: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 128 US: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 129 US: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 130 US: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 131 US: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 132 US: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 133 US: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 134 US: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 135 US: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 136 US: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 137 US: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 138 CANADA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 139 CANADA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 140 CANADA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 141 CANADA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 142 CANADA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 143 CANADA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 144 CANADA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 145 CANADA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 146 CANADA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 147 CANADA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 148 CANADA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 149 CANADA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 150 CANADA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 151 CANADA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 152 CANADA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 153 CANADA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 154 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 155 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 156 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 157 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 158 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 159 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 160 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 161 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 162 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 163 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 164 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 165 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 166 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 167 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 168 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 169 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 170 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 171 EUROPE: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 172 UK: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 173 UK: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 174 UK: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 175 UK: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 176 UK: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 177 UK: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 178 UK: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 179 UK: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 180 UK: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 181 UK: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 182 UK: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 183 UK: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 184 UK: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 185 UK: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 186 UK: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 187 UK: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 188 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 189 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 190 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 191 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 192 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 193 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 194 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 195 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 196 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 197 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 198 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 199 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 200 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 201 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 202 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 203 GERMANY: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 204 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 205 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 206 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 207 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 208 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 209 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 210 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 211 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 212 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 213 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 214 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 215 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 216 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 217 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 218 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 219 FRANCE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 220 ITALY: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 221 ITALY: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 222 ITALY: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 223 ITALY: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 224 ITALY: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 225 ITALY: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 226 ITALY: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 227 ITALY: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 228 ITALY: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 229 ITALY: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 230 ITALY: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 231 ITALY: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 232 ITALY: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 233 ITALY: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 234 ITALY: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 235 ITALY: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 236 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 237 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 238 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 239 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 240 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 241 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 242 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 243 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 244 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 245 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 246 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 247 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 248 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 249 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 250 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 251 SPAIN: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 252 GREECE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 253 GREECE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 254 GREECE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 255 GREECE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 256 GREECE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 257 GREECE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 258 GREECE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 259 GREECE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 260 GREECE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 261 GREECE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 262 GREECE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 263 GREECE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 264 GREECE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 265 GREECE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 266 GREECE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 267 GREECE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 268 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 269 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 270 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 271 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 272 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 273 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 274 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 275 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 276 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 277 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 278 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 279 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 280 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 281 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 282 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 283 REST OF EUROPE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 284 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 285 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 286 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 287 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 288 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 289 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 290 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 291 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 292 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 293 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 294 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 295 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 296 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 297 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 298 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 299 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 300 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 301 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 302 CHINA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 303 CHINA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 304 CHINA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 305 CHINA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 306 CHINA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 307 CHINA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 308 CHINA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 309 CHINA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 310 CHINA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 311 CHINA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 312 CHINA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 313 CHINA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 314 CHINA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 315 CHINA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 316 CHINA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 317 CHINA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 318 INDIA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 319 INDIA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 320 INDIA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 321 INDIA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 322 INDIA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 323 INDIA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 324 INDIA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 325 INDIA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 326 INDIA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 327 INDIA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 328 INDIA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 329 INDIA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 330 INDIA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 331 INDIA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 332 INDIA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 333 INDIA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 334 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 335 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 336 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 337 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 338 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 339 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 340 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 341 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 342 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 343 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 344 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 345 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 346 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 347 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 348 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 349 JAPAN: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 350 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 351 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 352 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 353 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 354 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 355 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 356 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 357 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 358 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 359 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 360 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 361 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 362 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 363 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 364 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 365 SOUTH KOREA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 366 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 367 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 368 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 369 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 370 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 371 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 372 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 373 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 374 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 375 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 376 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 377 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 378 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 379 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 380 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 381 AUSTRALIA & NEW ZEALAND: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 382 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 383 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 384 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 385 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 386 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 387 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 388 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 389 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 390 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 391 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 392 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 393 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 394 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 395 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 396 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 397 REST OF ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 398 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 399 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 400 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 401 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 402 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 403 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 404 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 405 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 406 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 407 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 408 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 409 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 410 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 411 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 412 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 413 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 414 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 415 MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 416 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 417 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 418 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 419 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 420 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 421 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 422 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 423 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 424 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 425 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 426 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 427 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 428 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 429 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 430 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 431 SAUDI ARABIA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 432 UAE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 433 UAE: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 434 UAE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 435 UAE: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 436 UAE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 437 UAE: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 438 UAE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 439 UAE: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 440 UAE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 441 UAE: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 442 UAE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 443 UAE: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 444 UAE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 445 UAE: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 446 UAE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 447 UAE: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 448 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 449 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 450 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 451 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 452 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 453 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 454 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 455 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 456 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 457 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 458 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 459 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 460 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 461 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 462 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 463 SOUTH AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 464 QATAR: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 465 QATAR: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 466 QATAR: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 467 QATAR: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 468 QATAR: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 469 QATAR: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 470 QATAR: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 471 QATAR: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 472 QATAR: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 473 QATAR: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 474 QATAR: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 475 QATAR: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 476 QATAR: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 477 QATAR: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 478 QATAR: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 479 QATAR: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 480 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 481 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 482 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 483 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 484 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 485 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 486 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 487 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 488 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 489 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 490 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 491 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 492 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 493 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 494 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 495 REST OF MIDDLE EAST & AFRICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 496 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 497 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 498 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 499 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 500 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 501 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 502 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 503 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 504 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 505 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 506 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 507 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 508 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 509 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 510 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 511 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 512 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 513 LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 514 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 515 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 516 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 517 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 518 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 519 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 520 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 521 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 522 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 523 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 524 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 525 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 526 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 527 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 528 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 529 BRAZIL: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 530 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 531 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 532 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 533 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 534 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 535 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 536 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 537 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 538 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 539 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 540 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 541 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 542 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 543 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 544 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 545 MEXICO: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 546 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 547 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 548 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 549 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 550 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 551 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 552 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 553 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 554 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 555 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 556 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 557 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 558 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 559 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 560 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 561 ARGENTINA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 562 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 563 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 564 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2021-2025 (USD MILLION)
- TABLE 565 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY HARDWARE, 2026-2031 (USD MILLION)
- TABLE 566 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2021-2025 (USD MILLION)
- TABLE 567 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SOFTWARE, 2026-2031 (USD MILLION)
- TABLE 568 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 569 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 570 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 571 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 572 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 573 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 574 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 575 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 576 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 577 REST OF LATIN AMERICA: MARITIME SAFETY SYSTEM MARKET, BY OPERATING ENVIRONMENT, 2026-2031 (USD MILLION)
- TABLE 578 OVERVIEW OF STRATEGIES ADOPTED BY KEY MARITIME SAFETY SYSTEM VENDORS, 2021-2026
- TABLE 579 MARITIME SAFETY SYSTEM MARKET: DEGREE OF COMPETITION
- TABLE 580 MARITIME SAFETY SYSTEM MARKET: REGIONAL FOOTPRINT (11 PLAYERS)
- TABLE 581 MARITIME SAFETY SYSTEM MARKET: OFFERING FOOTPRINT (11 PLAYERS)
- TABLE 582 MARITIME SAFETY SYSTEM MARKET: APPLICATION FOOTPRINT (11 PLAYERS)
- TABLE 583 MARITIME SAFETY SYSTEM MARKET: OPERATING ENVIRONMENT FOOTPRINT (11 PLAYERS)
- TABLE 584 MARITIME SAFETY SYSTEM MARKET: REGIONAL FOOTPRINT (5 PLAYERS)
- TABLE 585 MARITIME SAFETY SYSTEM MARKET: OFFERING FOOTPRINT (5 PLAYERS)
- TABLE 586 MARITIME SAFETY SYSTEM MARKET: APPLICATION FOOTPRINT (5 PLAYERS)
- TABLE 587 MARITIME SAFETY SYSTEM MARKET: OPERATING ENVIRONMENT FOOTPRINT (5 PLAYERS)
- TABLE 588 MARITIME SAFETY SYSTEM MARKET: REGIONAL FOOTPRINT (19 PLAYERS)
- TABLE 589 MARITIME SAFETY SYSTEM MARKET: OFFERING FOOTPRINT (19 PLAYERS)
- TABLE 590 MARITIME SAFETY SYSTEM MARKET: APPLICATION FOOTPRINT (19 PLAYERS)
- TABLE 591 MARITIME SAFETY SYSTEM MARKET: OPERATING ENVIRONMENT FOOTPRINT (19 PLAYERS)
- TABLE 592 MARITIME SAFETY SYSTEM MARKET: PRODUCT LAUNCHES/ENHANCEMENTS, 2021-AUGUST 2026
- TABLE 593 MARITIME SAFETY SYSTEM MARKET: DEALS, 2021-AUGUST 2026
- TABLE 594 KONGSBERG MARITIME: COMPANY OVERVIEW
- TABLE 595 KONGSBERG MARITIME: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 596 KONGSBERG MARITIME: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 597 KONGSBERG MARITIME: DEALS
- TABLE 598 KONGSBERG MARITIME: OTHER DEVELOPMENTS
- TABLE 599 FURUNO ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 600 FURUNO ELECTRIC CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 601 FURUNO ELECTRIC CO., LTD.: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 602 MICROSOFT: DEALS
- TABLE 603 FURUNO ELECTRIC CO., LTD.: OTHER DEVELOPMENTS
- TABLE 604 JAPAN RADIO CO., LTD. (JRC): COMPANY OVERVIEW
- TABLE 605 JAPAN RADIO CO., LTD. (JRC): PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 606 JAPAN RADIO CO., LTD. (JRC): PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 607 JAPAN RADIO CO., LTD. (JRC): DEALS
- TABLE 608 NAVICO GROUP: COMPANY OVERVIEW
- TABLE 609 NAVICO GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 610 NAVICO GROUP: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 611 NAVICO GROUP: DEALS
- TABLE 612 GARMIN: COMPANY OVERVIEW
- TABLE 613 GARMIN MARINE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 614 GARMIN MARINE: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 615 GARMIN MARINE: DEALS
- TABLE 616 CONSILIUM SAFETY GROUP: COMPANY OVERVIEW
- TABLE 617 CONSILIUM SAFETY GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 618 CONSILIUM SAFETY GROUP: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 619 CONSILIUM SAFETY GROUP: DEALS
- TABLE 620 ANSCHUTZ: COMPANY OVERVIEW
- TABLE 621 ANSCHUTZ: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 622 ANSCHUTZ: DEALS
- TABLE 623 TOKYO KEIKI INC.: COMPANY OVERVIEW
- TABLE 624 TOKYO KEIKI INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 625 TOKYO KEIKI INC.: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 626 TOKYO KEIKI INC.: DEALS
- TABLE 627 TOKYO KEIKI INC.: OTHER DEVELOPMENTS
- TABLE 628 COBHAM SATCOM: COMPANY OVERVIEW
- TABLE 629 COBHAM SATCOM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 630 COBHAM SATCOM: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 631 COBHAM SATCOM: DEALS
- TABLE 632 COBHAM SATCOM: OTHER DEVELOPMENTS
- TABLE 633 SPERRY MARINE: COMPANY OVERVIEW
- TABLE 634 SPERRY MARINE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 635 SPERRY MARINE: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 636 SPERRY MARINE: DEALS
- TABLE 637 SPERRY MARINE: OTHER DEVELOPMENTS
- TABLE 638 M2INTELLIGENCE: COMPANY OVERVIEW
- TABLE 639 M2INTELLIGENCE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 640 M2INTELLIGENCE: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 641 FACTOR ANALYSIS
List of Figures
- FIGURE 1 MARKET SCENARIO
- FIGURE 2 MARITIME SAFETY SYSTEM MARKET, 2021-2031
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN MARITIME SAFETY SYSTEM MARKET, 2022-2026
- FIGURE 4 DISRUPTIONS INFLUENCING GROWTH OF MARITIME SAFETY SYSTEM MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS IN MARITIME SAFETY SYSTEM MARKET, 2026-2031
- FIGURE 6 EUROPE TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 7 LARGE SHIPPING FLEET, PORT INFRASTRUCTURE, AND DIGITALIZATION TO CREATE ATTRACTIVE MARKET OPPORTUNITIES
- FIGURE 8 ASIA PACIFIC TO EXHIBIT HIGHEST GROWTH RATE DURING FORECAST PERIOD
- FIGURE 9 SOFTWARE SEGMENT TO WITNESS HIGHEST GROWTH RATE DURING FORECAST PERIOD
- FIGURE 10 HARDWARE AND ONBOARD VESSEL SEGMENTS TO ACCOUNT FOR LARGEST MARKET SHARES IN ASIA PACIFIC IN 2026
- FIGURE 11 ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
- FIGURE 12 MARITIME SAFETY SYSTEM MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 13 EVOLUTION OF MARITIME SAFETY SYSTEM
- FIGURE 14 MARITIME SAFETY SYSTEM: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 MARITIME SAFETY SYSTEM MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 16 MARITIME SAFETY SYSTEM MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 COMPUTER PROCESSING UNITS EXPORT, BY KEY COUNTRY, 2018-2025 (USD BILLION)
- FIGURE 18 COMPUTER PROCESSING UNITS IMPORT, BY KEY COUNTRY, 2018-2025 (USD BILLION)
- FIGURE 19 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 20 LEADING MARITIME SAFETY SYSTEM STARTUPS, BY FUNDING VALUE (MILLION) AND FUNDING ROUND, UNTIL 2026
- FIGURE 21 MARITIME SAFETY PRODUCT ROADMAP, 2026-2031
- FIGURE 22 NUMBER OF PATENTS APPLIED AND GRANTED, 2016-2026
- FIGURE 23 REGIONAL ANALYSIS OF PATENTS GRANTED, 2016-2026
- FIGURE 24 MARITIME SAFETY SYSTEM MARKET: FUTURE APPLICATIONS
- FIGURE 25 MARITIME SAFETY SYSTEM MARKET: DECISION-MAKING FACTORS
- FIGURE 26 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE APPLICATIONS
- FIGURE 27 KEY BUYING CRITERIA FOR TOP THREE SAFETY APPLICATIONS
- FIGURE 28 MARITIME SAFETY SYSTEM MARKET: ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 29 SOFTWARE SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 30 NAVIGATION & POSITIONING EQUIPMENT SEGMENT TO LEAD MARKET FROM 2026 TO 2031
- FIGURE 31 NAVIGATION & COLLISION AVOIDANCE SOFTWARE SEGMENT TO LEAD MARKET FROM 2026 TO 2031
- FIGURE 32 PROFESSIONAL SERVICES SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 33 VESSEL & CREW SAFETY MONITORING SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 34 OFFSHORE INSTALLATION SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 35 ASIA PACIFIC TO LEAD MARKET FROM 2026 TO 2031
- FIGURE 36 UK TO WITNESS FASTEST GROWTH DURING FORECAST PERIOD
- FIGURE 37 EUROPE: MARITIME SAFETY SYSTEM MARKET SNAPSHOT
- FIGURE 38 ASIA PACIFIC: MARITIME SAFETY SYSTEM MARKET SNAPSHOT
- FIGURE 39 MARITIME SAFETY SYSTEM MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021-2025
- FIGURE 40 SHARE OF LEADING COMPANIES IN MARITIME SAFETY SYSTEM MARKET, 2025
- FIGURE 41 COMPARATIVE ANALYSIS OF MARITIME SAFETY SYSTEM PLATFORMS
- FIGURE 42 MARITIME SAFETY SYSTEM MARKET: COMPANY EVALUATION MATRIX (INTEGRATED NAVIGATION, COMMUNICATION, & VESSEL SAFETY SYSTEMS), 2025
- FIGURE 43 MARITIME SAFETY SYSTEM MARKET: COMPANY FOOTPRINT (14 PLAYERS)
- FIGURE 44 MARITIME SAFETY SYSTEM MARKET: COMPANY EVALUATION MATRIX (EMERGENCY, LIFE, & HAZARD SAFETY SYSTEMS), 2025
- FIGURE 45 MARITIME SAFETY SYSTEM MARKET: COMPANY FOOTPRINT (5 PLAYERS)
- FIGURE 46 MARITIME SAFETY SYSTEM MARKET: COMPANY EVALUATION MATRIX (INTELLIGENT & AUTONOMOUS MARITIME SAFETY SYSTEMS), 2025
- FIGURE 47 MARITIME SAFETY SYSTEM MARKET: COMPANY FOOTPRINT (19 PLAYERS)
- FIGURE 48 FINANCIAL METRICS OF KEY VENDORS
- FIGURE 49 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 50 KONGSBERG MARITIME: COMPANY SNAPSHOT
- FIGURE 51 FURUNO ELECTRIC CO., LTD.: COMPANY SNAPSHOT
- FIGURE 52 GARMIN MARINE: COMPANY SNAPSHOT
- FIGURE 53 TOKYO KEIKI INC.: COMPANY SNAPSHOT
- FIGURE 54 MARITIME SAFETY SYSTEM MARKET: RESEARCH DESIGN
- FIGURE 55 DATA TRIANGULATION
- FIGURE 56 MARITIME SAFETY SYSTEM MARKET: TOP-DOWN AND BOTTOM-UP APPROACHES
- FIGURE 57 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 1, BOTTOM-UP (SUPPLY-SIDE): REVENUE FROM SOFTWARE/SERVICES OF MARITIME SAFETY SYSTEM MARKET
- FIGURE 58 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 2, BOTTOM-UP (SUPPLY-SIDE): COLLECTIVE REVENUE FROM ALL HARDWARE/SOFTWARE/SERVICES OF MARITIME SAFETY SYSTEM MARKET
- FIGURE 59 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 3, BOTTOM-UP (SUPPLY-SIDE): COLLECTIVE REVENUE FROM ALL HARDWARE/SOFTWARE/ SERVICES OF MARITIME SAFETY SYSTEM MARKET
- FIGURE 60 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 3, BOTTOM-UP (DEMAND-SIDE): SHARE OF MARITIME SAFETY SYSTEM THROUGH OVERALL AI SPENDING

