PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2136424
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2136424
Edge AI Software Market by Offering, AI Workload, Edge Environment - Global Forecast to 2032
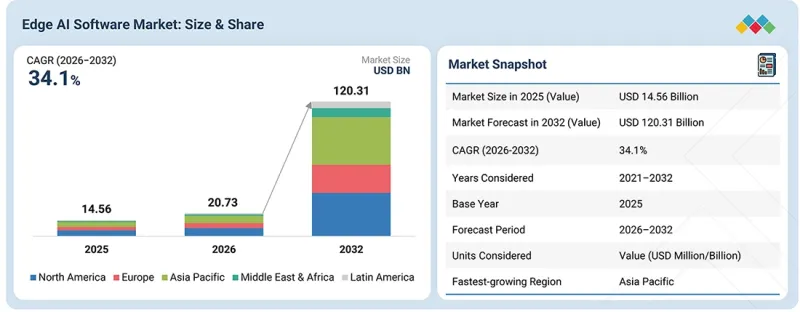
The global edge AI software market is estimated at USD 20.73 billion in 2026 and is projected to reach USD 120.31 billion by 2032, reflecting a 34.1% CAGR over the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Billion) |
| Segments | Offering, AI Workload, Edge Environment, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
Growth is supported by rising demand for low-latency AI execution, stronger control over enterprise and operational data, greater resilience in intermittently connected environments, and more efficient use of cloud infrastructure. At the same time, heterogeneous hardware environments, deployment complexity, model lifecycle requirements, and integration with legacy operational systems remain key constraints to large-scale adoption.
"Generative AI is emerging as the fastest-growing Edge AI workload as sophisticated models move closer to the point of execution"
Generative AI is expected to grow fastest within the AI workload segment as smaller foundation models, quantization, model compression, and optimized inference runtimes make local execution increasingly practical. The opportunity is moving beyond basic text generation toward local assistants, retrieval-enabled applications, natural-language interfaces, and autonomous software functions that can operate with reduced reliance on continuous cloud connectivity. Vendors that improve model efficiency, hardware portability, memory utilization, and integration with enterprise data are positioned to benefit as generative workloads extend across distributed environments.
"Device edge remains the largest environment as AI execution expands directly across intelligent endpoints"
The device edge environment is expected to account for the largest share of the market in 2026, supported by the growing ability of cameras, robots, vehicles, embedded systems, appliances, and other endpoints to run AI locally. The segment benefits from requirements for immediate decision-making, bandwidth efficiency, privacy, and operational continuity. As endpoint compute capabilities improve, demand is expanding from conventional computer vision and predictive workloads toward speech, multimodal, and generative AI. This increases the importance of lightweight runtimes, hardware-aware optimization, and software that can maintain performance across diverse processor architectures.
"North America leads current adoption, while Asia Pacific is positioned for the strongest expansion"
North America is expected to remain the largest regional market, supported by a concentration of hyperscalers, semiconductor vendors, Edge AI software companies, enterprise technology buyers, and mature AI infrastructure. The region also benefits from the early commercialization of distributed AI across both enterprise and device environments. Asia Pacific is expected to grow fastest, driven by large-scale electronics manufacturing, industrial automation, connected-device production, telecom infrastructure expansion, and growing enterprise AI investment across China, Japan, South Korea, India, and Southeast Asia. The region's combination of device manufacturing capacity and expanding domestic AI ecosystems provides a strong foundation for sustained Edge AI software adoption.
Breakdown of Primaries
In-depth interviews were conducted with chief executive officers (CEOs), innovation and technology directors, system integrators, and executives from key organizations operating in the edge AI software market.
- By Company: Tier 1 - 24%, Tier 2 - 41%, and Tier 3 - 35%
- By Designation: Directors - 31%, Managers - 46%, and Others - 23%
- By Region: North America - 42%, Europe - 21%, Asia Pacific - 25%, Middle East & Africa - 4%, and Latin America - 8%
Key players profiled in the edge AI software market include AWS (US), Microsoft (US), Google (US), IBM (US), Dell Technologies (US), Siemens (Germany), Schneider Electric (France), Intel (US), Red Hat (US), SAS (US), Nutanix (US), Viso.ai (Switzerland), ClearBlade (US), Litmus (US), Honeywell (US), Plumerai (UK), Edge Impulse (US), Latent AI (US), Imagimob (Sweden), SensiML (US), Nota AI (South Korea), Aizip (US), MicroAI (US), Axelera AI (Netherlands), MathWorks (US), Roboflow (US), Picovoice (Canada), Wallaroo.AI (US), ZEDEDA (US), Barbara (Spain), Ekkono (Sweden), Accenture (Ireland), Capgemini (France), HCLTech (India), NTT DATA (Japan), Tata Elxsi (India), Tata Consultancy Services (India), Infosys (India), Wipro (India), eInfochips (US), and Bosch Global Software Technologies (India).
The study includes an in-depth competitive analysis of these key players in the edge AI software market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the edge AI Software market by offering (software and services), by AI workload (computer vision, speech & audio AI, NLP, predictive & analytical AI, generative AI, and multimodal AI), by edge environment (device edge, enterprise/on-premises edge, and network/telecom edge), by end-user (manufacturing, healthcare & life sciences, energy & utilities, telecommunications, retail, automotive, transportation & logistics, smart cities, BFSI, consumer electronics & devices, and other end users), and by region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America). The scope of the report covers detailed information on the major factors, such as drivers, restraints, challenges, and opportunities, that influence the growth of the Edge AI Software market. A detailed analysis of key industry players has been conducted to provide insights into their business overview, solutions, and services; key strategies; contracts, partnerships, and agreements; new product & service launches; mergers and acquisitions; and recent developments associated with the Edge AI Software market. The report also covers competitive analysis of upcoming startups in the Edge AI Software market ecosystem.
Reasons to Buy This Report
The report will provide market leaders and new entrants with the closest available estimates of revenue for the overall edge AI software market and its subsegments. It will help stakeholders understand the competitive landscape and gain insights to position their business more effectively and plan suitable go-to-market strategies. It will also help stakeholders gauge the market's pulse and provide information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Rising demand for low-latency and real-time AI processing; growing need for data privacy, sovereignty, and local decision-making; proliferation of AI-capable edge devices and distributed infrastructure; increasing deployment of computer vision, generative AI, and multimodal workloads at the edge), restraints (Hardware fragmentation and lack of standardized edge AI environments; high deployment and integration complexity across heterogeneous edge estates), opportunities (Growing adoption of on-device generative and multimodal AI; expansion of Edge AI applications and autonomous systems; increasing demand for centralized deployment, lifecycle management, and observability across distributed AI fleets), and challenges (Optimizing increasingly complex AI models for constrained compute, memory, and power environments; and maintaining security, reliability, and model performance across large-scale distributed deployments)
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and new product & service launches in the edge AI software market
- Market Development: Comprehensive information about lucrative markets - analysis of the edge AI software market across varied regions
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the edge AI software market
- Competitive Assessment: In-depth assessment of market share, growth strategies, and product portfolios of AWS (US), Microsoft (US), Accenture (Ireland), Dell Technologies (US), Google (US), Capgemini (France), IBM (US), Siemens (Germany), Red Hat (US), and NTT Data (Japan), among others, in the edge AI software market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 OBJECTIVES OF THE STUDY
- 1.2 MARKET DEFINITION
- 1.2.1 INCLUSIONS AND EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 YEARS CONSIDERED FOR THE STUDY
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN EDGE AI SOFTWARE MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES IN EDGE AI SOFTWARE MARKET
- 3.2 EDGE AI SOFTWARE MARKET, BY REGION
- 3.3 EDGE AI SOFTWARE MARKET: TOP THREE AI WORKLOADS
- 3.4 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising Need for Real-time, Low-latency Inference at the Point of Action
- 4.2.1.2 Growing Requirement for Localized Processing to Improve Privacy, Resilience, and Data Control
- 4.2.1.3 Expanding Use of Visual Intelligence, Automation, Monitoring, and Predictive Analytics Across Physical Operations
- 4.2.1.4 Proliferation of Connected Assets, 5G, IoT, and Distributed Computing Ecosystems
- 4.2.2 RESTRAINTS
- 4.2.2.1 High Complexity of Deploying and Managing AI Across Heterogeneous Edge Infrastructure
- 4.2.2.2 Limited Interoperability Across AI Frameworks, Edge Platforms, Devices, and Enterprise Systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Deployment of Generative AI and Small Language Models at the Edge
- 4.2.3.2 Expansion of Edge MLOps, Orchestration, and Lifecycle Management Platforms
- 4.2.3.3 Growth of Privacy-preserving and Decentralized Edge AI Architectures
- 4.2.4 CHALLENGES
- 4.2.4.1 Maintaining Consistent Model Accuracy, Performance, and Reliability Across Distributed Edge Environments
- 4.2.4.2 Managing Model Updates, Version Control, Drift, Security, and Governance Over Long Edge Lifecycles
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN THE EDGE AI SOFTWARE MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN THE GLOBAL EDGE COMPUTING INDUSTRY
- 5.2.4 TRENDS IN THE GLOBAL ARTIFICIAL INTELLIGENCE INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 ENTERPRISE EDGE AI SOLUTION VENDORS
- 5.4.2 EDGE AI DEVELOPMENT PLATFORM VENDORS
- 5.4.3 EDGE AI SERVICE PROVIDERS
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICING ANALYSIS, BY OFFERING, 2026
- 5.5.2 INDICATIVE PRICING ANALYSIS, BY EDGE AI ENVIRONMENT, 2026
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 PROCTER & GAMBLE SCALES EDGE-TO-CLOUD AI OPERATIONS WITH MICROSOFT
- 5.9.2 COLES GROUP USES EDGE INFRASTRUCTURE AND AI TO MODERNIZE STORE OPERATIONS
- 5.9.3 DILIGENT ROBOTICS USES AWS EDGE AND AI SERVICES TO SCALE MOXI HOSPITAL ROBOTS
- 5.9.4 D.M. BOWMAN USES NETRADYNE EDGE AI TO IMPROVE FLEET SAFETY
- 5.9.5 SOUTHERN MINNESOTA BEET SUGAR COOPERATIVE AUTOMATES LOAD INSPECTION
- 5.10 IMPACT OF 2025-2026 US TARIFFS - EDGE AI SOFTWARE MARKET
- 5.10.1 INTRODUCTION
- 5.10.1.1 Tariff/Trade Policy Updates
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.3.1 Strategic Shifts and Emerging Trends
- 5.10.4 IMPACT ON COUNTRY/REGION
- 5.10.4.1 US
- 5.10.4.2 China
- 5.10.4.3 Europe
- 5.10.4.4 Asia Pacific (Excluding China)
- 5.10.5 IMPACT ON END-USE INDUSTRIES
- 5.10.1 INTRODUCTION
6 TECHNOLOGICAL ADVANCEMENTS, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 EDGE-OPTIMIZED FOUNDATION MODELS
- 6.1.2 MULTIMODAL AI
- 6.1.3 FEDERATED LEARNING
- 6.1.4 TINYML
- 6.1.5 MODEL COMPRESSION, QUANTIZATION, AND PRUNING
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 CLOUD AND HYBRID CLOUD COMPUTING
- 6.2.2 5G, PRIVATE 5G, AND MULTI-ACCESS EDGE COMPUTING
- 6.2.3 IOT/IIOT
- 6.2.4 CONTAINERIZATION AND EDGE ORCHESTRATION
- 6.2.5 CONFIDENTIAL COMPUTING AND ZERO-TRUST SECURITY
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 EDGE COMPUTING
- 6.3.2 COMPUTER VISION
- 6.3.3 ROBOTICS AND AUTONOMOUS SYSTEMS
- 6.3.4 REAL-TIME AND STREAMING ANALYTICS
- 6.3.5 DIGITAL TWINS
- 6.4 TECHNOLOGY ROADMAP
- 6.5 PATENT ANALYSIS
- 6.5.1 METHODOLOGY
- 6.5.2 PATENTS FILED, BY DOCUMENT TYPE, 2016-2026
- 6.5.3 INNOVATION AND PATENT APPLICATIONS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AUTONOMOUS INDUSTRIAL OPERATIONS
- 6.6.2 COOPERATIVE AUTONOMOUS MOBILITY
- 6.6.3 REAL-TIME MULTIMODAL HEALTHCARE AT THE POINT OF CARE
- 6.6.4 SELF-OPTIMIZING TELECOM AND CRITICAL INFRASTRUCTURE
- 6.6.5 HYPER-PERSONALIZED ON-DEVICE DIGITAL EXPERIENCES
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.1.1 North America
- 7.1.1.1.1 Executive Order 14179 and the US AI Governance Framework (US)
- 7.1.1.1.2 PIPEDA and the Voluntary Code of Conduct for Advanced Generative AI Systems (Canada)
- 7.1.1.2 Europe
- 7.1.1.2.1 Pro-innovation AI Regulatory Framework and Data Protection Law (UK)
- 7.1.1.2.2 EU AI Act and German AI Market-surveillance Implementation (Germany)
- 7.1.1.2.3 EU AI Act, GDPR, and CNIL AI Guidance (France)
- 7.1.1.2.4 EU AI Act and Supervision by AESIA (Spain)
- 7.1.1.2.5 Law No. 132 of 2025 - Provisions and Delegations to Government Concerning Artificial Intelligence (Italy)
- 7.1.1.3 Asia Pacific
- 7.1.1.3.1 Regulations on Network Data Security Management and China's Data Governance Framework (China)
- 7.1.1.3.2 Act on the Protection of Personal Information and AI Guidelines for Business v1.2 (Japan)
- 7.1.1.3.3 Digital Personal Data Protection Act, 2023 and Digital Personal Data Protection Rules, 2025 (India)
- 7.1.1.3.4 Framework Act on the Development of AI and Establishment of a Foundation for Trustworthiness (South Korea)
- 7.1.1.3.5 Guide on AI Governance and Ethics and Expanded Generative AI Guide (ASEAN)
- 7.1.1.4 Middle East & Africa
- 7.1.1.4.1 Personal Data Protection Law and SDAIA AI Ethics Principles (Saudi Arabia)
- 7.1.1.4.2 Protection of Personal Information Act and Evolving National AI Policy (South Africa)
- 7.1.1.4.3 Federal Decree-law No. 45 of 2021 on the Protection of Personal Data (UAE)
- 7.1.1.5 Latin America
- 7.1.1.5.1 LGPD and ANPD Regulatory Sandbox for AI and Data Protection (Brazil)
- 7.1.1.5.2 Federal Law on Protection of Personal Data Held by Private Parties, 2025 (Mexico)
- 7.1.1.1 North America
- 7.1.2 INDUSTRY STANDARDS
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS INDUSTRY VERTICALS
9 EDGE AI SOFTWARE MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 DRIVERS: EDGE AI SOFTWARE MARKET, BY OFFERING
- 9.2 SOFTWARE
- 9.2.1 EDGE AI DEVELOPMENT PLATFORMS
- 9.2.1.1 Model-to-device tool chains to become control point for faster Edge AI product development
- 9.2.2 EDGE AI RUNTIME & INFERENCE SOFTWARE
- 9.2.2.1 Runtime optimization to evolve from performance utility into strategic software layer for heterogeneous edge fleets
- 9.2.3 EDGE AI DEPLOYMENT & LIFECYCLE MANAGEMENT PLATFORMS
- 9.2.3.1 Fleet-scale model operations make deployment, observability, and update control distinct buying requirements
- 9.2.4 EDGE AI APPLICATIONS
- 9.2.4.1 Packaged edge applications shift spending from experimentation toward repeatable operational outcomes
- 9.2.1 EDGE AI DEVELOPMENT PLATFORMS
- 9.3 SERVICES
- 9.3.1 CONSULTING & ADVISORY SERVICES
- 9.3.1.1 Architecture and use-case prioritization to prove decisive as enterprises move beyond isolated Edge AI pilots
- 9.3.2 SOLUTION DEVELOPMENT & INTEGRATION SERVICES
- 9.3.2.1 Rising integration demand as Edge AI connects models with operational systems, sensors, and enterprise applications
- 9.3.3 DEPLOYMENT & IMPLEMENTATION SERVICES
- 9.3.3.1 Production rollouts to drive demand for disciplined site readiness, validation, security hardening, and rollout management
- 9.3.4 MANAGED SERVICES
- 9.3.4.1 Distributed AI estates create recurring services market around uptime, model health, security, and continuous optimization
- 9.3.1 CONSULTING & ADVISORY SERVICES
10 EDGE AI SOFTWARE MARKET, BY AI WORKLOAD
- 10.1 INTRODUCTION
- 10.1.1 DRIVERS: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD
- 10.2 COMPUTER VISION
- 10.2.1 COMPUTER VISION TO REMAIN ANCHOR WORKLOAD AS ENTERPRISES PRIORITIZE REAL-TIME PERCEPTION WITHOUT CLOUD STREAMING
- 10.3 SPEECH & AUDIO AI
- 10.3.1 ON-DEVICE SPEECH AND ACOUSTIC INTELLIGENCE GAIN VALUE WHERE PRIVACY, IMMEDIACY, AND CONTINUOUS LISTENING MATTER
- 10.4 NATURAL LANGUAGE PROCESSING
- 10.4.1 LOCAL NLP TO EXPAND FROM COMMAND RECOGNITION TO OPERATIONAL SEARCH AND HUMAN-MACHINE INTERACTION
- 10.5 PREDICTIVE & ANALYTICAL AI
- 10.5.1 TIME-SERIES PREDICTION & ANOMALY DETECTION EMBEDDED ACROSS INDUSTRIAL AND OPERATIONAL EDGE SYSTEMS
- 10.6 GENERATIVE AI
- 10.6.1 LOCAL INFERENCE STACKS TURN EDGE INTO NEW DEPLOYMENT TIER FOR PRIVATE, RESPONSIVE GENERATIVE AI
- 10.7 MULTIMODAL AI
- 10.7.1 MULTIMODAL MODELS TO BECOME INTELLIGENCE LAYER LINKING SENSOR CONTEXT INTO RICHER EDGE DECISIONS
11 EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT
- 11.1 INTRODUCTION
- 11.1.1 DRIVERS: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT
- 11.2 DEVICE EDGE
- 11.2.1 AI MOVES DIRECTLY INTO ENDPOINTS AS COMPACT MODELS MAKE LOCAL PERCEPTION AND DECISION-MAKING PRACTICAL AT SCALE
- 11.3 ON-PREMISES EDGE
- 11.3.1 LOCAL SERVERS TO EMERGE AS PREFERRED AGGREGATION TIER FOR MULTI-DEVICE AI, PRIVATE INFERENCE, AND SITE-LEVEL AUTOMATION
- 11.4 NETWORK EDGE
- 11.4.1 AI-NATIVE NETWORK SOFTWARE TURNS TELCO INFRASTRUCTURE INTO BOTH OPTIMIZATION DOMAIN AND DISTRIBUTED INFERENCE PLATFORM
12 EDGE AI SOFTWARE MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.1.1 DRIVERS: EDGE AI SOFTWARE MARKET, BY END USER
- 12.2 MANUFACTURING
- 12.2.1 MANUFACTURING TO SHIFT EDGE AI FROM ISOLATED MACHINE VISION TOWARD PLANT-WIDE INTELLIGENCE
- 12.2.2 PREDICTIVE MAINTENANCE
- 12.2.3 QUALITY INSPECTION
- 12.2.4 PROCESS & YIELD OPTIMIZATION
- 12.2.5 AUTONOMOUS ROBOTICS & INDUSTRIAL AUTOMATION
- 12.2.6 WORKER SAFETY & SITE MONITORING
- 12.2.7 OTHER MANUFACTURING USE CASES
- 12.3 HEALTHCARE & LIFE SCIENCES
- 12.3.1 HEALTHCARE EDGE AI EXPANDS CLINICAL RESPONSIVENESS, PRIVACY, AND DEVICE-LEVEL INTELLIGENCE
- 12.3.2 REMOTE PATIENT MONITORING
- 12.3.3 MEDICAL IMAGING & DIAGNOSTICS
- 12.3.4 SMART MEDICAL DEVICES & WEARABLES
- 12.3.5 REAL-TIME PATIENT & CLINICAL MONITORING
- 12.3.6 ASSISTED SURGERY & CLINICAL PROCEDURES
- 12.3.7 OTHER HEALTHCARE & LIFE SCIENCES USE CASES
- 12.4 ENERGY & UTILITIES
- 12.4.1 UTILITIES ADOPT EDGE AI TO MAKE DISTRIBUTED ASSETS MORE OBSERVABLE AND AUTONOMOUS
- 12.4.2 ASSET MONITORING & PREDICTIVE MAINTENANCE
- 12.4.3 GRID MONITORING & FAULT DETECTION
- 12.4.4 SMART GRID & SUBSTATION INTELLIGENCE
- 12.4.5 DISTRIBUTED ENERGY RESOURCE OPTIMIZATION
- 12.4.6 ENERGY DISTRIBUTION AUTOMATION
- 12.4.7 OTHER ENERGY & UTILITIES USE CASES
- 12.5 TELECOMMUNICATIONS
- 12.5.1 TELCO OPERATORS TO APPLY AI INSIDE NETWORKS WHILE EXPOSING DISTRIBUTED INFRASTRUCTURE FOR NEW AI SERVICES
- 12.5.2 REAL-TIME NETWORK MONITORING & ANOMALY DETECTION
- 12.5.3 RAN & NETWORK OPTIMIZATION
- 12.5.4 NETWORK SECURITY & THREAT DETECTION
- 12.5.5 PREDICTIVE NETWORK MAINTENANCE
- 12.5.6 TRAFFIC & SERVICE QUALITY OPTIMIZATION
- 12.5.7 OTHER TELECOMMUNICATION USE CASES
- 12.6 RETAIL & E-COMMERCE
- 12.6.1 RETAIL EDGE AI: FROM ISOLATED VIDEO ANALYTICS TOWARD INTEGRATED STORE INTELLIGENCE
- 12.6.2 IN-STORE ANALYTICS
- 12.6.3 SMART & AUTONOMOUS CHECKOUT
- 12.6.4 INVENTORY & SHELF MONITORING
- 12.6.5 LOSS PREVENTION & THEFT DETECTION
- 12.6.6 CUSTOMER BEHAVIOR & PERSONALIZATION
- 12.6.7 OTHER RETAIL USE CASES
- 12.7 AUTOMOTIVE
- 12.7.1 AUTOMOTIVE EDGE AI TO BECOME CORE SOFTWARE LAYER AS VEHICLES COMBINE SAFETY AND LOCAL GENERATIVE INTERACTION
- 12.7.2 AUTONOMOUS & SEMI-AUTONOMOUS DRIVING
- 12.7.3 ADAS
- 12.7.4 DRIVER & OCCUPANT MONITORING
- 12.7.5 IN-VEHICLE AI ASSISTANTS & INFOTAINMENT
- 12.7.6 VEHICLE HEALTH & PREDICTIVE MAINTENANCE
- 12.7.7 OTHER AUTOMOTIVE USE CASES
- 12.8 TRANSPORTATION & LOGISTICS
- 12.8.1 TRANSPORTATION AND LOGISTICS OPERATORS TURN TO EDGE AI TO COORDINATE MOVING ASSETS AND AUTOMATE FACILITIES
- 12.8.2 FLEET MONITORING & MANAGEMENT
- 12.8.3 ROUTE & TRAFFIC OPTIMIZATION
- 12.8.4 WAREHOUSE & LOGISTICS AUTOMATION
- 12.8.5 CARGO & CONDITION MONITORING
- 12.8.6 AUTONOMOUS TRANSPORTATION SYSTEMS
- 12.8.7 OTHER TRANSPORTATION & LOGISTICS USE CASES
- 12.9 SMART CITIES
- 12.9.1 SMART-CITY EDGE AI ADVANCES TOWARD DISTRIBUTED URBAN INTELLIGENCE COORDINATED ACROSS CITY SYSTEMS
- 12.9.2 INTELLIGENT TRAFFIC MANAGEMENT
- 12.9.3 PUBLIC SAFETY & SURVEILLANCE
- 12.9.4 EMERGENCY RESPONSE & INCIDENT DETECTION
- 12.9.5 ENVIRONMENTAL MONITORING
- 12.9.6 SMART INFRASTRUCTURE & MUNICIPAL OPERATIONS
- 12.9.7 OTHER SMART CITY USE CASES
- 12.10 BFSI
- 12.10.1 BFSI EDGE AI TO CONCENTRATE ON TRANSACTION-TIME RISK, IDENTITY, AND BRANCH INTELLIGENCE
- 12.10.2 REAL-TIME FRAUD DETECTION
- 12.10.3 BIOMETRIC AUTHENTICATION & IDENTITY VERIFICATION
- 12.10.4 ATM & SELF-SERVICE BANKING INTELLIGENCE
- 12.10.5 BRANCH SECURITY & VIDEO ANALYTICS
- 12.10.6 PAYMENT RISK & TRANSACTION AUTHENTICATION
- 12.10.7 OTHER BFSI USE CASES
- 12.11 CONSUMER ELECTRONICS & DEVICES
- 12.11.1 CONSUMER EDGE AI EVOLVES FROM ISOLATED SMART FEATURES TOWARD PERSISTENT ON-DEVICE INTELLIGENCE
- 12.11.2 ON-DEVICE AI ASSISTANTS
- 12.11.3 COMPUTATIONAL PHOTOGRAPHY & VIDEO
- 12.11.4 BIOMETRIC AUTHENTICATION
- 12.11.5 SMART HOME & DEVICE AUTOMATION
- 12.11.6 AR/VR & SPATIAL INTELLIGENCE
- 12.11.7 OTHER CONSUMER ELECTRONICS & DEVICES USE CASES
- 12.12 OTHER END USERS
13 EDGE AI SOFTWARE MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 NORTH AMERICA: EDGE AI SOFTWARE MARKET DRIVERS
- 13.2.2 US
- 13.2.2.1 Industrial AI depth and domestic compute investment anchor US leadership in commercial Edge AI deployment
- 13.2.3 CANADA
- 13.2.3.1 Canada's Edge AI research depth and compute-access funding extend Edge AI into remote, resource-intensive industries
- 13.3 EUROPE
- 13.3.1 EUROPE: EDGE AI SOFTWARE MARKET DRIVERS
- 13.3.2 UK
- 13.3.2.1 Edge computing research, AI hardware policy, and advanced services to strengthen UK's commercial Edge AI base
- 13.3.3 GERMANY
- 13.3.3.1 Industry 4.0 pivot to industrial AI to favor factory-floor inference and lifecycle software
- 13.3.4 FRANCE
- 13.3.4.1 Nationwide AI diffusion and industrial AI policy to carry French enterprise AI into operational environments
- 13.3.5 ITALY
- 13.3.5.1 Italy's manufacturing depth and EU-backed AI infrastructure open pragmatic path to industrial Edge AI
- 13.3.6 SPAIN
- 13.3.6.1 Public AI investment and wide 5G reach to strengthen Spain's foundation for Edge AI adoption
- 13.3.7 REST OF EUROPE
- 13.4 ASIA PACIFIC
- 13.4.1 ASIA PACIFIC: EDGE AI SOFTWARE MARKET DRIVERS
- 13.4.2 CHINA
- 13.4.2.1 Industrial 5G and cloud-network-edge coordination to embed local inference in China's smart manufacturing architecture
- 13.4.3 INDIA
- 13.4.3.1 India's 5G scale, AI mission, and manufacturing push widen addressable base for Edge AI software
- 13.4.4 JAPAN
- 13.4.4.1 Physical AI and robotics strategy to steer Japanese Edge AI toward multimodal autonomous systems
- 13.4.5 SOUTH KOREA
- 13.4.5.1 AI factory targets and M.AX industrial clusters build policy-backed demand for edge inference and orchestration
- 13.4.6 ASEAN
- 13.4.6.1 Manufacturing diversification and national AI programs drive multi-speed but fast-expanding ASEAN Edge AI market
- 13.4.7 REST OF ASIA PACIFIC
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET DRIVERS
- 13.5.2 SAUDI ARABIA
- 13.5.2.1 National AI push and private 5G to generate high-value Edge AI demand across smart cities, energy, and industrial assets
- 13.5.3 UAE
- 13.5.3.1 Sovereign compute, advanced 5G, and AI-native government agenda accelerate hybrid Edge AI deployment
- 13.5.4 SOUTH AFRICA
- 13.5.4.1 Mining, energy, and telecom needs sustain selective Edge AI opportunities despite uneven adoption
- 13.5.5 REST OF MIDDLE EAST & AFRICA
- 13.6 LATIN AMERICA
- 13.6.1 LATIN AMERICA: EDGE AI SOFTWARE MARKET DRIVERS
- 13.6.2 BRAZIL
- 13.6.2.1 5G scale, industrial digitization, and telecom AI policy to push Edge AI beyond pilot-stage deployments
- 13.6.3 MEXICO
- 13.6.3.1 Nearshoring and dedicated smart-network spectrum to align connectivity investment with factory-floor AI
- 13.6.4 REST OF LATIN AMERICA
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER STRATEGIES, 2025-2026
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.4.1 MARKET RANKING ANALYSIS, 2025
- 14.5 PRODUCT COMPARATIVE ANALYSIS
- 14.5.1 PRODUCT COMPARATIVE ANALYSIS OF EDGE AI DEVELOPMENT PLATFORMS
- 14.5.2 PRODUCT COMPARATIVE ANALYSIS OF ENTERPRISE EDGE AI SOLUTIONS
- 14.6 COMPANY EVALUATION MATRIX: EDGE AI DEVELOPMENT PLATFORM VENDORS
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: EDGE AI DEVELOPMENT PLATFORM VENDORS, 2025
- 14.6.5.1 Company Footprint (Edge AI Development Platform Vendors)
- 14.6.5.2 Regional Footprint (Edge AI Development Platform Vendors)
- 14.6.5.3 Offering Footprint (Edge AI Development Platform Vendors)
- 14.6.5.4 AI Workload Footprint (Edge AI Development Platform Vendors)
- 14.6.5.5 Edge Environment Footprint (Edge AI Development Platform Vendors)
- 14.6.5.6 End User Footprint (Edge AI Development Platform Vendors)
- 14.7 COMPANY EVALUATION MATRIX: ENTERPRISE EDGE AI SOLUTION VENDORS
- 14.7.1 STARS
- 14.7.2 EMERGING LEADERS
- 14.7.3 PERVASIVE PLAYERS
- 14.7.4 PARTICIPANTS
- 14.7.5 COMPANY FOOTPRINT: ENTERPRISE EDGE AI SOLUTION VENDORS, 2025
- 14.7.5.1 Company Footprint (Enterprise Edge AI Solution Vendors)
- 14.7.5.2 Regional Footprint (Enterprise Edge AI Solution Vendors)
- 14.7.5.3 Offering Footprint (Enterprise Edge AI Solution Vendors)
- 14.7.5.4 AI Workload Footprint (Enterprise Edge AI Solution Vendors)
- 14.7.5.5 Edge Environment Footprint (Enterprise Edge AI Solution Vendors)
- 14.7.5.6 End User Footprint (Enterprise Edge AI Solution Vendors)
- 14.8 COMPANY EVALUATION MATRIX: EDGE AI SERVICE PROVIDERS
- 14.8.1 STARS
- 14.8.2 EMERGING LEADERS
- 14.8.3 PERVASIVE PLAYERS
- 14.8.4 PARTICIPANTS
- 14.8.5 COMPANY FOOTPRINT: EDGE AI SOFTWARE SERVICE PROVIDERS, 2025
- 14.8.5.1 Company Footprint (Edge AI Service Providers)
- 14.8.5.2 Regional Footprint (Edge AI Service Providers)
- 14.8.5.3 Offering Footprint (Edge AI Service Providers)
- 14.8.5.4 AI Workload Footprint (Edge AI Service Providers)
- 14.8.5.5 Edge Environment Footprint (Edge AI Service Providers)
- 14.8.5.6 End User Footprint (Edge AI Service Providers)
- 14.9 COMPANY VALUATION AND FINANCIAL METRICS
- 14.10 COMPETITIVE SCENARIO
- 14.10.1 PRODUCT LAUNCHES AND ENHANCEMENTS
- 14.10.2 DEALS
15 COMPANY PROFILES
- 15.1 INTRODUCTION
- 15.2 ENTERPRISE EDGE AI SOLUTION VENDORS
- 15.2.1 AWS
- 15.2.1.1 Business overview
- 15.2.1.2 Products/Solutions/Services offered
- 15.2.1.3 Recent developments
- 15.2.1.3.1 Product launches & enhancements
- 15.2.1.3.2 Deals
- 15.2.1.4 MnM view
- 15.2.1.4.1 Key strengths
- 15.2.1.4.2 Strategic choices
- 15.2.1.4.3 Weaknesses and competitive threats
- 15.2.2 MICROSOFT
- 15.2.2.1 Business overview
- 15.2.2.2 Products/Solutions/Services offered
- 15.2.2.3 Recent developments
- 15.2.2.3.1 Product launches & enhancements
- 15.2.2.3.2 Deals
- 15.2.2.4 MnM view
- 15.2.2.4.1 Key strengths
- 15.2.2.4.2 Strategic choices
- 15.2.2.4.3 Weaknesses and competitive threats
- 15.2.3 GOOGLE
- 15.2.3.1 Business overview
- 15.2.3.2 Products/Solutions/Services offered
- 15.2.3.3 Recent developments
- 15.2.3.3.1 Product launches & enhancements
- 15.2.3.3.2 Deals
- 15.2.3.4 MnM view
- 15.2.3.4.1 Key strengths
- 15.2.3.4.2 Strategic choices
- 15.2.3.4.3 Weaknesses and competitive threats
- 15.2.4 IBM
- 15.2.4.1 Business overview
- 15.2.4.2 Products/Solutions/Services offered
- 15.2.4.3 Recent developments
- 15.2.4.3.1 Product launches & enhancements
- 15.2.4.3.2 Deals
- 15.2.4.4 MnM view
- 15.2.4.4.1 Key strengths
- 15.2.4.4.2 Strategic choices
- 15.2.4.4.3 Weaknesses and competitive threats
- 15.2.5 DELL TECHNOLOGIES
- 15.2.5.1 Business overview
- 15.2.5.2 Products/Solutions/Services offered
- 15.2.5.3 Recent developments
- 15.2.5.3.1 Product launches & enhancements
- 15.2.5.3.2 Deals
- 15.2.5.4 MnM view
- 15.2.5.4.1 Key strengths
- 15.2.5.4.2 Strategic choices
- 15.2.5.4.3 Weaknesses and competitive threats
- 15.2.6 SIEMENS
- 15.2.6.1 Business overview
- 15.2.6.2 Products/Solutions/Services offered
- 15.2.6.3 Recent developments
- 15.2.6.3.1 Product launches & enhancements
- 15.2.6.3.2 Deals
- 15.2.6.4 MnM view
- 15.2.6.4.1 Key strengths
- 15.2.6.4.2 Strategic choices
- 15.2.6.4.3 Weaknesses and competitive threats
- 15.2.7 SCHNEIDER ELECTRIC
- 15.2.7.1 Business overview
- 15.2.7.2 Products/Solutions/Services offered
- 15.2.7.3 Recent developments
- 15.2.7.3.1 Product launches & enhancements
- 15.2.7.3.2 Deals
- 15.2.7.4 MnM view
- 15.2.7.4.1 Key strengths
- 15.2.7.4.2 Strategic choices
- 15.2.7.4.3 Weaknesses and competitive threats
- 15.2.8 NUTANIX
- 15.2.8.1 Business overview
- 15.2.8.2 Products/Solutions/Services offered
- 15.2.8.3 Recent developments
- 15.2.8.3.1 Product launches & enhancements
- 15.2.8.3.2 Deals
- 15.2.8.4 MnM view
- 15.2.8.4.1 Key strengths
- 15.2.8.4.2 Strategic choices
- 15.2.8.4.3 Weaknesses and competitive threats
- 15.2.9 RED HAT
- 15.2.10 SAS
- 15.2.11 INTEL
- 15.2.12 VISO.AI
- 15.2.13 CLEARBLADE
- 15.2.14 LITMUS
- 15.2.15 HONEYWELL
- 15.2.1 AWS
- 15.3 EDGE AI DEVELOPMENT PLATFORM VENDORS
- 15.3.1 AXELERA AI
- 15.3.1.1 Business overview
- 15.3.1.2 Products/Solutions/Services offered
- 15.3.1.3 Recent developments
- 15.3.1.3.1 Product launches & enhancements
- 15.3.1.3.2 Deals
- 15.3.1.4 MnM view
- 15.3.1.4.1 Key strengths
- 15.3.1.4.2 Strategic choices
- 15.3.1.4.3 Weaknesses and competitive threats
- 15.3.2 EDGE IMPULSE
- 15.3.3 LATENT AI
- 15.3.4 IMAGIMOB
- 15.3.5 SENSIML
- 15.3.6 NOTA AI
- 15.3.7 AIZIP
- 15.3.8 MICROAI
- 15.3.9 PLUMERAI
- 15.3.10 MATHWORKS
- 15.3.11 ROBOFLOW
- 15.3.12 PICOVOICE
- 15.3.13 WALLAROO.AI
- 15.3.14 ZEDEDA
- 15.3.15 BARBARA
- 15.3.16 EKKONO
- 15.3.1 AXELERA AI
- 15.4 EDGE AI SERVICES PROVIDERS
- 15.4.1 ACCENTURE
- 15.4.1.1 Business overview
- 15.4.1.2 Products/Solutions/Services offered
- 15.4.1.3 Recent developments
- 15.4.1.3.1 Product launches & enhancements
- 15.4.1.3.2 Deals
- 15.4.1.4 MnM view
- 15.4.1.4.1 Key strengths
- 15.4.1.4.2 Strategic choices
- 15.4.1.4.3 Weaknesses and competitive threats
- 15.4.2 CAPGEMINI
- 15.4.3 HCLTECH
- 15.4.4 NTT DATA
- 15.4.5 TATA ELXSI
- 15.4.6 TATA CONSULTANCY SERVICES (TCS)
- 15.4.7 INFOSYS
- 15.4.8 WIPRO
- 15.4.9 EINFOCHIPS
- 15.4.10 BOSCH GLOBAL SOFTWARE TECHNOLOGIES
- 15.4.1 ACCENTURE
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Breakup of primary profiles
- 16.1.2.2 Key industry insights
- 16.2 MARKET BREAKUP AND DATA TRIANGULATION
- 16.3 MARKET SIZE ESTIMATION
- 16.3.1 TOP-DOWN APPROACH
- 16.3.2 BOTTOM-UP APPROACH
- 16.4 MARKET FORECAST
- 16.5 RESEARCH ASSUMPTIONS
- 16.6 LIMITATIONS OF THE STUDY
17 ADJACENT AND RELATED MARKETS
- 17.1 INTRODUCTION
- 17.2 ARTIFICIAL INTELLIGENCE (AI) MARKET - GLOBAL FORECAST TO 2033
- 17.2.1 MARKET DEFINITION
- 17.2.2 MARKET OVERVIEW
- 17.2.2.1 Artificial Intelligence Market, By Offering
- 17.2.2.2 Artificial Intelligence Market, By Technology
- 17.2.2.3 Artificial Intelligence Market, By Business Function
- 17.3 EDGE COMPUTING MARKET - GLOBAL FORECAST TO 2031
- 17.3.1 MARKET DEFINITION
- 17.3.2 MARKET OVERVIEW
- 17.3.2.1 Edge Computing Market, By Offering
- 17.3.2.2 Edge Computing Market, By Application
- 17.3.2.3 Edge Computing Market, By Vertical
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS
List of Tables
- TABLE 1 EDGE AI SOFTWARE MARKET: DETAILED SEGMENTATION
- TABLE 2 UNITED STATES DOLLAR EXCHANGE RATE, 2021-2025
- TABLE 3 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- TABLE 4 IMPACT OF PORTER'S FIVE FORCES ON THE EDGE AI SOFTWARE MARKET
- TABLE 5 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2026-2030
- TABLE 6 EDGE AI SOFTWARE MARKET: ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 7 INDICATIVE PRICING ANALYSIS, BY OFFERING, 2026
- TABLE 8 INDICATIVE PRICING ANALYSIS, BY EDGE AI ENVIRONMENT, 2026
- TABLE 9 EDGE AI SOFTWARE MARKET: LIST OF CONFERENCES AND EVENTS, 2026-2027
- TABLE 10 TARIFF/TRADE POLICY UPDATES, JUNE 2026-SEPTEMBER 2026
- TABLE 11 CURRENT BROAD US TARIFF RATES, BY COUNTRY
- TABLE 12 PATENTS FILED, 2016-2026
- TABLE 13 LIST OF TOP PATENTS IN EDGE AI SOFTWARE MARKET, 2026
- TABLE 14 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 15 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 16 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 17 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 LATIN AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 GLOBAL INDUSTRY STANDARDS FOR EDGE AI SOFTWARE
- TABLE 20 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE VERTICALS
- TABLE 21 KEY BUYING CRITERIA FOR TOP THREE END USERS
- TABLE 22 UNMET NEEDS IN THE EDGE AI SOFTWARE MARKET BY END-USE INDUSTRIES
- TABLE 23 EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 24 EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 25 EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 26 EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 27 SOFTWARE: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 28 SOFTWARE: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 29 EDGE AI DEVELOPMENT PLATFORMS: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 30 EDGE AI DEVELOPMENT PLATFORMS: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 31 EDGE AI RUNTIME & INFERENCE SOFTWARE: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 32 EDGE AI RUNTIME & INFERENCE SOFTWARE: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 33 EDGE AI DEPLOYMENT & LIFECYCLE MANAGEMENT PLATFORMS: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 34 EDGE AI DEPLOYMENT & LIFECYCLE MANAGEMENT PLATFORMS: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 35 EDGE AI APPLICATIONS: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 36 EDGE AI APPLICATIONS: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 37 EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 38 EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 39 SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 40 SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 41 CONSULTING & ADVISORY SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 42 CONSULTING & ADVISORY SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 43 SOLUTION DEVELOPMENT & INTEGRATION SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 44 SOLUTION DEVELOPMENT & INTEGRATION SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 45 DEPLOYMENT & IMPLEMENTATION SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 46 DEPLOYMENT & IMPLEMENTATION SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 47 MANAGED SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 48 MANAGED SERVICES: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 49 EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 50 EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 51 COMPUTER VISION: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 52 COMPUTER VISION: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 53 SPEECH & AUDIO AI: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 54 SPEECH & AUDIO AI: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 55 NATURAL LANGUAGE PROCESSING: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 56 NATURAL LANGUAGE PROCESSING: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 57 PREDICTIVE & ANALYTICAL AI: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 58 PREDICTIVE & ANALYTICAL AI: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 59 GENERATIVE AI: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 60 GENERATIVE AI: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 61 MULTIMODAL AI: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 62 MULTIMODAL AI: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 63 EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 64 EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 65 DEVICE EDGE ENVIRONMENT: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 66 DEVICE EDGE ENVIRONMENT: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 67 ON-PREMISES EDGE ENVIRONMENT: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 68 ON-PREMISES EDGE ENVIRONMENT: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 69 NETWORK EDGE ENVIRONMENT: EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 70 NETWORK EDGE ENVIRONMENT: EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 71 EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 72 EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 73 EDGE AI SOFTWARE MARKET IN MANUFACTURING, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 74 EDGE AI SOFTWARE MARKET IN MANUFACTURING, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 75 EDGE AI SOFTWARE MARKET IN MANUFACTURING, BY REGION, 2021-2025 (USD MILLION)
- TABLE 76 EDGE AI SOFTWARE MARKET IN MANUFACTURING, BY REGION, 2026-2032 (USD MILLION)
- TABLE 77 EDGE AI SOFTWARE MARKET IN HEALTHCARE & LIFE SCIENCES, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 78 EDGE AI SOFTWARE MARKET IN HEALTHCARE & LIFE SCIENCES, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 79 EDGE AI SOFTWARE MARKET IN HEALTHCARE & LIFE SCIENCES, BY REGION, 2021-2025 (USD MILLION)
- TABLE 80 EDGE AI SOFTWARE MARKET IN HEALTHCARE & LIFE SCIENCES, BY REGION, 2026-2032 (USD MILLION)
- TABLE 81 EDGE AI SOFTWARE MARKET IN ENERGY & UTILITIES, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 82 EDGE AI SOFTWARE MARKET IN ENERGY & UTILITIES, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 83 EDGE AI SOFTWARE MARKET IN ENERGY & UTILITIES, BY REGION, 2021-2025 (USD MILLION)
- TABLE 84 EDGE AI SOFTWARE MARKET IN ENERGY & UTILITIES, BY REGION, 2026-2032 (USD MILLION)
- TABLE 85 EDGE AI SOFTWARE MARKET IN TELECOM, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 86 EDGE AI SOFTWARE MARKET IN TELECOM, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 87 EDGE AI SOFTWARE MARKET IN TELECOMMUNICATIONS, BY REGION, 2021-2025 (USD MILLION)
- TABLE 88 EDGE AI SOFTWARE MARKET IN TELECOMMUNICATIONS, BY REGION, 2026-2032 (USD MILLION)
- TABLE 89 EDGE AI SOFTWARE MARKET IN RETAIL & E-COMMERCE, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 90 EDGE AI SOFTWARE MARKET IN RETAIL & E-COMMERCE, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 91 EDGE AI SOFTWARE MARKET IN RETAIL & E-COMMERCE, BY REGION, 2021-2025 (USD MILLION)
- TABLE 92 EDGE AI SOFTWARE MARKET IN RETAIL & E-COMMERCE, BY REGION, 2026-2032 (USD MILLION)
- TABLE 93 EDGE AI SOFTWARE MARKET IN AUTOMOTIVE, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 94 EDGE AI SOFTWARE MARKET IN AUTOMOTIVE, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 95 EDGE AI SOFTWARE MARKET IN AUTOMOTIVE, BY REGION, 2021-2025 (USD MILLION)
- TABLE 96 EDGE AI SOFTWARE MARKET IN AUTOMOTIVE, BY REGION, 2026-2032 (USD MILLION)
- TABLE 97 EDGE AI SOFTWARE MARKET IN TRANSPORTATION & LOGISTICS, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 98 EDGE AI SOFTWARE MARKET IN TRANSPORTATION & LOGISTICS, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 99 EDGE AI SOFTWARE MARKET IN TRANSPORTATION & LOGISTICS, BY REGION, 2021-2025 (USD MILLION)
- TABLE 100 EDGE AI SOFTWARE MARKET IN TRANSPORTATION & LOGISTICS, BY REGION, 2026-2032 (USD MILLION)
- TABLE 101 EDGE AI SOFTWARE MARKET IN SMART CITIES, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 102 EDGE AI SOFTWARE MARKET IN SMART CITIES, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 103 EDGE AI SOFTWARE MARKET IN SMART CITIES, BY REGION, 2021-2025 (USD MILLION)
- TABLE 104 EDGE AI SOFTWARE MARKET IN SMART CITIES, BY REGION, 2026-2032 (USD MILLION)
- TABLE 105 EDGE AI SOFTWARE MARKET IN BFSI, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 106 EDGE AI SOFTWARE MARKET IN BFSI, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 107 EDGE AI SOFTWARE MARKET IN BFSI, BY REGION, 2021-2025 (USD MILLION)
- TABLE 108 EDGE AI SOFTWARE MARKET IN BFSI, BY REGION, 2026-2032 (USD MILLION)
- TABLE 109 EDGE AI SOFTWARE MARKET IN CONSUMER ELECTRONICS & DEVICES, BY USE CASE, 2021-2025 (USD MILLION)
- TABLE 110 EDGE AI SOFTWARE MARKET IN CONSUMER ELECTRONICS & DEVICES, BY USE CASE, 2026-2032 (USD MILLION)
- TABLE 111 EDGE AI SOFTWARE MARKET IN CONSUMER ELECTRONICS & DEVICES, BY REGION, 2021-2025 (USD MILLION)
- TABLE 112 EDGE AI SOFTWARE MARKET IN CONSUMER ELECTRONICS & DEVICES, BY REGION, 2026-2032 (USD MILLION)
- TABLE 113 EDGE AI SOFTWARE MARKET IN OTHER END USERS, BY REGION, 2021-2025 (USD MILLION)
- TABLE 114 EDGE AI SOFTWARE MARKET IN OTHER END USERS, BY REGION, 2026-2032 (USD MILLION)
- TABLE 115 EDGE AI SOFTWARE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 116 EDGE AI SOFTWARE MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 117 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 118 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 119 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 120 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 121 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 122 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 123 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 124 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 125 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 126 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 127 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 128 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 129 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2021-2025 (USD MILLION)
- TABLE 130 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2026-2032 (USD MILLION)
- TABLE 131 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2021-2025 (USD MILLION)
- TABLE 132 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2026-2032 (USD MILLION)
- TABLE 133 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2021-2025 (USD MILLION)
- TABLE 134 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2026-2032 (USD MILLION)
- TABLE 135 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2021-2025 (USD MILLION)
- TABLE 136 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2026-2032 (USD MILLION)
- TABLE 137 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2021-2025 (USD MILLION)
- TABLE 138 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2026-2032 (USD MILLION)
- TABLE 139 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2021-2025 (USD MILLION)
- TABLE 140 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2026-2032 (USD MILLION)
- TABLE 141 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2021-2025 (USD MILLION)
- TABLE 142 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2026-2032 (USD MILLION)
- TABLE 143 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2021-2025 (USD MILLION)
- TABLE 144 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2026-2032 (USD MILLION)
- TABLE 145 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2021-2025 (USD MILLION)
- TABLE 146 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2026-2032 (USD MILLION)
- TABLE 147 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2021-2025 (USD MILLION)
- TABLE 148 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2026-2032 (USD MILLION)
- TABLE 149 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 150 NORTH AMERICA: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 151 US: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 152 US: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 153 US: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 154 US: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 155 US: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 156 US: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 157 US: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 158 US: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 159 US: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 160 US: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 161 US: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 162 US: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 163 CANADA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 164 CANADA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 165 CANADA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 166 CANADA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 167 CANADA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 168 CANADA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 169 CANADA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 170 CANADA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 171 CANADA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 172 CANADA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 173 CANADA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 174 CANADA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 175 EUROPE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 176 EUROPE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 177 EUROPE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 178 EUROPE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 179 EUROPE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 180 EUROPE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 181 EUROPE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 182 EUROPE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 183 EUROPE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 184 EUROPE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 185 EUROPE: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 186 EUROPE: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 187 EUROPE: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2021-2025 (USD MILLION)
- TABLE 188 EUROPE: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2026-2032 (USD MILLION)
- TABLE 189 EUROPE: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2021-2025 (USD MILLION)
- TABLE 190 EUROPE: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2026-2032 (USD MILLION)
- TABLE 191 EUROPE: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2021-2025 (USD MILLION)
- TABLE 192 EUROPE: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2026-2032 (USD MILLION)
- TABLE 193 EUROPE: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2021-2025 (USD MILLION)
- TABLE 194 EUROPE: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2026-2032 (USD MILLION)
- TABLE 195 EUROPE: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2021-2025 (USD MILLION)
- TABLE 196 EUROPE: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2026-2032 (USD MILLION)
- TABLE 197 EUROPE: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2021-2025 (USD MILLION)
- TABLE 198 EUROPE: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2026-2032 (USD MILLION)
- TABLE 199 EUROPE: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2021-2025 (USD MILLION)
- TABLE 200 EUROPE: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2026-2032 (USD MILLION)
- TABLE 201 EUROPE: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2021-2025 (USD MILLION)
- TABLE 202 EUROPE: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2026-2032 (USD MILLION)
- TABLE 203 EUROPE: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2021-2025 (USD MILLION)
- TABLE 204 EUROPE: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2026-2032 (USD MILLION)
- TABLE 205 EUROPE: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2021-2025 (USD MILLION)
- TABLE 206 EUROPE: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2026-2032 (USD MILLION)
- TABLE 207 EUROPE: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 208 EUROPE: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 209 UK: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 210 UK: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 211 UK: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 212 UK: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 213 UK: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 214 UK: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 215 UK: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 216 UK: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 217 UK: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 218 UK: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 219 UK: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 220 UK: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 221 GERMANY: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 222 GERMANY: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 223 GERMANY: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 224 GERMANY: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 225 GERMANY: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 226 GERMANY: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 227 GERMANY: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 228 GERMANY: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 229 GERMANY: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 230 GERMANY: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 231 GERMANY: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 232 GERMANY: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 233 FRANCE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 234 FRANCE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 235 FRANCE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 236 FRANCE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 237 FRANCE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 238 FRANCE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 239 FRANCE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 240 FRANCE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 241 FRANCE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 242 FRANCE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 243 FRANCE: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 244 FRANCE: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 245 ITALY: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 246 ITALY: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 247 ITALY: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 248 ITALY: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 249 ITALY: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 250 ITALY: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 251 ITALY: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 252 ITALY: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 253 ITALY: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 254 ITALY: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 255 ITALY: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 256 ITALY: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 257 SPAIN: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 258 SPAIN: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 259 SPAIN: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 260 SPAIN: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 261 SPAIN: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 262 SPAIN: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 263 SPAIN: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 264 SPAIN: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 265 SPAIN: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 266 SPAIN: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 267 SPAIN: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 268 SPAIN: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 269 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 270 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 271 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 272 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 273 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 274 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 275 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 276 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 277 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 278 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 279 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 280 REST OF EUROPE: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 281 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 282 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 283 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 284 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 285 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 286 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 287 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 288 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 289 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 290 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 291 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 292 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 293 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2021-2025 (USD MILLION)
- TABLE 294 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2026-2032 (USD MILLION)
- TABLE 295 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2021-2025 (USD MILLION)
- TABLE 296 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2026-2032 (USD MILLION)
- TABLE 297 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2021-2025 (USD MILLION)
- TABLE 298 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2026-2032 (USD MILLION)
- TABLE 299 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2021-2025 (USD MILLION)
- TABLE 300 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2026-2032 (USD MILLION)
- TABLE 301 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2021-2025 (USD MILLION)
- TABLE 302 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2026-2032 (USD MILLION)
- TABLE 303 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2021-2025 (USD MILLION)
- TABLE 304 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2026-2032 (USD MILLION)
- TABLE 305 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2021-2025 (USD MILLION)
- TABLE 306 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2026-2032 (USD MILLION)
- TABLE 307 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2021-2025 (USD MILLION)
- TABLE 308 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2026-2032 (USD MILLION)
- TABLE 309 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2021-2025 (USD MILLION)
- TABLE 310 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2026-2032 (USD MILLION)
- TABLE 311 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2021-2025 (USD MILLION)
- TABLE 312 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2026-2032 (USD MILLION)
- TABLE 313 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 314 ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 315 CHINA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 316 CHINA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 317 CHINA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 318 CHINA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 319 CHINA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 320 CHINA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 321 CHINA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 322 CHINA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 323 CHINA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 324 CHINA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 325 CHINA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 326 CHINA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 327 INDIA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 328 INDIA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 329 INDIA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 330 INDIA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 331 INDIA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 332 INDIA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 333 INDIA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 334 INDIA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 335 INDIA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 336 INDIA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 337 INDIA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 338 INDIA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 339 JAPAN: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 340 JAPAN: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 341 JAPAN: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 342 JAPAN: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 343 JAPAN: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 344 JAPAN: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 345 JAPAN: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 346 JAPAN: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 347 JAPAN: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 348 JAPAN: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 349 JAPAN: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 350 JAPAN: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 351 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 352 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 353 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 354 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 355 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 356 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 357 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 358 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 359 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 360 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 361 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 362 SOUTH KOREA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 363 ASEAN: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 364 ASEAN: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 365 ASEAN: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 366 ASEAN: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 367 ASEAN: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 368 ASEAN: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 369 ASEAN: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 370 ASEAN: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 371 ASEAN: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 372 ASEAN: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 373 ASEAN: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 374 ASEAN: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 375 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 376 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 377 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 378 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 379 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 380 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 381 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 382 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 383 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 384 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 385 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 386 REST OF ASIA PACIFIC: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 387 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 388 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 389 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 390 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 391 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 392 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 393 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 394 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 395 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 396 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 397 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 398 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 399 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2021-2025 (USD MILLION)
- TABLE 400 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2026-2032 (USD MILLION)
- TABLE 401 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2021-2025 (USD MILLION)
- TABLE 402 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2026-2032 (USD MILLION)
- TABLE 403 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2021-2025 (USD MILLION)
- TABLE 404 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2026-2032 (USD MILLION)
- TABLE 405 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2021-2025 (USD MILLION)
- TABLE 406 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2026-2032 (USD MILLION)
- TABLE 407 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2021-2025 (USD MILLION)
- TABLE 408 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2026-2032 (USD MILLION)
- TABLE 409 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2021-2025 (USD MILLION)
- TABLE 410 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2026-2032 (USD MILLION)
- TABLE 411 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2021-2025 (USD MILLION)
- TABLE 412 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2026-2032 (USD MILLION)
- TABLE 413 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2021-2025 (USD MILLION)
- TABLE 414 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2026-2032 (USD MILLION)
- TABLE 415 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2021-2025 (USD MILLION)
- TABLE 416 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2026-2032 (USD MILLION)
- TABLE 417 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2021-2025 (USD MILLION)
- TABLE 418 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2026-2032 (USD MILLION)
- TABLE 419 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 420 MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 421 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 422 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 423 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 424 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 425 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 426 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 427 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 428 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 429 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 430 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 431 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 432 SAUDI ARABIA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 433 UAE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 434 UAE: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 435 UAE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 436 UAE: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 437 UAE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 438 UAE: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 439 UAE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 440 UAE: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 441 UAE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 442 UAE: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 443 UAE: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 444 UAE: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 445 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 446 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 447 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 448 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 449 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 450 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 451 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 452 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 453 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 454 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 455 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 456 SOUTH AFRICA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 457 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 458 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 459 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 460 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 461 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 462 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 463 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 464 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 465 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 466 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 467 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 468 REST OF MIDDLE EAST & AFRICA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 469 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 470 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 471 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 472 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 473 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 474 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 475 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 476 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 477 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 478 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 479 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 480 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 481 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2021-2025 (USD MILLION)
- TABLE 482 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY MANUFACTURING USE CASE, 2026-2032 (USD MILLION)
- TABLE 483 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2021-2025 (USD MILLION)
- TABLE 484 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY HEALTHCARE & LIFE SCIENCES USE CASE, 2026-2032 (USD MILLION)
- TABLE 485 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2021-2025 (USD MILLION)
- TABLE 486 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY ENERGY & UTILITIES USE CASE, 2026-2032 (USD MILLION)
- TABLE 487 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2021-2025 (USD MILLION)
- TABLE 488 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY TELECOMMUNICATION USE CASE, 2026-2032 (USD MILLION)
- TABLE 489 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2021-2025 (USD MILLION)
- TABLE 490 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY RETAIL & E-COMMERCE USE CASE, 2026-2032 (USD MILLION)
- TABLE 491 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2021-2025 (USD MILLION)
- TABLE 492 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY AUTOMOTIVE USE CASE, 2026-2032 (USD MILLION)
- TABLE 493 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2021-2025 (USD MILLION)
- TABLE 494 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY TRANSPORTATION & LOGISTICS USE CASE, 2026-2032 (USD MILLION)
- TABLE 495 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2021-2025 (USD MILLION)
- TABLE 496 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SMART CITY USE CASE, 2026-2032 (USD MILLION)
- TABLE 497 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2021-2025 (USD MILLION)
- TABLE 498 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY BFSI USE CASE, 2026-2032 (USD MILLION)
- TABLE 499 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2021-2025 (USD MILLION)
- TABLE 500 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY CONSUMER ELECTRONICS & DEVICES USE CASE, 2026-2032 (USD MILLION)
- TABLE 501 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 502 LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 503 BRAZIL: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 504 BRAZIL: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 505 BRAZIL: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 506 BRAZIL: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 507 BRAZIL: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 508 BRAZIL: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 509 BRAZIL: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 510 BRAZIL: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 511 BRAZIL: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 512 BRAZIL: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 513 BRAZIL: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 514 BRAZIL: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 515 MEXICO: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 516 MEXICO: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 517 MEXICO: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 518 MEXICO: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 519 MEXICO: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 520 MEXICO: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 521 MEXICO: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 522 MEXICO: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 523 MEXICO: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 524 MEXICO: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 525 MEXICO: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 526 MEXICO: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 527 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 528 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 529 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2021-2025 (USD MILLION)
- TABLE 530 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SOFTWARE TYPE, 2026-2032 (USD MILLION)
- TABLE 531 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 532 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 533 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2021-2025 (USD MILLION)
- TABLE 534 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY AI WORKLOAD, 2026-2032 (USD MILLION)
- TABLE 535 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2021-2025 (USD MILLION)
- TABLE 536 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY EDGE ENVIRONMENT, 2026-2032 (USD MILLION)
- TABLE 537 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY END USER, 2021-2025 (USD MILLION)
- TABLE 538 REST OF LATIN AMERICA: EDGE AI SOFTWARE MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 539 OVERVIEW OF STRATEGIES ADOPTED BY KEY EDGE AI SOFTWARE VENDORS, 2025-2026
- TABLE 540 EDGE AI SOFTWARE MARKET: DEGREE OF COMPETITION
- TABLE 541 EDGE AI SOFTWARE MARKET: REGIONAL FOOTPRINT (EDGE AI DEVELOPMENT PLATFORM VENDORS)
- TABLE 542 EDGE AI SOFTWARE MARKET: OFFERING FOOTPRINT (EDGE AI DEVELOPMENT PLATFORM VENDORS)
- TABLE 543 EDGE AI SOFTWARE MARKET: AI WORKLOAD FOOTPRINT (EDGE AI DEVELOPMENT PLATFORM VENDORS)
- TABLE 544 EDGE AI SOFTWARE MARKET: EDGE ENVIRONMENT FOOTPRINT (EDGE AI DEVELOPMENT PLATFORM VENDORS)
- TABLE 545 EDGE AI SOFTWARE MARKET: END USER FOOTPRINT (EDGE AI DEVELOPMENT PLATFORM VENDORS)
- TABLE 546 EDGE AI SOFTWARE MARKET: REGIONAL FOOTPRINT (ENTERPRISE EDGE AI SOLUTION VENDORS)
- TABLE 547 EDGE AI SOFTWARE MARKET: OFFERING FOOTPRINT (ENTERPRISE EDGE AI SOLUTION VENDORS)
- TABLE 548 EDGE AI SOFTWARE MARKET: AI WORKLOAD FOOTPRINT (ENTERPRISE EDGE AI SOLUTION VENDORS)
- TABLE 549 EDGE AI SOFTWARE MARKET: EDGE ENVIRONMENT FOOTPRINT (ENTERPRISE EDGE AI SOLUTION VENDORS)
- TABLE 550 EDGE AI SOFTWARE MARKET: END USER FOOTPRINT (ENTERPRISE EDGE AI SOLUTION VENDORS)
- TABLE 551 EDGE AI SOFTWARE MARKET: REGIONAL FOOTPRINT (EDGE AI SERVICE PROVIDERS)
- TABLE 552 EDGE AI SOFTWARE MARKET: OFFERING FOOTPRINT (EDGE AI SERVICE PROVIDERS)
- TABLE 553 EDGE AI SOFTWARE MARKET: AI WORKLOAD FOOTPRINT (EDGE AI SERVICE PROVIDERS)
- TABLE 554 EDGE AI SOFTWARE MARKET: EDGE ENVIRONMENT FOOTPRINT (EDGE AI SERVICE PROVIDERS)
- TABLE 555 EDGE AI SOFTWARE MARKET: END USER FOOTPRINT (EDGE AI SOFTWARE SERVICE PROVIDERS)
- TABLE 556 EDGE AI SOFTWARE MARKET: PRODUCT LAUNCHES AND ENHANCEMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 557 EDGE AI SOFTWARE MARKET: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 558 AWS: COMPANY OVERVIEW
- TABLE 559 AWS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 560 AWS: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 561 AWS: DEALS
- TABLE 562 MICROSOFT: COMPANY OVERVIEW
- TABLE 563 MICROSOFT: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 564 MICROSOFT: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 565 MICROSOFT: DEALS
- TABLE 566 GOOGLE: COMPANY OVERVIEW
- TABLE 567 GOOGLE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 568 GOOGLE: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 569 GOOGLE: DEALS
- TABLE 570 IBM: COMPANY OVERVIEW
- TABLE 571 IBM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 572 IBM: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 573 IBM: DEALS
- TABLE 574 DELL TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 575 DELL TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 576 DELL TECHNOLOGIES: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 577 DELL TECHNOLOGIES: DEALS
- TABLE 578 SIEMENS: COMPANY OVERVIEW
- TABLE 579 SIEMENS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 580 SIEMENS: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 581 SIEMENS: DEALS
- TABLE 582 SCHNEIDER ELECTRIC: COMPANY OVERVIEW
- TABLE 583 SCHNEIDER ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 584 SCHNEIDER ELECTRIC: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 585 SCHNEIDER ELECTRIC: DEALS
- TABLE 586 NUTANIX: COMPANY OVERVIEW
- TABLE 587 NUTANIX: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 588 NUTANIX: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 589 NUTANIX: DEALS
- TABLE 590 AXELERA AI: COMPANY OVERVIEW
- TABLE 591 AXELERA AI: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 592 AXELERA AI: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 593 AXELERA AI: DEALS
- TABLE 594 ACCENTURE: COMPANY OVERVIEW
- TABLE 595 ACCENTURE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 596 ACCENTURE: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 597 ACCENTURE: DEALS
- TABLE 598 FACTOR ANALYSIS
List of Figures
- FIGURE 1 MARKET SCENARIO
- FIGURE 2 GLOBAL EDGE AI SOFTWARE MARKET, 2021-2032
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN EDGE AI SOFTWARE MARKET, 2025-2026
- FIGURE 4 DISRUPTIONS INFLUENCING THE GROWTH OF EDGE AI SOFTWARE MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS IN EDGE AI SOFTWARE MARKET, 2026-2032
- FIGURE 6 ASIA PACIFIC TO REGISTER THE HIGHEST CAGR IN EDGE AI SOFTWARE MARKET DURING THE FORECAST PERIOD
- FIGURE 7 EDGE AI SOFTWARE IS EVOLVING INTO A CRITICAL ENTERPRISE LAYER FOR SCALABLE INTELLIGENCE ACROSS DISTRIBUTED ENVIRONMENTS
- FIGURE 8 ASIA PACIFIC EDGE AI SOFTWARE MARKET IS POISED TO GROW AT FASTEST PACE BETWEEN 2026 AND 2032
- FIGURE 9 GENERATIVE AI TO BE FASTEST GROWING EDGE AI WORKLOAD DURING FORECAST PERIOD
- FIGURE 10 RUNTIME & INFERENCE SOFTWARE, AND DEVELOPMENT & INTEGRATION SERVICES TO BE LARGEST SHAREHOLDERS IN NORTH AMERICA IN 2026
- FIGURE 11 EDGE AI SOFTWARE MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 12 EDGE AI SOFTWARE MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 13 EDGE AI SOFTWARE MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 14 EDGE AI SOFTWARE MARKET: ECOSYSTEM ANALYSIS
- FIGURE 15 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 16 PROMINENT EDGE AI PLATFORM & INFERENCE COMPANIES, BY FUNDING VALUE (USD MILLION) AND FUNDING ROUND, UNTIL 2026
- FIGURE 17 EDGE AI SOFTWARE TECHNOLOGY ROADMAP, 2025-2032
- FIGURE 18 NUMBER OF PATENTS GRANTED, 2016-2026
- FIGURE 19 REGIONAL ANALYSIS OF PATENTS GRANTED, 2016-2026
- FIGURE 20 FUTURE APPLICATIONS: EDGE AI SOFTWARE
- FIGURE 21 EDGE AI SOFTWARE MARKET DECISION MAKING FACTORS
- FIGURE 22 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE VERTICALS
- FIGURE 23 KEY BUYING CRITERIA FOR TOP THREE END USERS
- FIGURE 24 ADOPTION BARRIERS & INTERNAL CHALLENGES: EDGE AI SOFTWARE MARKET
- FIGURE 25 SOFTWARE SEGMENT TO ACCOUNT FOR LARGER SHARE OF MARKET BY 2032
- FIGURE 26 COMPUTER VISION SEGMENT TO ACCOUNT FOR LARGEST SHARE OF EDGE AI SOFTWARE MARKET BY 2032
- FIGURE 27 NETWORK EDGE ENVIRONMENT TO REGISTER FASTER GROWTH OVER FORECAST PERIOD
- FIGURE 28 AUTOMOTIVE END USER SEGMENT TO EXPAND AT THE FASTEST RATE OVER THE FORECAST PERIOD
- FIGURE 29 NORTH AMERICA TO ACCOUNT FOR HIGHER SHARE OF EDGE AI SOFTWARE MARKET IN 2026
- FIGURE 30 INDIA TO WITNESS FASTEST GROWTH DURING FORECAST PERIOD
- FIGURE 31 NORTH AMERICA: EDGE AI SOFTWARE MARKET SNAPSHOT
- FIGURE 32 ASIA PACIFIC: EDGE AI SOFTWARE MARKET SNAPSHOT
- FIGURE 33 TOP FIVE PLAYERS HAVE DOMINATED THE MARKET OVER LAST FIVE YEARS
- FIGURE 34 SHARE OF LEADING COMPANIES IN EDGE AI SOFTWARE MARKET, 2025
- FIGURE 35 PRODUCT COMPARATIVE ANALYSIS OF EDGE AI DEVELOPMENT PLATFORMS
- FIGURE 36 PRODUCT COMPARATIVE ANALYSIS OF ENTERPRISE EDGE AI SOLUTIONS
- FIGURE 37 EDGE AI SOFTWARE MARKET: COMPANY EVALUATION MATRIX (EDGE AI DEVELOPMENT PLATFORM VENDORS), 2025
- FIGURE 38 EDGE AI SOFTWARE MARKET: COMPANY FOOTPRINT (EDGE AI DEVELOPMENT PLATFORM VENDORS)
- FIGURE 39 EDGE AI SOFTWARE MARKET: COMPANY EVALUATION MATRIX (ENTERPRISE EDGE AI SOLUTION VENDORS), 2025
- FIGURE 40 EDGE AI SOFTWARE MARKET: COMPANY FOOTPRINT (ENTERPRISE EDGE AI SOLUTION VENDORS)
- FIGURE 41 EDGE AI SOFTWARE MARKET: COMPANY EVALUATION MATRIX (EDGE AI SERVICE PROVIDERS), 2025
- FIGURE 42 EDGE AI SOFTWARE MARKET: COMPANY FOOTPRINT (EDGE AI SOFTWARE SERVICE PROVIDERS)
- FIGURE 43 FINANCIAL METRICS OF KEY VENDORS
- FIGURE 44 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 45 AWS: COMPANY SNAPSHOT
- FIGURE 46 MICROSOFT: COMPANY SNAPSHOT
- FIGURE 47 GOOGLE: COMPANY SNAPSHOT
- FIGURE 48 IBM: COMPANY SNAPSHOT
- FIGURE 49 DELL TECHNOLOGIES: COMPANY SNAPSHOT
- FIGURE 50 SIEMENS: COMPANY SNAPSHOT
- FIGURE 51 SCHNEIDER ELECTRIC: COMPANY SNAPSHOT
- FIGURE 52 NUTANIX: COMPANY SNAPSHOT
- FIGURE 53 ACCENTURE: COMPANY SNAPSHOT
- FIGURE 54 EDGE AI SOFTWARE MARKET: RESEARCH DESIGN
- FIGURE 55 DATA TRIANGULATION
- FIGURE 56 EDGE AI SOFTWARE MARKET: TOP-DOWN AND BOTTOM-UP APPROACHES
- FIGURE 57 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 1, BOTTOM-UP (SUPPLY-SIDE): REVENUE FROM SOFTWARE/SERVICES OF THE EDGE AI SOFTWARE MARKET
- FIGURE 58 MARKET SIZE ESTIMATION METHODOLOGY- APPROACH 2, BOTTOM-UP (SUPPLY-SIDE): COLLECTIVE REVENUE FROM ALL SOFTWARE/SERVICES OF THE EDGE AI SOFTWARE MARKET
- FIGURE 59 MARKET SIZE ESTIMATION METHODOLOGY-APPROACH 3, BOTTOM-UP (SUPPLY-SIDE): COLLECTIVE REVENUE FROM ALL SOFTWARE/ SERVICES OF THE EDGE AI SOFTWARE MARKET
- FIGURE 60 MARKET SIZE ESTIMATION METHODOLOGY-APPROACH 4, BOTTOM-UP (DEMAND-SIDE): SHARE OF EDGE AI SOFTWARE THROUGH OVERALL AI SPENDING

