PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121263

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121263
Europe Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe plastic packaging market size is expected to grow from USD 70 billion in 2025 to USD 73.73 billion in 2026 and is forecast to reach USD 95.56 billion by 2031 at 5.33% CAGR over 2026-2031.
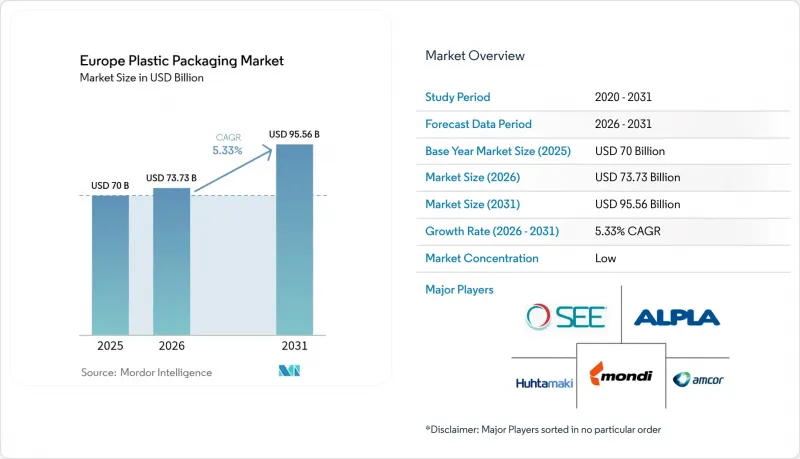
This report is Segmented by Packaging Type (Rigid, Flexible, Industrial & Bulk), Material Type (PET, Polyethylene, Polypropylene, Polystyrene & EPS, PVC, Bioplastics, Recycled Plastics), End-User Industry (Food & Beverages, Personal Care, Healthcare, Chemicals, E-Commerce, Automotive), and Geography (Germany, UK, France, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Plastic Packaging Market Trends and Insights
EU Packaging-Waste Targets Accelerating Recycled Content Mandates
The Packaging and Packaging Waste Regulation (PPWR), effective February 11, 2025, sets a 30% recycled-content threshold in PET food packs by 2030, establishing uniform compliance rules that favor large-scale recyclers. Eco-modulated EPR fees now tilt material-selection decisions toward easily recyclable designs, prompting companies such as ALPLA to lift Polish food-grade rPET output from 30,000 tpa to 54,000 tpa. The removal of PFAS in food contact layers deepens the need for alternative barrier technologies while reinforcing the competitive moat of firms with certified rPET capacity.
E-commerce Boom Boosting Lightweight Protective Formats
A structural surge in online shopping has increased parcel volumes and intensified pressure to reduce packaging weight per shipment. Brand owners are adopting mono-material cushions that cut material use by 25% yet safeguard products in high-velocity fulfillment networks. PPWR rules that favor source-reduction dovetail with courier incentives to trim dimensional weight, amplifying demand for thin-gauge films and recyclable mailers produced by flexible-packaging converters.
Volatile Virgin Resin Prices Linked to Energy Crisis
Energy expense now consumes up to 70% of the cost of goods for some converters as natural-gas prices remain more than fourteen times their ten-year average, leading to production curtailments and 2,068 insolvencies in the German packaging sector in February 2025. The decoupling of virgin and recycled pricing complicates procurement hedges and shrinks working-capital buffers for SMEs.
Other drivers and restraints analyzed in the detailed report include:
- Food-Grade rPET Capacity Expansions Across DACH Region
- FMCG Shift to Mono-Material Pouches for Curb-Side Collection
- PPWR Draft Creating Compliance-Cost Overhang
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rigid formats accounted for 51.35% of the European plastic packaging market share in 2025 thanks to their proven performance in dairy, pharma, and industrial chemicals. The European plastic packaging market size for rigid applications is projected to grow steadily as high-barrier PET and HDPE containers comply with strict shelf-life and safety norms. Consolidation, exemplified by Faerch's purchase of PACCOR, is yielding scale efficiencies and reinforcing closed-loop tray recycling infrastructure. However, cost pass-through remains challenging when resin price spikes outpace customer contracts.
Flexible packaging trails in share yet leads in momentum, advancing at a 5.18% CAGR through 2031 as e-commerce and click-and-collect dominate retail logistics. Lightweight mailers, stand-up pouches, and mono-PE films help shippers cut freight emissions. The European plastic packaging market size for flexible formats gains additional lift from PPWR incentives that reward material minimization. Success depends on commercializing curb-side compatible mono-material films and securing supply of compatible recyclates to satisfy brand-owner pledges.
Complete Report Scope:
- By Packaging Type
- Rigid Plastic Packaging
- Flexible Plastic Packaging
- Industrial & Bulk Plastic Packaging
- By Material Type
- PET
- Polyethylene (HDPE, LDPE, LLDPE)
- Polypropylene
- Polystyrene & EPS
- PVC
- Bioplastics & Bio-based Plastics
- Recycled Plastics (rPET, rHDPE, rPP)
- By End-user Industry
- Food & Beverages
- Personal Care & Cosmetics
- Healthcare & Pharmaceuticals
- Household & Industrial Chemicals
- E-commerce & Retail Fulfilment
- Automotive & Industrial Components
- Geography (Country Level)
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Netherlands
- Poland
- Sweden
- Norway
- Denmark
- Finland
- Belgium
- Austria
List of Companies Covered in this Report:
- Amcor Plc
- Mondi Group
- ALPLA Werke GmbH
- Sealed Air Corp
- Huhtamaki Oyj
- Paccor
- Plastipak Holdings
- Constantia Flexibles
- Coveris Holdings
- Greiner Packaging
- AptarGroup Inc
- Logoplaste
- Schur Flexibles
- Klockner Pentaplast
- Wipak Group
- Silgan Holdings
- DS Smith Plastics
- ALPLA Circular Economy Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Packaging-Waste Targets Accelerating Recycled Content Mandates
- 4.2.2 E-commerce Boom Boosting Lightweight Protective Formats
- 4.2.3 Food-Grade rPET Capacity Expansions Across DACH Region
- 4.2.4 FMCG Shift to Mono-Material Pouches for Curb-Side Collection
- 4.2.5 AI-Enabled Sorting Lines Raising rPlastics Yields (Under-the-radar)
- 4.2.6 Pharma Cold-Chain Growth Driving High-Barrier Rigid PET (Under-the-radar)
- 4.3 Market Restraints
- 4.3.1 Volatile Virgin Resin Prices Linked to Energy Crisis
- 4.3.2 PPWR Draft Creating Compliance Cost Overhang
- 4.3.3 Shortage of Food-Contact rPET Feedstock
- 4.3.4 Anti-dumping Duties Inflating PET Costs in CEE (Under-the-radar)
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Packaging Type
- 5.1.1 Rigid Plastic Packaging
- 5.1.2 Flexible Plastic Packaging
- 5.1.3 Industrial & Bulk Plastic Packaging
- 5.2 By Material Type
- 5.2.1 PET
- 5.2.2 Polyethylene (HDPE, LDPE, LLDPE)
- 5.2.3 Polypropylene
- 5.2.4 Polystyrene & EPS
- 5.2.5 PVC
- 5.2.6 Bioplastics & Bio-based Plastics
- 5.2.7 Recycled Plastics (rPET, rHDPE, rPP)
- 5.3 By End-user Industry
- 5.3.1 Food & Beverages
- 5.3.2 Personal Care & Cosmetics
- 5.3.3 Healthcare & Pharmaceuticals
- 5.3.4 Household & Industrial Chemicals
- 5.3.5 E-commerce & Retail Fulfilment
- 5.3.6 Automotive & Industrial Components
- 5.4 Geography (Country Level)
- 5.4.1 Germany
- 5.4.2 United Kingdom
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Russia
- 5.4.7 Netherlands
- 5.4.8 Poland
- 5.4.9 Sweden
- 5.4.10 Norway
- 5.4.11 Denmark
- 5.4.12 Finland
- 5.4.13 Belgium
- 5.4.14 Austria
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Amcor Plc
- 6.4.2 Mondi Group
- 6.4.3 ALPLA Werke GmbH
- 6.4.4 Sealed Air Corp
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Paccor
- 6.4.7 Plastipak Holdings
- 6.4.8 Constantia Flexibles
- 6.4.9 Coveris Holdings
- 6.4.10 Greiner Packaging
- 6.4.11 AptarGroup Inc
- 6.4.12 Logoplaste
- 6.4.13 Schur Flexibles
- 6.4.14 Klockner Pentaplast
- 6.4.15 Wipak Group
- 6.4.16 Silgan Holdings
- 6.4.17 DS Smith Plastics
- 6.4.18 ALPLA Circular Economy Solutions
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

