PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2043961

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2043961
Insoluble Sulfur - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
The Insoluble Sulfur Market size is expected to increase from USD 1.16 billion in 2025 to USD 1.21 billion in 2026 and reach USD 1.49 billion by 2031, growing at a CAGR of 4.31% over 2026-2031.
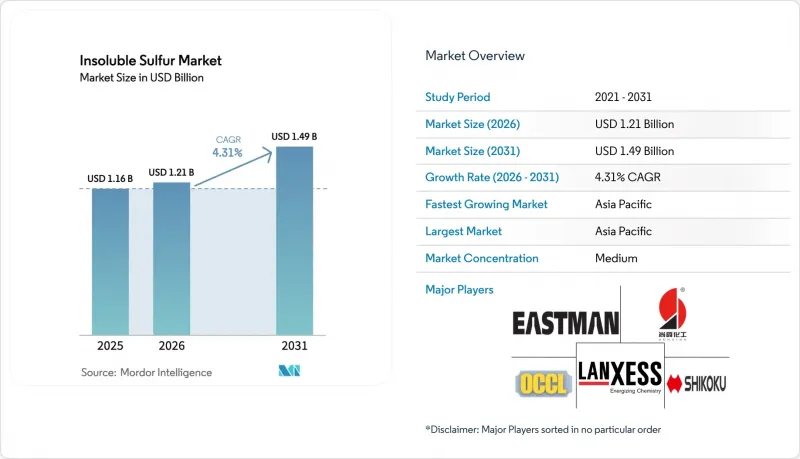
Tire radialization, higher electric-vehicle (EV) penetration, and the shift toward premium high-dispersion grades are reinforcing demand resilience despite margin pressure from elemental sulfur cost spikes. Capacity additions in China and the adoption of continuous-process manufacturing are reshaping cost curves, while Western suppliers focus on low-carbon, high-stability formulations to serve EV tires. Distributor-led sales are expanding as mid-tier compounders seek technical support and just-in-time delivery, and industrial rubber goods capitalize on mining and infrastructure spending. Regulatory scrutiny of carbon disulfide (CS2) exposure and the search for sustainable feedstocks will keep capital requirements high and support long-term price discipline.
Global Insoluble Sulfur Market Trends and Insights
Surging Global OEM and Replacement Tire Production Demand
China produced 1.19 billion tire units in 2024, an increase of 9.2% year on year, while replacement demand remained robust because aging vehicle fleets continue to clock higher mileage. Southeast Asia's dominance in tire exports, led by Thailand's 40.38% share of US passenger-tire imports, keeps regional offtake solid. Radial tires need about 1.7 times more insoluble sulfur than bias-ply designs, reinforcing the volume pull from tire modernization. Tire makers relocating plants to circumvent tariffs are boosting chemical imports and accelerating international orders. Combined, these structural and cyclical forces underpin a sustained volume floor for the insoluble sulfur market.
Shift to EV-Specific Low-Rolling-Resistance Compounds
EV tires carry heavier loads and must deliver a longer range. They therefore rely on silica-rich, low-rolling-resistance compounds that demand insoluble sulfur to prevent bloom and ensure thermal stability. Eastman's Crystex Cure Pro, jointly developed with Double Coin, improves flow and dispersion, enabling shorter mixing times and lower cure temperatures, which saves energy and reduces emissions. Flexsys reports that its Cure Pro Malaysia grade has a 10% lower product carbon footprint than conventional HD-OT20, supporting OEM (original equipment manufacturer) scope-3 targets. Growing EV adoption in China, where new-energy vehicles reached a 41% sales share in 2024, positions premium insoluble sulfur grades for double-digit volume growth through 2031.
Volatile Elemental Sulfur and CS2 Pricing
China's FOB sulfur price hit USD 571 per ton in January 2026, quadrupling from January 2024, after Russia extended its export ban and Middle Eastern producers diverted tonnage to Indonesian nickel projects. Sulfur makes up over half of phosphate-fertilizer costs, so fertilizer demand competes directly with chemical feedstock buyers. LANXESS raised additive prices by up to 50% in March 2026 to preserve margins. Producers without long-term sulfur contracts face margin squeeze and working-capital strain.
Other drivers and restraints analyzed in the detailed report include:
- Continuous-Process IS Manufacturing Boosts Capacity and Consistency
- Rise of Green High-Dispersion, Low-Oil Grades for Sustainability
- Tightening Occupational-Exposure Limits for Dust and CS2
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Regular Oil-Filled Grades (OT33/OT10) hold 33.47% of the Insoluble Sulfur market share owing to cost advantages for bias-ply and replacement tires. The insoluble sulfur market size for regular grades remains the largest, yet premium grades capture incremental margin, especially where OEM sustainability mandates push for lower product carbon footprints. High-Dispersion Premium (HD-OT20) grades captured the fastest growth at a 4.58% CAGR, supported by EV tire needs for low bloom and superior thermal stability. Flexsys's Crystex HD OT 20 specifies more than or equal to 72% insoluble sulfur and maintains stability at 105°C for 15 minutes. Eastman's Cure Pro variant allows lower mixing speeds and saves up to 10% energy.
Low-oil and no-oil grades are gaining traction in high-silica EV compounds. LANXESS's Aflux SD, launched in 2025, improves silica dispersion and wet grip. Flexsys's XD grade posts cradle-to-gate emissions near 1.23 tons CO2 equivalent per kilogram, reinforcing its positioning in low-carbon tires. Suppliers with continuous-process capability can switch between grades quickly, meeting diverse compounder requirements and optimizing asset utilization.
The Insoluble Sulfur Market Report is Segmented by Product Grade (High-Dispersion Premium, Regular Oil-Filled Grades, and Low-Oil/No-Oil Grades), Distribution Channel (Direct To Tire/Rubber Manufacturers and More), Application (Tires, Industrial Rubber Goods, and More), and Geography (Asia-Pacific, North America, Europe, South America, and the Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Geography Analysis
Asia-Pacific held 56.25% of the 2025 value and will post a 5.14% CAGR to 2031, driven by China's tire expansion and EV adoption. China Sunsine raised insoluble sulfur capacity to 60,000 tons per annum, but oversupply kept utilization near 68% in 2024. Shandong Yanggu Huatai's 40,000 tons per annum addition in 2022 depressed average selling prices by 24% through mid-2024. Thailand's natural-rubber supremacy and Vietnam's rising tire plants fortify regional offtake. India is adding capacity to meet domestic auto growth, yet it relies on imports, offering investment headroom for new regional producers.
North America benefits from LANXESS's Bushy Park expansion, which brought new processing-promoter lines online in November 2025. Local production cuts shipment times and enhances security amid geopolitical tension. Flexsys operates US plants that feed domestic OEMs pursuing lower scope-3 emissions. Mexican tire plants serve US automakers, and Canada remains a key sulfur exporter. Regional EV uptake is slower than in China, moderating demand growth but supporting higher-value, low-carbon grades.
Europe's market reflects strict environmental norms and decarbonization mandates. LANXESS's Vulkanox HS Scopeblue, ISCC PLUS-certified since 2024, evidences regional emphasis on bio-based inputs. Flexsys's German HD-OT20 emits 18% less CO2 than its Malaysian counterpart, appealing to European Union (EU) OEMs with aggressive CO2 targets. Russian sulfur export bans and higher energy costs squeeze margins, encouraging process upgrades and local feedstock contracts. South America's growth clusters in Brazil's auto and agricultural equipment sectors, while Middle East and Africa depend on mining-related rubber goods, importing most insoluble sulfur from Asia.
- Chaoyang Mingyu Chemical Co., Ltd.
- Chemiplas Rubber Chemicals
- China Petrochemical Corp.
- China Sunsine Chemical Holdings
- Eastman Chemical Company
- Flexsys
- Henan Kailun Chemical Co., Ltd.
- Honeywell International Inc.
- Jiangxi Hengxingyuan Chemical Co., Ltd.
- KISHO Corporation Co., Ltd.
- Lanxess AG
- Nantong Haotai Chemical Products Co., Ltd.
- Ningxia Xinlong Chemical Industry Co., Ltd.
- OCCL Limited
- SHIKOKU CHEMICALS CORPORATION
- Taizhou Huangyan Donghai Chemical Co., Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging global OEM and replacement tire production demand
- 4.2.2 Shift to EV-specific low-rolling-resistance compounds
- 4.2.3 Continuous-process IS manufacturing boosts capacity and consistency
- 4.2.4 Rise of "green" high-dispersion, low-oil IS grades for sustainability
- 4.2.5 Industrial rubber goods capacity additions in mining and construction
- 4.3 Market Restraints
- 4.3.1 Volatile elemental sulfur and CS2 feedstock pricing
- 4.3.2 Tightening occupational-exposure limits for dust and CS2
- 4.3.3 Emerging peroxide/other non-sulfur cure systems in specialty elastomers
- 4.4 Value Chain Analysis
- 4.5 Regulatory Framework
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Grade
- 5.1.1 High-Dispersion Premium (HD-OT20)
- 5.1.2 Regular Oil-Filled Grades (OT33/OT10)
- 5.1.3 Low-Oil/No-Oil Grades
- 5.2 By Distribution Channel
- 5.2.1 Direct to Tire/Rubber Manufacturers
- 5.2.2 Specialty Chemical Distributors
- 5.3 By Application
- 5.3.1 Tires (Passenger, Commercial, Off-road)
- 5.3.2 Industrial Rubber Goods (Hoses, Belts, Seals)
- 5.3.3 Other Molded and Foamed Rubber Products
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Chaoyang Mingyu Chemical Co., Ltd.
- 6.4.2 Chemiplas Rubber Chemicals
- 6.4.3 China Petrochemical Corp.
- 6.4.4 China Sunsine Chemical Holdings
- 6.4.5 Eastman Chemical Company
- 6.4.6 Flexsys
- 6.4.7 Henan Kailun Chemical Co., Ltd.
- 6.4.8 Honeywell International Inc.
- 6.4.9 Jiangxi Hengxingyuan Chemical Co., Ltd.
- 6.4.10 KISHO Corporation Co., Ltd.
- 6.4.11 Lanxess AG
- 6.4.12 Nantong Haotai Chemical Products Co., Ltd.
- 6.4.13 Ningxia Xinlong Chemical Industry Co., Ltd.
- 6.4.14 OCCL Limited
- 6.4.15 SHIKOKU CHEMICALS CORPORATION
- 6.4.16 Taizhou Huangyan Donghai Chemical Co., Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
8 Key Strategic Questions for CEOs

