PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2044129

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2044129
Color Detection Sensor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
The color detection sensor market size is expected to increase from USD 1.59 billion in 2025 to USD 1.72 billion in 2026 and reach USD 2.37 billion by 2031, growing at a CAGR of 6.63% over 2026-2031.
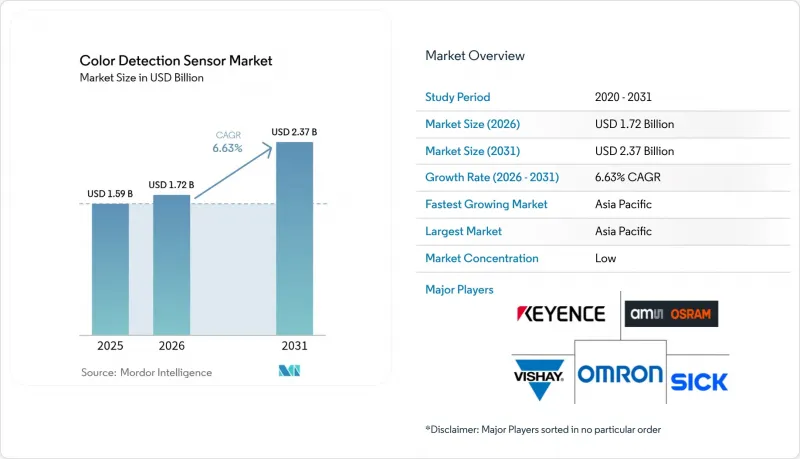
Demand keeps rising as factory owners digitize quality control, smartphone and wearable brands embed chromatic modules for health monitoring, and regulators tighten rules on color uniformity in food and pharmaceutical packaging. Investment is also flowing toward hyperspectral research that promises material-level insights far beyond classic RGB, while machine-learning firmware shortens inspection cycles and trims scrap. Vendors are responding with miniaturized, low-power devices that fit next to camera sensors or robot grippers, allowing real-time validation without slowing throughput. Pricing pressure persists in high-volume consumer electronics, yet industrial and healthcare buyers continue to pay a premium for accuracy, traceability, and long-term supply assurance.
Global Color Detection Sensor Market Trends and Insights
Rising Process Automation Across Discrete and Process Industries
Factories that assemble cars, smartphones, or machinery now rely on inline color checks to confirm part identity, spot coating flaws, and hold paint within tolerance without pausing the line. Chemical and food producers run continuous colorimetry on liquid streams to trigger adjustments before off-spec batches reach packaging. Growth accelerated after large vision suppliers posted double-digit revenue gains from 2025 automation projects. Ethernet-ready sensors feed programmable logic controllers, closing feedback loops that lift first-pass yield and trim rework. Emerging uses include color-coded plastic sorting for recycling and real-time verification of tablet coating in pharma lines where hue correlates with drug release rates.
Proliferation of Color Sensors in Smartphones and Wearables
Phone and watch makers mount RGB and RGB+IR diodes beside cameras or under glass to read pulse, blood-oxygen saturation, and even skin tone for cosmetic advice. With annual handset volumes in the hundreds of millions, component pricing has plunged, spurring suppliers to shrink packages to under 2 mm while adding up to 14 channels of spectral output. R&D now targets non-invasive glucose tests that could open clinical markets once regulators complete guidance on software-as-a-medical-device rules. The high-volume mobile segment, therefore, finances miniaturization that industrial and healthcare adopters quickly repurpose.
High Upfront Cost and ROI Concerns
An inline color station, including a sensor, optics, and integration software, can cost more than USD 10,000, a hurdle for smaller factories with limited capital. Return-on-investment calculations for color detection systems are highly variable, since they depend on scrap rates, production throughput, and the scale of deployment, which makes managers cautious about committing capital until external pressure, such as rising labor costs or stricter customer quality clauses, forces their hand. This hesitation has historically slowed adoption, but vendors are increasingly addressing it with flexible business models that reduce financial risk.
Other drivers and restraints analyzed in the detailed report include:
- Adoption in Industrial Robotics and Machine-Vision Systems
- Stringent Color-Matching Standards in Food-Pharma Packaging
- Ambient-Light Sensitivity and Calibration Complexities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
RGB sensors held 41.27% of the color-detection sensor market share in 2025, maintaining volume leadership because three-channel data satisfies many consumer electronics and automotive applications. Spectral devices, however, are registering a 7.61% CAGR as pharmaceutical coatings, precision agriculture, and counterfeit-protection applications demand wavelength-resolved insight. RGB+IR hybrids bridge the gap by adding near-infrared channels that enhance heart-rate readings and low-light contrast.
Spectral architectures capture detailed signatures that reveal composition and layer thickness, which RGB cannot see. Hyperspectral payloads on drones scan hundreds of bands to map crop health, while inline arrays monitor additive manufacturing layers for color drift linked to powder degradation. CMOS image sensors continue to ride semiconductor cost curves, turning once-premium features into standard options for mid-range devices. Photodiode arrays, though lacking imagery, deliver exceptional signal-to-noise and remain staples in web inspection where spatial resolution matters less than spectral fidelity.
The Color Detection Sensor Market Report is Segmented by Sensor Type (RGB, RGB+IR, Spectral, CMOS, and More), Form Factor (Discrete Module, Embedded, and OEM), End-User Industry (Food and Beverage, Healthcare, Chemical, Textile, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Geography Analysis
Asia-Pacific captured 37.54% of global revenue in 2025 and is forecast to post a 7.56% CAGR through 2031. China's handset and wearable assembly complexes integrate hundreds of millions of RGB+IR chips each year, while Japan leverages robotics expertise to add color checks to welding and painting cells. India's generic pharmaceutical leaders deploy inline spectrophotometers to meet FDA import requirements, and Singapore and Malaysia house semiconductor back-end plants where color-sensing systems validate printed solder paste. Australia, meanwhile, mounts hyperspectral rigs on drones to survey broadacre farms, improving fertilizer targeting.
North America follows closely, driven by stringent FDA color additive rules that require pharmaceutical makers to validate every lot. Detroit paint shops rely on instant tint checks to avoid warranty claims, and U.S. aerospace primes use color vision to inspect composite layers. Canada's food packagers and Mexico's fast-growing auto plants are integrating color stations to meet export targets.
Europe maintains leadership in machine-vision research and packaging legislation. German carmakers combine color and texture analysis to guarantee consistent finishes across global supply chains, and French food regulators enforce tight label-tone tolerance. The United Kingdom's pharma sector accelerated inline adoption after Brexit shifted compliance paperwork in-house. South America and the Middle East and Africa remain smaller today, yet Brazilian textile mills and Saudi petrochemical refineries are installing ruggedized sensors as part of broader Industry 4.0 investments.
- SICK AG
- Ams-Osram AG
- Keyence Corporation
- Omron Corporation
- Vishay Intertechnology Inc.
- EMX Industries Inc.
- Wenglor Sensoric GmbH
- Panasonic Corporation
- Astech Applied Sensor Technology GmbH
- Banner Engineering Corporation
- Baumer NV
- Rockwell Automation Inc.
- Datalogic SpA
- SensoPart Industriesensorik GmbH
- Jenoptik AG
- Hamamatsu Photonics KK
- Balluff GmbH
- Pepperl+Fuchs Inc.
- Tri-Tronics Company Inc.
- IDEC Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Process Automation Across Discrete and Process Industries
- 4.2.2 Proliferation of Color Sensors in Smartphones and Wearables
- 4.2.3 Adoption in Industrial Robotics and Machine-Vision Systems
- 4.2.4 Stringent Color-Matching Standards in Food-Pharma Packaging
- 4.2.5 Inline Color Measurement for Additive Manufacturing
- 4.2.6 Hyperspectral Color Sensing in Precision-Agri Drones
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost and ROI Concerns
- 4.3.2 Ambient-Light Sensitivity and Calibration Complexities
- 4.3.3 Availability of Low-Cost Monochrome Alternatives
- 4.3.4 Rare-Earth Photodiode Material Supply Volatility
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sensor Type
- 5.1.1 RGB
- 5.1.2 RGB+IR
- 5.1.3 Spectral
- 5.1.4 CMOS
- 5.1.5 Photodiode Array
- 5.2 By Form Factor
- 5.2.1 Discrete Module
- 5.2.2 Embedded
- 5.2.3 OEM
- 5.3 By End-User Industry
- 5.3.1 Food and Beverage
- 5.3.2 Healthcare
- 5.3.3 Chemical
- 5.3.4 Textile
- 5.3.5 Automotive
- 5.3.6 Consumer Electronics
- 5.3.7 Rest of End-User Industries
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 Singapore
- 5.4.4.5 Australia
- 5.4.4.6 Malaysia
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 SICK AG
- 6.4.2 Ams-Osram AG
- 6.4.3 Keyence Corporation
- 6.4.4 Omron Corporation
- 6.4.5 Vishay Intertechnology Inc.
- 6.4.6 EMX Industries Inc.
- 6.4.7 Wenglor Sensoric GmbH
- 6.4.8 Panasonic Corporation
- 6.4.9 Astech Applied Sensor Technology GmbH
- 6.4.10 Banner Engineering Corporation
- 6.4.11 Baumer NV
- 6.4.12 Rockwell Automation Inc.
- 6.4.13 Datalogic SpA
- 6.4.14 SensoPart Industriesensorik GmbH
- 6.4.15 Jenoptik AG
- 6.4.16 Hamamatsu Photonics KK
- 6.4.17 Balluff GmbH
- 6.4.18 Pepperl+Fuchs Inc.
- 6.4.19 Tri-Tronics Company Inc.
- 6.4.20 IDEC Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

