PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2061979

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2061979
Leafy Greens - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
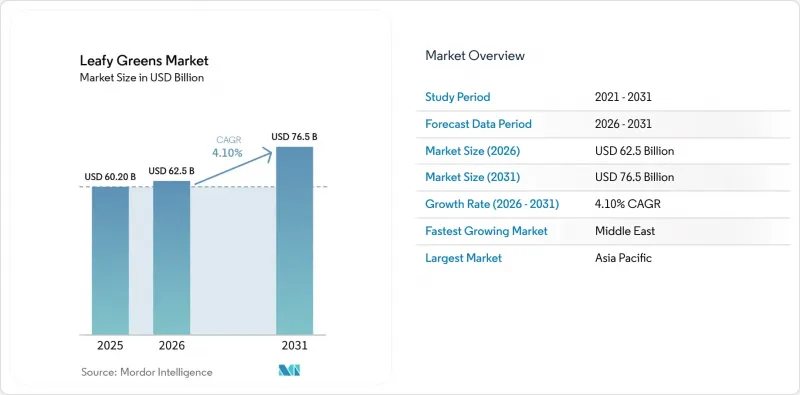
According to Mordor Intelligence, the leafy greens market size is projected to be USD 60.2 billion in 2025, USD 62.5 billion in 2026, and reach USD 76.5 billion by 2031, growing at a CAGR of 4.1% from 2026 to 2031.
This report is Segmented by Product Type (Lettuce, and Others) and by Geography (North America, Europe, and More). The Report Includes Production Analysis (Volume), Consumption Analysis (Value and Volume), Import Analysis (Value and Volume), Export Analysis (Value and Volume), Wholesale Price Trend Analysis and Forecast, and More. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Metric Tons).
Global Leafy Greens Market Trends and Insights
Rising Demand for Nutrient-Dense Foods
Health-conscious shoppers continue to reallocate grocery budgets toward low-calorie, micronutrient-rich vegetables following the 2025 post-pandemic wellness surge. Leafy greens supply folate, vitamin K, and iron at minimal caloric cost, making them staples in weight-management and chronic-disease-prevention regimens championed by public-health campaigns. Urban households purchase pre-washed kits at elevated rates because two-income families value time savings, and meal-kit services often feature greens as the base ingredient. Asia-Pacific middle-class families are following similar patterns as disposable incomes climb and Western food habits diffuse through supermarket expansion. The result is sustained unit growth even when average retail prices edge higher, reinforcing long-run demand in the leafy greens market.
Expansion of Controlled-Environment Agriculture
CEA has shifted from pilots to industrial-scale assets, enabling multiple harvests each year and tighter yield predictability than field production. Partnerships such as Plenty and Mawarid in Abu Dhabi exemplify sovereign efforts to reduce import dependence with vertical infrastructure. GigaFarm, under construction in Dubai Food Tech Valley, will push regional annual output to 3 million kilograms once operational in late 2026. North American incumbents are mirroring the move, as Taylor Farms bought Equinox Growers in March 2026 to lock in 6 million pounds of greenhouse capacity per year. Energy costs remain the biggest constraint, but falling photovoltaic prices and power-purchase agreements are improving economics for new builds in the leafy greens market.
High Energy Costs in Vertical Farming
Electricity for LED lighting, cooling, and nutrient pumps drives a large share of vertical-farm operating budgets. European facilities faced cost spikes during the 2024 energy crisis, forcing production pauses at peak tariff hours. Some growers installed solar arrays and batteries to hedge volatility, but these upgrades lengthen payback horizons and raise capital intensity. Sites in the Middle East enjoy cheap solar power yet still need storage to smooth nighttime demand. Until renewable penetration rises and storage costs fall globally, energy will remain the most immediate brake on CEA expansion inside the leafy greens market.
Other drivers and restraints analyzed in the detailed report include:
- Corporate Net-Zero Commitments Advancing Indoor Farming
- Retailer Private-Label Salad-Kit Innovation
- Labor Shortages in Harvesting and Packing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lettuce accounted for 43% of global consumption in 2025, underscoring its ubiquity in salads, sandwiches, and wraps, which anchor the leafy greens market. Spinach and kale maintained stable demand, backed by smoothie culture and nutrient-dense messaging, though their growth trailed lettuce's due to narrower culinary uses. Arugula is gaining popularity in Europe and North America as diners crave its peppery flavor, while beet greens and Swiss chard remain niche beyond Mediterranean and Middle Eastern cuisines. Microgreens deliver premium margins as chefs value intense flavor and visual appeal, and their seven-to-fourteen-day cycles align perfectly with vertical farm economics. Seed companies and CEA operators are co-developing proprietary microgreen cultivars that extend shelf life and elevate nutrient density, differentiating this subsegment inside the leafy greens commodity industry.
Vertical farms are particularly suited to microgreens because lighting and space requirements are lower per revenue dollar than for mature heads, thereby compressing energy costs per kilogram. As a result, microgreens are advancing at a 11.8% CAGR and are projected to capture an outsized share of incremental value in the leafy greens market by 2031. Genome-edited lettuce, still in pre-commercial trials, could unlock fresh growth vectors if regulators approve nutrient-boosted lines that justify premium pricing. Open-field systems continue to supply price-sensitive channels but face mounting water and labor challenges that erode historical cost edges. Greenhouse operations provide a middle path, using natural light to curb power bills while offering more climate resilience than fields. Strategic acquisitions like Taylor Farms' purchase of Equinox Growers highlight how mainstream packers are hedging risk by balancing all three production modes within their leafy greens market portfolio.
Geography Analysis
Asia-Pacific held 46.2% of global consumption in 2025 and is set to grow at a descent CAGR through 2031. China's middle class is boosting salad-kit uptake as Western retail formats spread across tier-one and tier-two cities, while public health campaigns promote iron-rich dark greens. Japan's aging population is embracing nutrient-dense vegetables to manage hypertension and diabetes, fueling steady demand for ready-to-eat packs. India's urban centers are adding salad bars and subscription meal boxes, yet rural diets still lean toward sauteed or stewed greens, which use longer-cooking varieties. Regional CEA investment is nascent but accelerating in densely populated metros where land prices and climatic risks favor vertical systems, reinforcing Asia-Pacific's leadership in the leafy greens market.
The Middle East is the fastest-growing region, with a 7.2% CAGR, as sovereign wealth funds bankroll CEA megaprojects to reduce import dependence. Companies such as GigaFarm contribute to industry growth in Dubai, and Saudi Arabia's Public Investment Fund has aligned with AeroFarms to replicate the model regionwide. Extreme heat and chronic water scarcity make indoor agriculture a policy imperative, shifting share away from imports flown in from Europe and Africa. Local shoppers are willing to pay a premium for home-grown freshness, underpinning revenue upside in the leafy greens market.
North America accounted for a significant share of revenue in 2025 and is expanding at a prominent CAGR, driven by relentless salad-kit innovation and CEA integration by legacy packers. California's Salinas Valley and Arizona's Yuma region remain field powerhouses but confront water caps under the Sustainable Groundwater Management Act that could limit acreage by 2031. Canada's greenhouse industry is growing with support from federal and provincial grants, as well as the Growing Greenhouses program for automation and renewable energy investments. Mexico leverages lower labor costs to ship romaine and iceberg north, yet trade friction remains a latent risk as antidumping disputes in other produce categories illustrate. Europe's CAGR is slower as mature markets saturate and Spanish output faces irrigation curbs, but Dutch and Belgian greenhouses are poised to fill winter gaps, maintaining regionwide supply stability in the leafy greens market.
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for nutrient-dense foods
- 4.2.2 Expansion of controlled-environment agriculture (CEA)
- 4.2.3 Corporate net-zero commitments advancing indoor farming
- 4.2.4 Retailer private-label salad-kit innovation
- 4.2.5 Emergence of carbon-credit revenue streams for CEA farms
- 4.2.6 Genome-edited lettuce varieties with extended shelf-life
- 4.3 Market Restraints
- 4.3.1 High energy costs in vertical farming
- 4.3.2 Labor shortages in harvesting and packing
- 4.3.3 Price sensitivity versus field-grown produce
- 4.3.4 Water-use regulations in drought-prone regions
- 4.4 Opportunities
- 4.5 Challenges
- 4.6 Value Chain Analysis
- 4.7 Technologies and usage of AI in the Industry
- 4.8 Input Market Analysis
- 4.8.1 Seeds
- 4.8.2 Fertilizers
- 4.8.3 Crop Protection Chemicals
- 4.9 Distribution Channel Analysis
- 4.10 Market Sentiment Analysis
- 4.11 PESTLE Analysis
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Product Type
- 5.1.1 Lettuce
- 5.1.1.1 Production Analysis
- 5.1.1.1.1 Production Volume
- 5.1.1.1.2 Area Harvested and Yield
- 5.1.1.2 Consumption Analysis (Value and Volume)
- 5.1.1.3 Trade Analysis (Value and Volume)
- 5.1.1.3.1 Import Market Analysis
- 5.1.1.3.1.1 Import Value and Volume
- 5.1.1.3.1.2 Key Supplying Markets
- 5.1.1.3.2 Export Market Analysis
- 5.1.1.3.2.1 Export Value and Volume
- 5.1.1.3.2.2 Key Destinations Markets
- 5.1.1.3.1 Import Market Analysis
- 5.1.1.4 Wholesale Price Trend Analysis and Forecast
- 5.1.1.5 Regulatory Framework
- 5.1.1.6 List of Key Players
- 5.1.1.7 Logistics and Infrastructure
- 5.1.1.8 Seasonality Analysis
- 5.1.1.1 Production Analysis
- 5.1.2 Spinach
- 5.1.2.1 Similar to Lettuce
- 5.1.3 Kale
- 5.1.3.1 Similar to Lettuce
- 5.1.4 Arugula
- 5.1.4.1 Similar to Lettuce
- 5.1.5 Beet Greens
- 5.1.5.1 Similar to Lettuce
- 5.1.6 Microgreens
- 5.1.6.1 Similar to Lettuce
- 5.1.7 Swiss Chard
- 5.1.7.1 Similar to Lettuce
- 5.1.1 Lettuce
- 5.2 By Geography
- 5.2.1 North America
- 5.2.1.1 United States
- 5.2.1.1.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.1.1.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.1.1.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.1.1.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.1.1.5 Wholesale Price Trend Analysis and Forecast
- 5.2.1.1.6 Regulatory Framework
- 5.2.1.1.7 List of Key Players
- 5.2.1.1.8 Logistics and Infrastructure
- 5.2.1.1.9 Seasonality Analysis
- 5.2.1.2 Canada
- 5.2.1.2.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.1.2.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.1.2.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.1.2.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.1.2.5 Wholesale Price Trend Analysis and Forecast
- 5.2.1.2.6 Regulatory Framework
- 5.2.1.2.7 List of Key Players
- 5.2.1.2.8 Logistics and Infrastructure
- 5.2.1.2.9 Seasonality Analysis
- 5.2.1.3 Mexico
- 5.2.1.3.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.1.3.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.1.3.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.1.3.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.1.3.5 Wholesale Price Trend Analysis and Forecast
- 5.2.1.3.6 Regulatory Framework
- 5.2.1.3.7 List of Key Players
- 5.2.1.3.8 Logistics and Infrastructure
- 5.2.1.3.9 Seasonality Analysis
- 5.2.1.1 United States
- 5.2.2 South America
- 5.2.2.1 Brazil
- 5.2.2.1.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.2.1.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.2.1.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.2.1.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.2.1.5 Wholesale Price Trend Analysis and Forecast
- 5.2.2.1.6 Regulatory Framework
- 5.2.2.1.7 List of Key Players
- 5.2.2.1.8 Logistics and Infrastructure
- 5.2.2.1.9 Seasonality Analysis
- 5.2.2.2 Argentina
- 5.2.2.2.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.2.2.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.2.2.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.2.2.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.2.2.5 Wholesale Price Trend Analysis and Forecast
- 5.2.2.2.6 Regulatory Framework
- 5.2.2.2.7 List of Key Players
- 5.2.2.2.8 Logistics and Infrastructure
- 5.2.2.2.9 Seasonality Analysis
- 5.2.2.3 Chile
- 5.2.2.3.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.2.3.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.2.3.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.2.3.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.2.3.5 Wholesale Price Trend Analysis and Forecast
- 5.2.2.3.6 Regulatory Framework
- 5.2.2.3.7 List of Key Players
- 5.2.2.3.8 Logistics and Infrastructure
- 5.2.2.3.9 Seasonality Analysis
- 5.2.2.1 Brazil
- 5.2.3 Europe
- 5.2.3.1 Germany
- 5.2.3.1.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.3.1.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.3.1.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.3.1.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.3.1.5 Wholesale Price Trend Analysis and Forecast
- 5.2.3.1.6 Regulatory Framework
- 5.2.3.1.7 List of Key Players
- 5.2.3.1.8 Logistics and Infrastructure
- 5.2.3.1.9 Seasonality Analysis
- 5.2.3.2 United Kingdom
- 5.2.3.2.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.3.2.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.3.2.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.3.2.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.3.2.5 Wholesale Price Trend Analysis and Forecast
- 5.2.3.2.6 Regulatory Framework
- 5.2.3.2.7 List of Key Players
- 5.2.3.2.8 Logistics and Infrastructure
- 5.2.3.2.9 Seasonality Analysis
- 5.2.3.3 France
- 5.2.3.3.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.3.3.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.3.3.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.3.3.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.3.3.5 Wholesale Price Trend Analysis and Forecast
- 5.2.3.3.6 Regulatory Framework
- 5.2.3.3.7 List of Key Players
- 5.2.3.3.8 Logistics and Infrastructure
- 5.2.3.3.9 Seasonality Analysis
- 5.2.3.4 Russia
- 5.2.3.4.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.3.4.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.3.4.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.3.4.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.3.4.5 Wholesale Price Trend Analysis and Forecast
- 5.2.3.4.6 Regulatory Framework
- 5.2.3.4.7 List of Key Players
- 5.2.3.4.8 Logistics and Infrastructure
- 5.2.3.4.9 Seasonality Analysis
- 5.2.3.1 Germany
- 5.2.4 Asia-Pacific
- 5.2.4.1 China
- 5.2.4.1.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.4.1.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.4.1.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.4.1.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.4.1.5 Wholesale Price Trend Analysis and Forecast
- 5.2.4.1.6 Regulatory Framework
- 5.2.4.1.7 List of Key Players
- 5.2.4.1.8 Logistics and Infrastructure
- 5.2.4.1.9 Seasonality Analysis
- 5.2.4.2 India
- 5.2.4.2.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.4.2.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.4.2.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.4.2.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.4.2.5 Wholesale Price Trend Analysis and Forecast
- 5.2.4.2.6 Regulatory Framework
- 5.2.4.2.7 List of Key Players
- 5.2.4.2.8 Logistics and Infrastructure
- 5.2.4.2.9 Seasonality Analysis
- 5.2.4.3 Japan
- 5.2.4.3.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.4.3.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.4.3.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.4.3.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.4.3.5 Wholesale Price Trend Analysis and Forecast
- 5.2.4.3.6 Regulatory Framework
- 5.2.4.3.7 List of Key Players
- 5.2.4.3.8 Logistics and Infrastructure
- 5.2.4.3.9 Seasonality Analysis
- 5.2.4.4 Australia
- 5.2.4.4.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.4.4.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.4.4.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.4.4.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.4.4.5 Wholesale Price Trend Analysis and Forecast
- 5.2.4.4.6 Regulatory Framework
- 5.2.4.4.7 List of Key Players
- 5.2.4.4.8 Logistics and Infrastructure
- 5.2.4.4.9 Seasonality Analysis
- 5.2.4.1 China
- 5.2.5 Middle East
- 5.2.5.1 Saudi Arabia
- 5.2.5.1.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.5.1.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.5.1.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.5.1.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.5.1.5 Wholesale Price Trend Analysis and Forecast
- 5.2.5.1.6 Regulatory Framework
- 5.2.5.1.7 List of Key Players
- 5.2.5.1.8 Logistics and Infrastructure
- 5.2.5.1.9 Seasonality Analysis
- 5.2.5.2 United Arab Emirates
- 5.2.5.2.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.5.2.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.5.2.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.5.2.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.5.2.5 Wholesale Price Trend Analysis and Forecast
- 5.2.5.2.6 Regulatory Framework
- 5.2.5.2.7 List of Key Players
- 5.2.5.2.8 Logistics and Infrastructure
- 5.2.5.2.9 Seasonality Analysis
- 5.2.5.3 Iran
- 5.2.5.3.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.5.3.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.5.3.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.5.3.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.5.3.5 Wholesale Price Trend Analysis and Forecast
- 5.2.5.3.6 Regulatory Framework
- 5.2.5.3.7 List of Key Players
- 5.2.5.3.8 Logistics and Infrastructure
- 5.2.5.3.9 Seasonality Analysis
- 5.2.5.1 Saudi Arabia
- 5.2.6 Africa
- 5.2.6.1 South Africa
- 5.2.6.1.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.6.1.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.6.1.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.6.1.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.6.1.5 Wholesale Price Trend Analysis and Forecast
- 5.2.6.1.6 Regulatory Framework
- 5.2.6.1.7 List of Key Players
- 5.2.6.1.8 Logistics and Infrastructure
- 5.2.6.1.9 Seasonality Analysis
- 5.2.6.2 Nigeria
- 5.2.6.2.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.6.2.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.6.2.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.6.2.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.6.2.5 Wholesale Price Trend Analysis and Forecast
- 5.2.6.2.6 Regulatory Framework
- 5.2.6.2.7 List of Key Players
- 5.2.6.2.8 Logistics and Infrastructure
- 5.2.6.2.9 Seasonality Analysis
- 5.2.6.3 Egypt
- 5.2.6.3.1 Production Analysis (Area Harvested, Yield, and Production Volume)
- 5.2.6.3.2 Consumption Analysis (Consumption Value and Volume)
- 5.2.6.3.3 Import Market Analysis (Import Value, Volume, and Key Supplying Markets)
- 5.2.6.3.4 Export Market Analysis (Export Value, Volume, and Key Destination Markets)
- 5.2.6.3.5 Wholesale Price Trend Analysis and Forecast
- 5.2.6.3.6 Regulatory Framework
- 5.2.6.3.7 List of Key Players
- 5.2.6.3.8 Logistics and Infrastructure
- 5.2.6.3.9 Seasonality Analysis
- 5.2.6.1 South Africa
- 5.2.1 North America
6 End Use and Application
- 6.1 Primary Applications and Emerging Applications
- 6.2 Consumption Breakdown by Industries
7 Competitive Landscape
- 7.1 Overview of the Competition
- 7.2 Recent Developments
- 7.3 Market Concentration Analysis
8 Market Opportunity and Future Outlook

