PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2062331

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2062331
Cast Acrylic Sheet - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the cast acrylic sheet market size is projected to expand from USD 3.82 billion in 2025 and USD 4.05 billion in 2026 to USD 5.39 billion by 2031, registering a CAGR of 5.90% between 2026 to 2031.
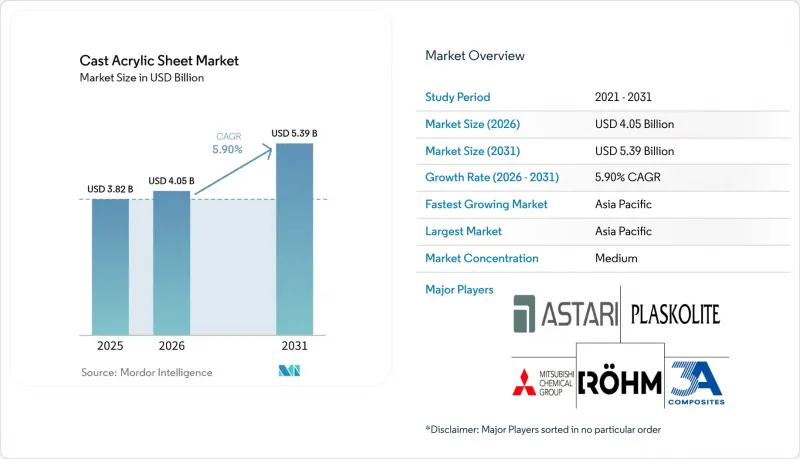
This report is Segmented by Product Type (Clear Cast Acrylic Sheet, Colored Cast Acrylic Sheet, and More), Thickness (Less Than or Equal To 5 Mm, 5. 1-10 Mm, and More), End-User Industry (Signage and Display, Architecture and Interior Design, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Cast Acrylic Sheet Market Trends and Insights
Growing Demand in Signage and Display Applications
Signage and display applications accounted for 34.69 of the 2025 revenue, as cast acrylic offers 92-93% light transmission and precise thickness tolerance, simplifying edge bonding. Large retail chains in Asia are transitioning from traditional PVC boards to UV-stabilized acrylic formats to comply with durability standards. Light-diffusing grades eliminate LED hot-spotting, supporting the growth of digital signage cabinets. Demand has stabilized and is now shifting from initial installations to scheduled refurbishments that incorporate anti-reflective and antimicrobial coatings. While polycarbonate remains the preferred material for high-impact applications like bus shelters, acrylic dominates in areas where optical clarity is prioritized over vandal resistance.
Increased Glass Substitution in Construction and Automotive
At half the density of glass, cast acrylic reduces dead loads in applications such as facade accents, skylight diffusers, and electric vehicle sunroofs. Impact-modified variants like DURAPLEX provide tenfold greater resistance compared to general-purpose sheets, renewing OEM interest in side-glazing concepts. Building-integrated photovoltaics increasingly specify acrylic secondary glazing to protect modules without adding structural steel weight. European embodied-carbon disclosures have slowed momentum, as cast PMMA has a carbon footprint of 4.77 kg CO2-eq/kg, which is 27% higher than extruded sheets. Nevertheless, long-term weight savings and design flexibility continue to support its adoption.
Volatility in MMA and Other Raw-Material Prices
Spot MMA prices ranged between USD 1.52 and USD 1.79 per kg in February 2026, impacting the already narrow EBITDA margins of 8-12% typical for mid-scale sheet producers. The cancellation of Mitsubishi Chemical's 350-ktpa Louisiana complex in 2025 removed a potential supply buffer for North American markets. Chemical-recycling feedstock provides a partial hedge by creating alternative MMA streams that are less dependent on crude oil benchmarks.
Other drivers and restraints analyzed in the detailed report include:
- Rise of PoS Protective Screens Post-COVID
- Sustainability Repositioning Through Bio-Based MMA Supply
- High-Impact Substitutes (Polycarbonate, PETG)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Specialty grades are anticipated to grow at a CAGR of 6.68% through 2031, adding significant value to the cast acrylic sheet market. Clear cast acrylic sheets held a 36.87% market share in 2025, driven by their established use in signage applications. Colored, patterned, and textured variants cater to decorative niches. Impact-modified DURAPLEX sheets create opportunities in mobility and machine-guard applications, while light-diffusing formulations improve LED luminaire efficiency. The availability of bio-based resins supports premium pricing strategies. Growth is also driven by co-extruded film laminates that incorporate scratch-resistant caps around impact cores, addressing demand in premium automotive interiors.
Demand for performance features has intensified competition among suppliers to patent additive packages that maintain 92-93% light transmission and Delta b<= 2 after 5,000 hours of Q-UV exposure. In-house color-matching centers, digital twin formulation tools, and rapid-heat-cycle mold technologies are reducing development cycles and strengthening OEM relationships. These trends reinforce the cast acrylic sheet market's transition from a commodity-based approach to a solution-oriented focus.
Geography Analysis
Asia-Pacific generated 48.02% of 2025 revenue and is poised for a 7.18% CAGR through 2031, supported by recycled-PMMA standards effective July 2026 that legalize post-industrial regrind feedstock. Chinese producers combine vertical MMA integration and high-capacity block casting to service aquarium megaprojects, while Japan and South Korea favor specialty light-diffusing grades for electronics backlights. India's limited 5 ktpa domestic MMA base compels import dependence, yet rising infrastructure spend lifts signage and architectural orders and fortifies the cast acrylic sheet market in South Asia.
In North America, Plaskolite's acquisition of the Matamoros facility and Rohm's Wallingford expansion shorten supply chains and provide specialty-grade agility. The loss of Mitsubishi Chemical's Louisiana MMA project, however, sustains feedstock tightness. Corporate sustainability pledges accelerate interest in depolymerized MMA, supporting future cast acrylic sheet market expansion despite raw-material headwinds.
In Europe, Germany leads regional supply after Rohm reinstated sulfuric-acid self-sufficiency and Evonik started the world's widest PMMA co-extrusion line. Green-Deal life-cycle mandates challenge high-embodied-carbon materials, yet pilot chemical-recycling lines and bio-based MMA agreements help safeguard regional cast acrylic sheet market growth. Mediterranean yacht and aquarium builds maintain steady thick-sheet demand, balancing weaker industrial output in Eastern Europe.
- 3A Composites GmbH
- Aristech Surfaces LLC
- Asia Poly Holdings Berhad
- Atoglas (Arkema)
- Cosmo Industrial Products Pvt. Ltd.
- Evonik Industries AG
- Madreperla SpA
- Margacipta
- Mitsubishi Chemical Infratec Co.,Ltd.
- Olida Ltd.
- Plaskolite
- POLYVANTIS GmbH
- PT Astari Niagara Internasional
- Roehm Chemical (Shanghai) Co., Ltd.
- Rohm GmbH
- Shaktiacryplast
- SHING FU ENTERPRISE CO., LTD.
- Simona AG
- Spartech LLC
- Taixing Donchamp Acrylic
- Trinseo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand in signage and display applications
- 4.2.2 Increased glass substitution in construction and automotive
- 4.2.3 Rise of PoS protective screens post-COVID
- 4.2.4 Secondary glazing for BIPV and utility-scale solar farms
- 4.2.5 Premium aquaculture viewing tanks adoption
- 4.2.6 Sustainability repositioning through bio-based MMA supply
- 4.3 Market Restraints
- 4.3.1 Volatility in MMA and other raw-material prices
- 4.3.2 High-impact substitutes (polycarbonate, PETG)
- 4.3.3 Embodied-carbon scrutiny versus glass and PET
- 4.3.4 Tightening solvent-VOC emission standards in Asia
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Clear Cast Acrylic Sheet
- 5.1.2 Colored Cast Acrylic Sheet
- 5.1.3 Patterned/Textured Cast Acrylic Sheet
- 5.1.4 Specialty Grades
- 5.1.4.1 UV-resistant
- 5.1.4.2 Anti-static
- 5.1.4.3 Impact-modified
- 5.1.4.4 Light-diffusing
- 5.2 By Thickness
- 5.2.1 Less than or equal to 5 mm
- 5.2.2 5.1 - 10 mm
- 5.2.3 10.1 - 20 mm
- 5.2.4 Greater than 20 mm (Block)
- 5.3 By End-user Industry
- 5.3.1 Signage and Display
- 5.3.2 Architecture and Interior Design
- 5.3.3 Automotive and Transportation
- 5.3.4 Furniture and Design
- 5.3.5 Medical and Life Sciences
- 5.3.6 Marine and Leisure
- 5.3.7 Solar and Renewable Energy
- 5.3.8 Aquaculture and Aquariums
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3A Composites GmbH
- 6.4.2 Aristech Surfaces LLC
- 6.4.3 Asia Poly Holdings Berhad
- 6.4.4 Atoglas (Arkema)
- 6.4.5 Cosmo Industrial Products Pvt. Ltd.
- 6.4.6 Evonik Industries AG
- 6.4.7 Madreperla SpA
- 6.4.8 Margacipta
- 6.4.9 Mitsubishi Chemical Infratec Co.,Ltd.
- 6.4.10 Olida Ltd.
- 6.4.11 Plaskolite
- 6.4.12 POLYVANTIS GmbH
- 6.4.13 PT Astari Niagara Internasional
- 6.4.14 Roehm Chemical (Shanghai) Co., Ltd.
- 6.4.15 Rohm GmbH
- 6.4.16 Shaktiacryplast
- 6.4.17 SHING FU ENTERPRISE CO., LTD.
- 6.4.18 Simona AG
- 6.4.19 Spartech LLC
- 6.4.20 Taixing Donchamp Acrylic
- 6.4.21 Trinseo
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

