PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2066528

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2066528
Software-Defined Wide Area Network - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the software-Defined wide area network market size is expected to grow from USD 7.92 billion in 2025 to USD 11.61 billion in 2026 and is forecast to reach USD 28.32 billion by 2031 at 19.53% CAGR over 2026-2031.
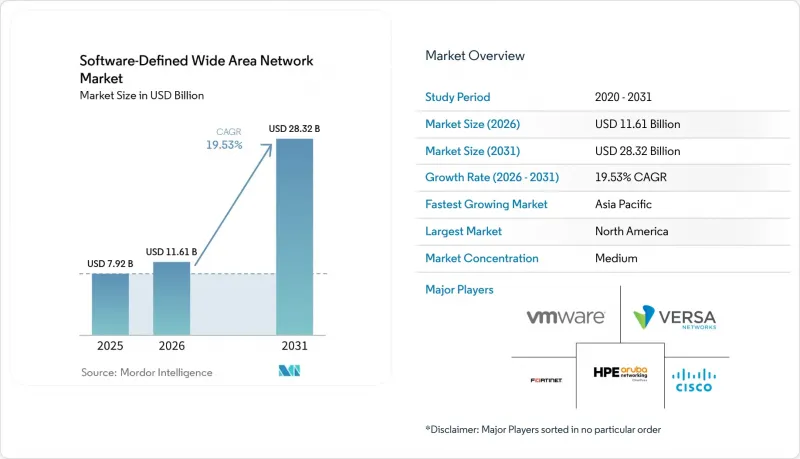
This report is Segmented by Deployment Mode (Premise, Cloud, and Hybrid), Component (Solutions and Services), Organization Size (Large Enterprises and Small and Medium Enterprises), End-User Industry (Healthcare, BFSI, Retail and Consumer Services, Manufacturing, Transport and Logistics, and IT and Telecom), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Software-Defined Wide Area Network Market Trends and Insights
Cloud-centric Application Explosion
Nearly 65% of enterprise workloads had shifted to public or hybrid cloud platforms by 2025, exposing the latency penalties of hub-and-spoke WAN topologies. SD-WAN overlays enable direct internet breakout at branch locations, shaving seconds off application response times for Microsoft 365, Dynamics 365, and other SaaS suites. Azure ExpressRoute ports integrated with SD-WAN gateways grew 43% year over year, illustrating demand for deterministic cloud paths. Multi-cloud strategies spanning Amazon Web Services, Google Cloud, and Oracle Cloud intensify the need for dynamic path steering. Enterprises report up to 40% faster page loads after deployment, turning network performance into a competitive differentiator.
Hybrid/Remote-work-driven WAN Agility
Remote employees working three or more days off-site stabilized at 38% in 2025, cementing hybrid work as a permanent operating model. SD-WAN platforms equipped with integrated firewalls, intrusion prevention, and secure web gateways enforce uniform security posture from headquarters to home offices. Cisco recorded 31% growth in Meraki SD-WAN subscriptions during 2025 as customers consolidated point tools into unified policies. Zero-trust frameworks that continuously verify user identity, device posture, and application context further amplify adoption, especially in financial services with stringent latency and compliance needs.
Data-Plane Security and Control-Plane Attack Surface
Cloud-hosted SD-WAN controllers centralize orchestration, creating high-value targets. A March 2025 advisory from the U.S. Cybersecurity and Infrastructure Security Agency warned that compromised controllers could reroute traffic, disable encryption, or inject malicious advertisements. Proof-of-concept exploits demonstrated at Black Hat exposed misconfigured APIs granting attackers topology maps and keys. Regulated sectors such as healthcare and defense slowed rollouts pending FedRAMP and HIPAA audits, while adopters segment control-plane traffic and require multi-factor authentication, extending deployment timelines.
Other drivers and restraints analyzed in the detailed report include:
- MPLS Cost-out and Bandwidth Optimisation
- 5G Network Slicing and SD-WAN Convergence
- Shortage of SD-WAN Architecture Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
On-premises deployments held the largest 2025 position, capturing 42.50% of the SD-WAN market. Heavily regulated entities valued appliance-based control planes residing in owned data centers, aligning with GDPR and HIPAA sovereignty rules. Conversely, cloud deployments are forecast to climb at a 25.50% CAGR, propelled by mid-sized enterprises sidestepping capital purchases. The SD-WAN market size for cloud implementations is projected to expand from USD 4.94 billion in 2026 to USD 15.4 billion by 2031, underscoring the pivot toward consumption economics.
Hybrid architecture blends on-premises sovereignty with cloud scalability. VMware reported that 58% of 2025 adopters chose hybrid designs, citing performance-critical workloads that remain on-site while remote branches leverage SaaS-based orchestration[2]. As SASE convergence accelerates, cloud-native controllers infuse security services, nudging even conservative sectors toward hybrid adoption. The SD-WAN market repeatedly illustrates that deployment flexibility, rather than hardware ownership, now dictates architecture decisions.
Solutions retained a 54.60% revenue share in 2025, spanning virtual appliances, perpetual licenses, and orchestration consoles. However, mounting integration demands are shifting budgets toward services, expected to post a 21.16% CAGR. Deloitte surveys showed 47% of enterprises outsourcing at least partial SD-WAN operations, driven by scarce internal expertise.
Professional services cover assessments, design, and proofs of concept, whereas managed services wrap transport, security, and monitoring into predictable OPEX. System integrators such as Accenture and Tata Consultancy Services now run multi-vendor SD-WAN centers of excellence, reducing overlay lock-in fears. As AI-based analytics mature, service providers differentiate by automating policy recommendations, reinforcing the gradual tilt of the SD-WAN market toward lifecycle partnerships.
Geography Analysis
North America controlled 41.20% of 2025 revenue owing to early cloud adoption, abundant broadband, and aggressive SASE experimentation. The U.S. Federal Communications Commission reported that 92% of business addresses accessed gigabit internet in 2025, allowing overlays to aggregate low-cost circuits for MPLS-grade reliability. Financial services hubs in New York and Charlotte, healthcare systems in Boston and Houston, and technology clusters in Silicon Valley collectively drove demand for consolidated network-security stacks. Canadian enterprises confront vast geographic dispersion, while Mexican manufacturers along the U.S. border lean on SD-WAN to support Industry 4.0 initiatives.
Asia-Pacific is forecast to post the fastest expansion at a 29.90% CAGR to 2031, propelled by India's USD 1.2 billion Digital India program, China's intelligent manufacturing push, and ASEAN's e-commerce boom. Standalone 5G cores rolling out across Japan, South Korea, and Australia fuel network slicing pilots that dovetail with SD-WAN orchestration. Emerging markets from Indonesia to Vietnam capitalize on SD-WAN to bypass expensive MPLS footprints and support cross-border digital trade.
Europe's trajectory is shaped by GDPR data-residency mandates that favor hybrid architectures keeping sensitive payloads on-premises. Germany's automotive giants link factories with engineering centers, while U.K. banks integrate SD-WAN and zero-trust to protect high-value trading flows. French and German operators launched bundled managed services in 2025, targeting mid-market firms lacking network personnel. Middle Eastern governments, notably Saudi Arabia and the United Arab Emirates, embed SD-WAN in national digital strategies, whereas South Africa and Nigeria anchor African adoption. In South America, Brazil and Argentina modernize frame relay estates via SD-WAN overlays to sustain e-commerce and hybrid work.
- Cisco Systems, Inc.
- Fortinet, Inc.
- VMware, Inc.
- Aryaka Networks, Inc.
- Versa Networks, Inc.
- Hewlett Packard Enterprise Company
- Nokia Corporation
- Huawei Technologies Co., Ltd.
- Tata Communications Limited
- Telefonaktiebolaget LM Ericsson
- Cato Networks Ltd.
- Palo Alto Networks, Inc.
- Silver Peak Systems, LLC
- Masergy Communications, Inc.
- Juniper Networks, Inc.
- Citrix Systems, Inc.
- Zscaler, Inc.
- Riverbed Technology, LLC
- Check Point Software Technologies Ltd.
- Barracuda Networks, Inc.
- AT&T Inc. (AT&T Business division)
- Telstra Corporation Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-Centric Application Explosion
- 4.2.2 Hybrid/Remote-Work-Driven WAN Agility
- 4.2.3 MPLS Cost-Out and Bandwidth Optimization
- 4.2.4 5G Network Slicing and SD-WAN Convergence
- 4.2.5 AI-Driven Self-Healing Route Optimisation
- 4.2.6 ESG-Linked Carbon-Aware Routing Demand
- 4.3 Market Restraints
- 4.3.1 Data-Plane Security and Control-Plane Attack Surface
- 4.3.2 Shortage of SD-WAN Architecture Talent
- 4.3.3 Proprietary Overlay Lock-In Risks
- 4.3.4 CPE Supply-Chain Bottlenecks
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Mode
- 5.1.1 Premise
- 5.1.2 Cloud
- 5.1.3 Hybrid
- 5.2 By Component
- 5.2.1 Solutions
- 5.2.2 Services
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises
- 5.4 By End-User Industry
- 5.4.1 Healthcare
- 5.4.2 BFSI
- 5.4.3 Retail and Consumer Services
- 5.4.4 Manufacturing
- 5.4.5 Transport and Logistics
- 5.4.6 IT and Telecom
- 5.4.7 Others End-User Industry
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 United Arab Emirates
- 5.5.4.3 Turkey
- 5.5.4.4 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Nigeria
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems, Inc.
- 6.4.2 Fortinet, Inc.
- 6.4.3 VMware, Inc.
- 6.4.4 Aryaka Networks, Inc.
- 6.4.5 Versa Networks, Inc.
- 6.4.6 Hewlett Packard Enterprise Company
- 6.4.7 Nokia Corporation
- 6.4.8 Huawei Technologies Co., Ltd.
- 6.4.9 Tata Communications Limited
- 6.4.10 Telefonaktiebolaget LM Ericsson
- 6.4.11 Cato Networks Ltd.
- 6.4.12 Palo Alto Networks, Inc.
- 6.4.13 Silver Peak Systems, LLC
- 6.4.14 Masergy Communications, Inc.
- 6.4.15 Juniper Networks, Inc.
- 6.4.16 Citrix Systems, Inc.
- 6.4.17 Zscaler, Inc.
- 6.4.18 Riverbed Technology, LLC
- 6.4.19 Check Point Software Technologies Ltd.
- 6.4.20 Barracuda Networks, Inc.
- 6.4.21 AT&T Inc. (AT&T Business division)
- 6.4.22 Telstra Corporation Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

