PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2072910

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2072910
Broiler Feed - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the broiler feed market size is anticipated to grow from USD 99.67 billion in 2025 to USD 102.94 billion in 2026 and is forecast to reach USD 120.95 billion by 2031 at 3.28% CAGR over 2026-2031.
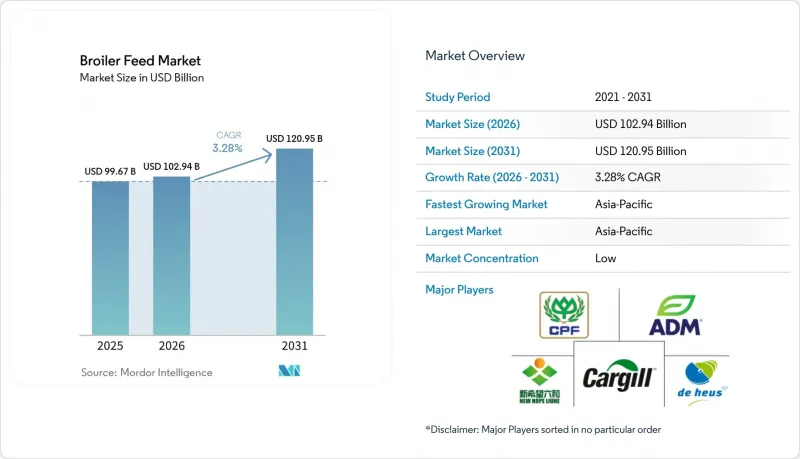
This report is Segmented by Feed Phase (Starter, Grower, and Finisher), by Form (Pellets, Crumbles, Mash, and Others), by Ingredient Type (Cereals, Oilseed Meal, Molasses, Fish Oil and Fish Meal, Additives, and Other Ingredient Types), and by Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Broiler Feed Market Trends and Insights
Rising Poultry Meat Consumption and Protein Affordability
Poultry meat is expanding its role in global diets, which directly supports demand for broiler feed. The Organization for Economic Co-operation and Development and the Food and Agriculture Organization projected that poultry will account for 62% of additional global meat consumption through 2034, with much of that increase concentrated in developing regions. Poultry also remains one of the more affordable animal proteins, which helps sustain consumption when household food budgets come under pressure. Affordability matters for the broiler feed market because stable meat demand protects feed volumes, even when other proteins face a sharper substitution risk. MHP SE reported nine-month 2025 revenue of USD 2.64 billion, representing a 16% year-on-year increase. The growth was supported by strong poultry demand, stable market pricing, and the consolidation of Spanish poultry producer Grupo UVESA. This trend supports sustained demand for broiler feed, as growing poultry output and capacity expansion require consistent increases in commercial feed consumption.
Commercial Broiler Farming Expansion and Feed Outsourcing
The broiler feed market grows more steadily when poultry production shifts from backyard systems to commercial and contract-based farming. Larger broiler operations depend on standardized compound feed because growth targets, flock uniformity, and processor requirements leave little room for inconsistent farm mixing. Once growers move to integrated or contract models, they usually remain tied to formal feed supply because financing, veterinary support, and buyer agreements are tied to that system. ForFarmers N.V. formed ForFarmers Polska in 2026 by combining feed production with poultry farming and processing, demonstrating how feed is being drawn deeper into organized poultry chains. Koninklijke De Heus Voeders B.V. also widened its position in Asia in March 2026 through the acquisition of CJ Feed and Care, adding 17 feed mills and extending its reach in major poultry-producing markets. These developments support the view that the broiler feed market benefits most when poultry farming becomes larger, more formal, and more dependent on outsourced feed.
European Union Deforestation Regulation (EUDR)-Linked Soy Traceability Premiums
The European Union Deforestation Regulation (EUDR) adds a new compliance layer to the broiler feed market, especially for supply chains with heavy soybean meal exposure. The regulation mandates plot-level traceability for covered commodities and products, with large and medium-sized operators required to comply by December 30, 2026. Non-compliance can result in penalties of up to 4% of an operator's annual European Union turnover. The European Feed Manufacturers' Federation reported disruption risk in the soy trade due to compliance systems that were still not fully ready, creating a tighter, less flexible sourcing environment. These requirements increase documentation costs for exporters and compounders that serve Europe-linked demand. They also make soy procurement less straightforward for mills that lack strong traceability systems. In practical terms, this raises sourcing premiums and encourages the broiler feed market to examine more diversified protein inputs.
Other drivers and restraints analyzed in the detailed report include:
- Higher Focus on Feed Conversion and Cost Efficiency
- Shift toward Antibiotic-Free and Additive-Led Feed Programs
- Climate-Driven Mycotoxin and Ingredient-Quality Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The largest feed phase segment was finisher, which held 42.6% of the broiler feed market share in 2025. This lead reflects the high feed intake during the final growth window, when producers focus on carcass yield and feed efficiency. Commercial broiler systems place strong emphasis on finisher diets because the last stage directly affects saleable output and processing returns. The fastest-growing feed phase segment is the starter, projected to grow at a 4.1% CAGR during 2026-2031. That faster pace shows that more producers now treat early-life nutrition as a performance foundation rather than a basic opening ration.
Starter diets are gaining more attention because gut development, immunity, and nutrient uptake are set early in the production cycle. The grower phase still plays a key balancing role because it connects early development with the high-volume finisher stage. Research published in Poultry Science in 2026 found that B-mannanase supplementation in reduced-energy broiler diets improved nutrient utilization and growth performance, highlighting continued industry interest in enzyme-enabled feed reformulation strategies to maintain productivity while reducing feed costs. This means value growth in the broiler feed market is not limited to higher volumes, but also reflects more precise feeding decisions across each phase. Cooperatie Koninklijke Agrifirm U.A. agreed to acquire Hamlet Protein in March 2026, underscoring that early-life and specialty nutrition remain attractive areas for commercial expansion.
Complete Report Scope:
- By Feed Phase
- Starter
- Grower
- Finisher
- By Form
- Pellets
- Crumbles
- Mash
- Others
- By Ingredient Type
- Cereals
- Oilseed Meal
- Molasses
- Fish Oil and Fish Meal
- Additives
- Other Ingredient Types
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- Thailand
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific was the largest regional segment with 46.5% of the broiler feed market share in 2025, and it is also the fastest regional segment with a projected 4.3% CAGR during 2026-2031. This position reflects strong poultry demand, rising commercial production, and the broad affordability of chicken across many large population centers. The Organization for Economic Co-operation and Development and the Food and Agriculture Organization outlook support this direction, as much of the added poultry consumption through 2034 is projected to come from Asia and other developing regions. Koninklijke De Heus Voeders B.V. has expanded its Asian platform in March 2026 through CJ Feed and Care, reinforcing that the broiler feed market in the region remains attractive for long-term investment.
South America remains an important region in the broiler feed market because poultry production and feed demand are closely connected to grain and oilseed availability. Brazil remains especially influential because it combines a strong poultry base with a major role in agricultural raw materials tied to feed formulation. Cargill, Incorporated, announced in 2025 a binding offer to acquire Mig-Plus in Brazil, indicating that nutrition companies still see room to deepen their footprint in major producing markets. North America is more mature by volume, so competition there centers more on efficiency, formulation upgrades, and additive performance than on large jumps in feed tonnage. This means the broiler feed market in the Americas combines scale-driven demand in South America with performance-led differentiation in North America.
Europe remains a lower-growth but higher-compliance part of the broiler feed market. The European Union Deforestation Regulation is pushing feed manufacturers to build more traceable soy sourcing systems before the December 30, 2026, deadline. Africa and the Middle East show stronger room for expansion because poultry remains a practical protein source in markets with fast population growth and changing food demand patterns. Hotter climate conditions also make functional and heat-support feed solutions more relevant in these regions, especially where flock performance is exposed to sustained temperature stress. As a result, the broiler feed market exhibits distinct regional priorities, with Asia-Pacific emphasizing production scale, Europe focusing on regulatory compliance, and Africa and the Middle East prioritizing market access, supply chain resilience, and industry formalization.
- New Hope Liuhe Co., Ltd.
- Charoen Pokphand Foods Public Company Limited
- Cargill, Incorporated
- Archer Daniels Midland Company
- Land O'Lakes, Inc.
- Koninklijke De Heus Voeders B.V.
- Guangdong Haid Group Co., Ltd.
- Nutreco N.V.
- Japfa Ltd.
- Wen's Foodstuff Group Co., Ltd.
- AB Agri Limited
- ForFarmers N.V.
- Cooperatie Koninklijke Agrifirm U.A.
- Godrej Agrovet Limited
- Suguna Foods Private Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising poultry meat consumption and protein affordability
- 4.2.2 Commercial broiler farming expansion and feed outsourcing
- 4.2.3 Higher focus on feed conversion and cost efficiency
- 4.2.4 Shift toward antibiotic-free and additive-led feed programs
- 4.2.5 AI-enabled precision nutrition in broiler feed formulation
- 4.2.6 Heat-stress mitigation demand for functional feed
- 4.3 Market Restraints
- 4.3.1 Corn and soybean meal price volatility
- 4.3.2 Tighter antimicrobial-use regulation
- 4.3.3 European Union Deforestation Regulation(EUDR)-linked soy traceability premiums
- 4.3.4 Climate-driven mycotoxin and ingredient-quality risk
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Feed Phase
- 5.1.1 Starter
- 5.1.2 Grower
- 5.1.3 Finisher
- 5.2 By Form
- 5.2.1 Pellets
- 5.2.2 Crumbles
- 5.2.3 Mash
- 5.2.4 Others
- 5.3 By Ingredient Type
- 5.3.1 Cereals
- 5.3.2 Oilseed Meal
- 5.3.3 Molasses
- 5.3.4 Fish Oil and Fish Meal
- 5.3.5 Additives
- 5.3.6 Other Ingredient Types
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 Australia
- 5.4.4.5 Indonesia
- 5.4.4.6 Thailand
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 New Hope Liuhe Co., Ltd.
- 6.4.2 Charoen Pokphand Foods Public Company Limited
- 6.4.3 Cargill, Incorporated
- 6.4.4 Archer Daniels Midland Company
- 6.4.5 Land O'Lakes, Inc.
- 6.4.6 Koninklijke De Heus Voeders B.V.
- 6.4.7 Guangdong Haid Group Co., Ltd.
- 6.4.8 Nutreco N.V.
- 6.4.9 Japfa Ltd.
- 6.4.10 Wen's Foodstuff Group Co., Ltd.
- 6.4.11 AB Agri Limited
- 6.4.12 ForFarmers N.V.
- 6.4.13 Cooperatie Koninklijke Agrifirm U.A.
- 6.4.14 Godrej Agrovet Limited
- 6.4.15 Suguna Foods Private Limited
7 Market Opportunities and Future Outlook

