PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2097306

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2097306
Edge AI Accelerators - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2025 - 2030)
According to Mordor Intelligence, the edge AI accelerators market size stood at USD 7.45 billion in 2024 and is projected to register a 31% CAGR, lifting the value to USD 35.75 billion by 2030.
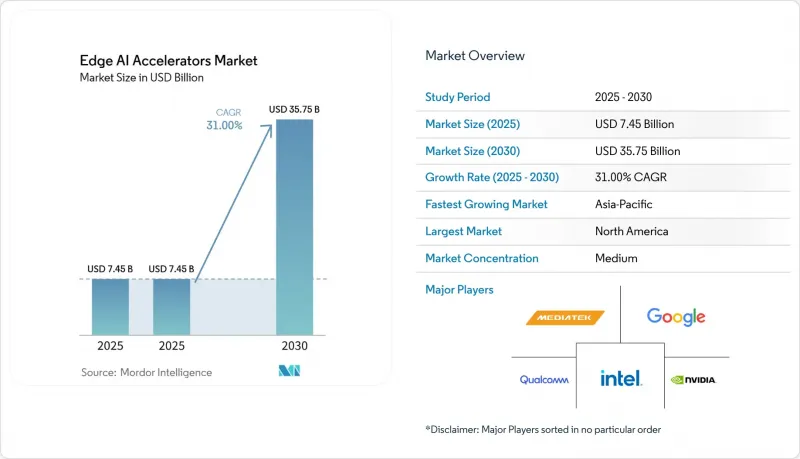
This report is Segmented by Hardware Type (ASIC, GPU, FPGA, and More), Power Consumption Envelope (Less Than 1W, 1-3W, and More), Form Factor (System-On-Chip, Module/Board, PCIe/Edge Card, USB/Stick Accelerator), Application (Computer Vision, Speech and NLP, and More), End-User Industry (Consumer Electronics, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Edge AI Accelerators Market Trends and Insights
Proliferation of Smart Cameras and IoT Devices
Mass deployment of intelligent cameras in factories, traffic systems, and retail spaces is pushing inference to the edge. Sony's IMX500 embeds a DSP inside the image sensor so frames are interpreted locally, slashing network traffic by up to 90% and shrinking decision latency below 10 ms. Multimodal references are rising as microphones and mm-wave radars piggyback on the same edge board, forcing accelerators to juggle vision, audio, and time-series workloads without exceeding 5-10 W.
Data-Privacy Regulations Driving On-Device Inference
The EU AI Act joins HIPAA and GDPR in demanding that patient, financial, and defense data stay on-premise. Edge-optimized silicon lets hospital imaging suites, bank branches, and municipal surveillance networks comply without sacrificing algorithmic sophistication. EdgeRunner AI ships air-gapped assistants that fine-tune large language models locally, eliminating cloud exposure and meeting zero-trust mandates for classified workloads.
Fragmented Hardware-Software Ecosystem Lengthens Integration Cycles
The Edge AI Accelerators market wrestles with APIs split across CUDA, OpenVINO, TVM, and vendor-specific SDKs. Enterprises spinning up proofs of concept on a USB stick often face multi-month rewrites when migrating to a mezzanine card. Absence of uniform benchmarking complicates ROI sign-off, delaying volume orders, especially for mid-market OEMs with lean engineering staffs. Cross-vendor ONNX compliance is improving, yet device-level power-gating tactics still require hand-tuned kernels that lock customers into single-supplier roadmaps.
Other drivers and restraints analyzed in the detailed report include:
- Falling USD/TOPS and Improved Performance-Per-Watt of Edge ASICs
- Edge-Native Foundation Models for Multimodal AI
- Thermal Management Limits in Fan-Less Designs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ASIC devices captured 47.2% Edge AI Accelerators market share in 2024, confirming a pivot from general-purpose compute toward domain-tuned logic that drives 4-7X gains in TOPS-per-watt. The segment promises a 25.4% CAGR to 2030 as design starts migrate to 3 nm where SRAM proximity slashes DRAM fetch penalties. GPUs remain vital in software-first prototyping venues, yet they cede volume deployments to inference-only cores that deliver deterministic latency. FPGAs keep a niche in aerospace where reconfigurability outweighs unit cost. Neuromorphic chips such as Intel Loihi 2 run constraint-satisfaction workloads at 37X lower energy than CPUs.
Performance-densities favor ASICs for surveillance NVRs, smart-factory PLCs, and in-cab driver monitoring. Meanwhile, the Edge AI Accelerators market size attached to brain-inspired silicon forecasts a 34% CAGR because event-driven spiking networks fire only when a signal arrives, trimming idle current to microwatts. ASIC roadmaps increasingly bundle secure elements and LPDDR-in-package to simplify system validation. As automotive Tier 1s lock multi-year supply agreements, volume guarantees give fabs the incentive to fast-track functional-safety certification at the mask level.
The 5-10 W bracket held 38.1% of Edge AI Accelerators market size in 2024, serving fanless DIN-rail controllers and city-pole computer-vision nodes. Shipments within the <1 W category are projected to expand 28.7% CAGR through 2030, reaching nearly one-quarter of unit volume as coin-cell wearables, tire-pressure sensors, and smart locks add always-on intelligence.
Neuromorphic and processing-in-memory chips headline this ultra-low-power wave, using event-based logic and analog compute to shed refresh cycles. PIMIC's Listen VL130 reduces DSP workloads by routing MAC operations inside SRAM, cutting power 10X over discrete MPU-DSP combos. Edge-optimized BMS algorithms running on 1-3 W NPUs now prolong e-scooter battery range by 12%. Higher envelopes above 10 W persist in rack-mount telco edge clusters where full-precision generative models need >100 TOPS and AC feed lines are available.
Complete Report Scope:
- By Hardware Type
- ASIC
- GPU
- FPGA
- VPU / NPU
- Heterogeneous SoC
- By Power Consumption Envelope
- Less Than 1 W
- 1-3 W
- 3-5 W
- 5-10 W
- 10-20 W
- More Than 20 W
- By Form Factor
- System-on-Chip
- Module / Board
- PCIe / Edge Card
- USB / Stick Accelerator
- By Application
- Computer Vision
- Speech and Natural-Language Processing
- Predictive Maintenance / Anomaly Detection
- Autonomous Navigation and Control
- Sensor Fusion and Data Aggregation
- By End-User Industry
- Consumer Electronics and Wearables
- Automotive and Transportation
- Industrial and Manufacturing
- Smart Cities and Public Safety
- Healthcare and Life Sciences
- Aerospace and Defense
- Agriculture
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 40% of 2024 revenue thanks to early adopter ecosystems in Silicon Valley automotive labs and hyperscaler R&D centers. Defense directives on zero-trust and on-shore silicon sourcing further lock government contracts into domestic suppliers.
Asia-Pacific's 29.88% CAGR is propelled by state grants and vertically integrated ODMs that migrate smartphones, scooters, and CCTV cameras into AI-enabled variants nearly in lock-step with node shrinks. TSMC already controls 62% global foundry share, underwriting a stable supply of 3 nm wafers for edge ASIC startups while Japanese fabless vendors like Socionext leverage local automotive OEM demand to seed regional clusters.
Europe emphasizes compliance over volume, with GDPR and the AI Act mandating on-device inference for sensitive data. Automakers in Germany, France, and Sweden are frontloading ASIC design to guarantee traceability and functional-safety proofs. Emerging deployments in the Middle East use edge AI traffic cameras to conserve scarce water by routing vehicles away from flooded roads. South America pilots smart-agriculture drones that infer crop stress offline to accommodate patchy rural networks, gradually widening the Edge AI Accelerators market footprint.
- NVIDIA Corporation
- Intel Corporation
- Qualcomm Technologies Inc.
- Google LLC
- MediaTek Inc.
- Advanced Micro Devices (AMD)
- NXP Semiconductors N.V.
- Samsung Electronics Co. Ltd.
- Arm Ltd.
- Huawei Technologies Co. Ltd.
- Texas Instruments Inc.
- Lattice Semiconductor Corp.
- Hailo Technologies Ltd.
- Mythic Inc.
- Blaize Inc.
- BrainChip Holdings Ltd.
- Sima.AI
- Esperanto Technologies
- Tenstorrent Inc.
- Horizon Robotics
- EdgeQ Inc.
- Graphcore Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of smart cameras and IoT devices
- 4.2.2 Data-privacy regulations driving on-device inference
- 4.2.3 Falling USD/TOPS and improved performance-per-watt of edge ASICs
- 4.2.4 Bandwidth and latency constraints in autonomous systems
- 4.2.5 Emergence of TinyML frameworks on micro-controllers
- 4.2.6 Edge-native foundation models for multimodal AI
- 4.3 Market Restraints
- 4.3.1 Fragmented h/w-s/w ecosystem lengthens integration cycles
- 4.3.2 Thermal management limits in fan-less designs
- 4.3.3 Higher unit economics vs. cloud GPU at scale
- 4.3.4 Lack of standardized on-device AI benchmarks
- 4.4 Technological Outlook
- 4.5 Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Porters Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Hardware Type
- 5.1.1 ASIC
- 5.1.2 GPU
- 5.1.3 FPGA
- 5.1.4 VPU / NPU
- 5.1.5 Heterogeneous SoC
- 5.2 By Power Consumption Envelope
- 5.2.1 Less Than 1 W
- 5.2.2 1-3 W
- 5.2.3 3-5 W
- 5.2.4 5-10 W
- 5.2.5 10-20 W
- 5.2.6 More Than 20 W
- 5.3 By Form Factor
- 5.3.1 System-on-Chip
- 5.3.2 Module / Board
- 5.3.3 PCIe / Edge Card
- 5.3.4 USB / Stick Accelerator
- 5.4 By Application
- 5.4.1 Computer Vision
- 5.4.2 Speech and Natural-Language Processing
- 5.4.3 Predictive Maintenance / Anomaly Detection
- 5.4.4 Autonomous Navigation and Control
- 5.4.5 Sensor Fusion and Data Aggregation
- 5.5 By End-User Industry
- 5.5.1 Consumer Electronics and Wearables
- 5.5.2 Automotive and Transportation
- 5.5.3 Industrial and Manufacturing
- 5.5.4 Smart Cities and Public Safety
- 5.5.5 Healthcare and Life Sciences
- 5.5.6 Aerospace and Defense
- 5.5.7 Agriculture
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 ASEAN
- 5.6.4.6 Australia and New Zealand
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 UAE
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Israel
- 5.6.5.1.5 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 NVIDIA Corporation
- 6.4.2 Intel Corporation
- 6.4.3 Qualcomm Technologies Inc.
- 6.4.4 Google LLC
- 6.4.5 MediaTek Inc.
- 6.4.6 Advanced Micro Devices (AMD)
- 6.4.7 NXP Semiconductors N.V.
- 6.4.8 Samsung Electronics Co. Ltd.
- 6.4.9 Arm Ltd.
- 6.4.10 Huawei Technologies Co. Ltd.
- 6.4.11 Texas Instruments Inc.
- 6.4.12 Lattice Semiconductor Corp.
- 6.4.13 Hailo Technologies Ltd.
- 6.4.14 Mythic Inc.
- 6.4.15 Blaize Inc.
- 6.4.16 BrainChip Holdings Ltd.
- 6.4.17 Sima.ai
- 6.4.18 Esperanto Technologies
- 6.4.19 Tenstorrent Inc.
- 6.4.20 Horizon Robotics
- 6.4.21 EdgeQ Inc.
- 6.4.22 Graphcore Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

