PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2099825

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2099825
Hemp-based Foods - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hemp-based foods market size was valued at USD 7.13 billion in 2025 and is estimated to grow from USD 7.89 billion in 2026 to reach USD 13.06 billion by 2031, at a CAGR of 10.61% during the forecast period (2026-2031).
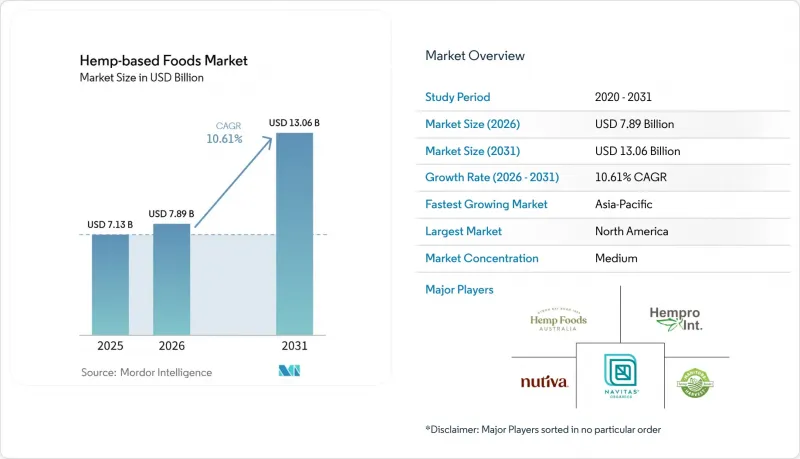
This report is Segmented by Product Type (Hemp Seed Oil, Hemp Protein Powder, and More), Category (Organic, Conventional), Distribution Channel (Supermarket and Hypermarket Stores, and More), Application (Bakery and Confectionery, Beverages, Dairy Alternatives, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hemp-based Foods Market Trends and Insights
Rising Demand for Plant-Based Protein Alternatives
The hemp-based foods market is benefiting from the wider shift toward plant-based diets across mature and emerging economies. Manufacturers are also seeking alternatives as soy and corn protein prices faced volatility after climate-related harvest disruptions in 2024. Hemp protein contains all essential amino acids, giving it a stronger nutritional profile than some other plant proteins used in mainstream formulations. In April 2025, Victory Hemp Foods commissioned North America's largest hemp heart protein and oil processing line, designed to support sourcing from more than 20,000 acres of hemp by 2030 while generating USD 18 million annually for U.S. farmers.
Expanding Clean-Label and Allergen-Free Food Claims
Clean-label demand has become a mainstream product requirement, supporting the expansion of the hemp-based foods market into wider retail channels. Hemp ingredients enable shorter ingredient lists and help brands avoid allergen concerns linked to oats, nuts, and other plant-based inputs. In its June 2025 retail launch, Manitoba Harvest's Hemp+ range combined Regenerative Organic Certified, Non-GMO Project Verified, Kosher, and Vegan positioning, strengthening its shelf appeal in premium channels. Hemp also helps manufacturers support multiple claims within a single product, reducing the need for separate claim-based product lines.
Regulatory Fragmentation Across Food-Grade Hemp Markets
The hemp-based foods market continues to face uneven regulations across countries, creating barriers for companies seeking regional scale. Traditional hemp seed, hemp seed oil, and hemp seed protein have clearer acceptance in some markets, while adjacent formats remain exposed to policy uncertainty. This limits product planning, raises compliance costs, delays investment, and slows commercial rollouts. In the United States, ongoing policy discussions around consumable hemp products continue to create uncertainty for some formats, while in Europe, Novel Food requirements continue to influence innovation pathways.
Other drivers and restraints analyzed in the detailed report include:
- Retail Mainstreaming of Hemp Ingredients Beyond Specialty Channels
- Product Innovation in Hemp-Based Functional Foods
- Higher Ingredient and Processing Costs Versus Commodity Proteins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hemp Seed Oil hold 37.65% of product revenue in 2025, making it the largest product category in the hemp-based foods market. Hemp Protein Powder is the fastest-growing product type and is projected to expand at an 11.93% CAGR through 2031. The market continues to rely on established seed-oil consumption, while growth is shifting toward protein-led formulations. Manufacturers use Hemp Seed Oil in culinary products, nutraceutical formats, and packaged food ingredient systems, supported by its omega fatty acid profile, cold-pressed positioning, and non-GMO appeal.
Hemp Protein Powder is gaining importance as a differentiated ingredient rather than a basic plant protein substitute. Demand remains strongest in sports nutrition, functional beverages, and meal replacement products, where protein quality and ingredient origin are key purchase factors. Whole Hemp Seed and Hulled Hemp Seed continue to support demand in granola, smoothie toppings, trail mixes, and seed-based snacks. Tilray Brands launched The Humble Seed Whole Wheat Protein Crackers in August 2025, offering 5 g of plant-based protein per 30 g serving through select Whole Foods Market stores.
Organic accounted for 65.23% of category revenue in 2025, giving it the largest share of the hemp-based foods market. It is also the fastest-growing category, with a 12.67% CAGR projected through 2031. This strong position reflects the focus of retail buyers, premium shelves, and product innovation budgets on certified products. Many natural and specialty retailers treat organic certification as a baseline requirement for hemp-based listings, giving certified brands a structural advantage.
Certified superfood portfolios are attracting investor interest as durable growth platforms. Laird Superfood completed its acquisition of Navitas LLC in March 2026 for USD 38.5 million, supported by a concurrent USD 50 million investment from Nexus Capital Management. Regenerative Organic Certified positioning is adding another premium layer above baseline organic status, especially for brands focused on soil health and sustainability claims. Conventional products remain relevant in value-focused and food-service channels, but premium shelf expansion and new product investment continue to center on certified lines.
Complete Report Scope:
- By Product Type
- Hemp Seed Oil
- Hemp Protein Powder
- Whole Hemp Seed
- Hulled Hemp Seed
- Other Hemp Food Products
- By Category
- Organic
- Conventional
- By Distribution Channel
- Supermarket and Hypermarket Stores
- Convenience Stores
- Specialty Stores
- Online Retail
- Other Distribution Channels
- By Application
- Bakery and Confectionery
- Beverages
- Dairy Alternatives
- Snacks and Cereals
- Nutraceuticals and Dietary Supplements
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted 40.56% of global revenue in 2025, securing the largest regional position in the hemp-based foods market. The region benefits from strong retail infrastructure, a developed hemp supply chain, and higher mainstream awareness of hemp nutrition than other markets. The United States remains the primary demand center, with hemp products increasingly available across broad retail networks, while Canada strengthens the regional market through its established cultivation base and seed-to-shelf supply chain links.
Europe remains the second-largest region, supported by demand for traditional hemp food ingredients such as seeds, oil, and protein. However, a mixed regulatory environment across member states continues to slow broader ingredient innovation and shifts commercial focus toward accepted product formats. Organic trade flows also support the region, and U.S.-EU organic equivalence enables easier movement of certified products across the Atlantic.
Asia-Pacific is the fastest-growing region and is projected to expand at a 13.56% CAGR through 2031. China and India are leading this growth from a smaller base, supported by rising disposable income, broader interest in plant-based diets, and increasing digital access to wellness products. Japan remains a steady market, while South Korea and Australia offer mid-tier growth potential; South America, the Middle East, and Africa remain earlier-stage areas with emerging opportunities through urban health-food retail and organized grocery expansion.
- Agropro
- Bioriginal Food and Science Corp.
- Canada Hemp Foods Ltd.
- Canah International S.R.L.
- Elixinol Wellness Limited
- Fresh Hemp Foods Ltd.
- GFR Ingredients Inc.
- Good Hemp Ltd.
- Hemp Factory GmbH
- Hemp Foods Australia Pty Ltd.
- Hemp Oil Canada Corp.
- Hempco Food and Fiber Inc.
- Hempro International GmbH
- Liaoning Qiaopai Biotech Co., Ltd.
- Manitoba Harvest Inc.
- Naturally Splendid Enterprises Ltd.
- Navitas Organics, LLC
- Nutiva Inc.
- Tilray Brands, Inc.
- Yunnan Hua Fang Industrial Hemp Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Plant-Based Protein Alternatives
- 4.2.2 Expanding Clean-Label and Allergen-Free Food Preference
- 4.2.3 Retail Mainstreaming of Hemp Ingredients Beyond Health Stores
- 4.2.4 Product Innovation in Hemp-Based Functional Foods and Beverages
- 4.2.5 Volatility in Conventional Protein Supply Chains, Supporting Hemp Diversification
- 4.2.6 Traceability-Driven Premiumization of Organic Hemp Ingredients
- 4.3 Market Restraints
- 4.3.1 Regulatory Fragmentation Across Food-Grade Hemp Thresholds
- 4.3.2 Consumer Confusion Between Hemp Foods and Cannabis-Derived Products
- 4.3.3 Higher Ingredient and Processing Costs Versus Mainstream Seeds and Grains
- 4.3.4 Limited Food-Grade Processing Capacity and Cold-Chain/Storage Constraints in Some Regions
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants, Analysis
- 4.7.2 Bargaining Power of Suppliers, Analysis
- 4.7.3 Bargaining Power of Buyers, Analysis
- 4.7.4 Threat of Substitutes, Analysis
- 4.7.5 Industry Rivalry, Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Hemp Seed Oil
- 5.1.2 Hemp Protein Powder
- 5.1.3 Whole Hemp Seed
- 5.1.4 Hulled Hemp Seed
- 5.1.5 Other Hemp Food Products
- 5.2 By Category
- 5.2.1 Organic
- 5.2.2 Conventional
- 5.3 By Distribution Channel
- 5.3.1 Supermarket and Hypermarket Stores
- 5.3.2 Convenience Stores
- 5.3.3 Specialty Stores
- 5.3.4 Online Retail
- 5.3.5 Other Distribution Channels
- 5.4 By Application
- 5.4.1 Bakery and Confectionery
- 5.4.2 Beverages
- 5.4.3 Dairy Alternatives
- 5.4.4 Snacks and Cereals
- 5.4.5 Nutraceuticals and Dietary Supplements
- 5.4.6 Other Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Agropro
- 6.3.2 Bioriginal Food and Science Corp.
- 6.3.3 Canada Hemp Foods Ltd.
- 6.3.4 Canah International S.R.L.
- 6.3.5 Elixinol Wellness Limited
- 6.3.6 Fresh Hemp Foods Ltd.
- 6.3.7 GFR Ingredients Inc.
- 6.3.8 Good Hemp Ltd.
- 6.3.9 Hemp Factory GmbH
- 6.3.10 Hemp Foods Australia Pty Ltd.
- 6.3.11 Hemp Oil Canada Corp.
- 6.3.12 Hempco Food and Fiber Inc.
- 6.3.13 Hempro International GmbH
- 6.3.14 Liaoning Qiaopai Biotech Co., Ltd.
- 6.3.15 Manitoba Harvest Inc.
- 6.3.16 Naturally Splendid Enterprises Ltd.
- 6.3.17 Navitas Organics, LLC
- 6.3.18 Nutiva Inc.
- 6.3.19 Tilray Brands, Inc.
- 6.3.20 Yunnan Hua Fang Industrial Hemp Co., Ltd.
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

