PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100015

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100015
Hepatitis C - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hepatitis c market size is expected to grow from USD 15.26 billion in 2025 to USD 15.83 billion in 2026 and is forecast to reach USD 18.96 billion by 2031 at 3.69% CAGR over 2026-2031.
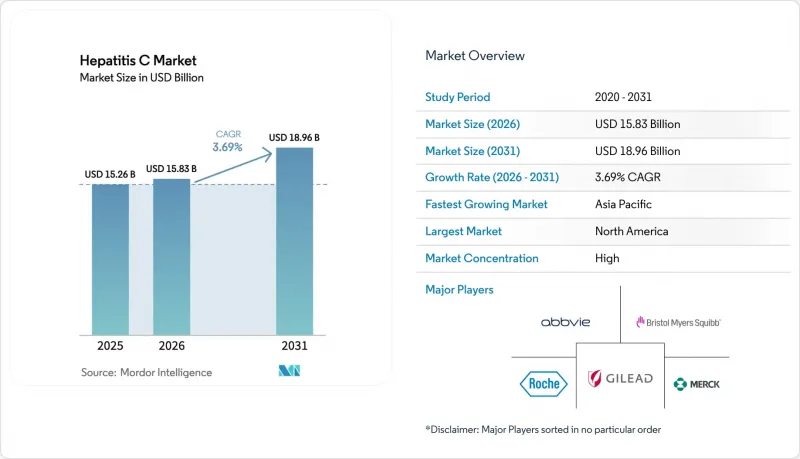
This report is Segmented by Component (Diagnosis [Blood Tests and More] and Treatment [DAAs and More]), Age-Group (Below 18, 18 - 45, Above 45), Channel (Hospitals & Clinics, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hepatitis C Market Trends and Insights
Rising HCV Prevalence & Mandatory Universal Screening
Universal one-time or birth-cohort screening replaces risk-based approaches and uncovers hidden cases in rural and suburban populations. US Centers for Disease Control modelling shows that only one-third of diagnosed Americans achieved virologic cure between 2013 and 2022, underscoring latent demand for streamlined linkage-to-care pathways. Whole-population surveys in Europe reveal prevalence pockets above 1% among individuals born between 1965 and 1985, far exceeding prior estimates. Countries meeting the World Health Organization's 90% diagnosis target demonstrate markedly steeper treatment adoption curves than nations still at sub-30% awareness levels. As more public health agencies set mandatory screening in primary-care and emergency-department settings, diagnostic volumes continue to rise even while the chronic prevalence rate falls.
Government-Funded National Elimination Initiatives
Egypt's national elimination programme treated over 4 million citizens and reached 87% cure, validating large-scale, publicly financed models. Australia, Canada, and Spain now provide unlimited DAA access through subscription or capped-payment contracts that align payer incentives with elimination targets. In the United States, a proposed USD 11 billion federal fund would cover the uninsured population and support state Medicaid treatment expansion, potentially adding 400,000 annual treatment starts by 2027. These schemes lock in predictable volumes, allowing manufacturers to exchange price concessions for certainty while accelerating progress toward the 2030 elimination milestone.
High Branded-Therapy Cost & Reimbursement Gaps
Course prices for branded pan-genotypic DAAs remain near USD 24,000 in many high-income markets, leading to restrictive payer criteria based on fibrosis stage or sobriety requirements. Out-of-pocket cost exposure discourages treatment among uninsured or under-insured populations, even where community health centres offer low-cost screening. Generic sofosbuvir/velpatasvir is available for under USD 100 in India, Pakistan, and Egypt, yet patent claws and exclusivity clauses keep list prices elevated elsewhere. The cumulative spend, including confirmatory RNA tests, fibrosis staging, and specialist visits, can exceed USD 30,000 per person, hampering uptake despite proven cost-effectiveness.
Other drivers and restraints analyzed in the detailed report include:
- Advances in Point-of-Care and Molecular Diagnostics
- Superior Cure Rates & Shorter Regimens of DAAs
- Large undiagnosed pool & social stigma
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Treatment accounted for 87.58% of the Hepatitis C market share in 2025, reflecting the high unit value of DAAs that sell at premium prices in many countries. Direct-acting antivirals anchored by sofosbuvir combinations generated the bulk of segment turnover, with Harvoni and Epclusa alone surpassing USD 9 billion in global sales in 2024. Pegylated-interferon/ribavirin now constitutes a single-digit niche for interferon-eligible patients, while immunomodulatory adjuncts are under investigation for non-responders. The Hepatitis C market size for treatment could reach USD 16.85 billion by 2031 if current reimbursement frameworks hold.
Diagnosis, although smaller, is rising at a 5.62% CAGR as universal screening, antenatal testing, and prison-based programmes increase test volumes. Point-of-care antibody assays, reflex RNA cartridges, and high-throughput NAAT platforms dominate procurement tenders in Asia-Pacific and Latin America. Molecular sub-typing and resistance sequencing deliver incremental revenue by guiding personalized therapy. An integrated "test-to-treat" workflow retains patients and extends value capture across both component categories, mitigating treatment-segment contraction caused by shrinking prevalence.
Complete Report Scope:
- By Component
- Diagnosis
- Blood Tests
- Rapid/POC Tests
- Molecular (PCR, NAAT)
- Sequencing-based Genotyping
- Others
- Treatment
- Direct-Acting Antivirals (DAAs)
- Pegylated Interferon + Ribavirin
- Adjunct Immunomodulators
- Diagnosis
- By Age Group
- Below 18
- 18 - 45
- Above 45
- By Channel
- Hospitals & Clinics
- Diagnostic Laboratories
- Community Pharmacies & Retail Clinics
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 39.76% of the Hepatitis C market share in 2025, powered by comprehensive screening mandates, premium branded pricing, and broad Medicaid coverage. However, growth moderates to a 3.28% CAGR as prevalence declines in previously untreated baby boomers. The proposed federal elimination fund, if enacted, could still add large treatment volumes by underwriting uninsured care. Canada aligns drug pricing with health-technology assessments, capping list prices, while Mexico's Seguro Popular programme is beginning to subsidise locally manufactured generics, anchoring volume growth despite lower per-patient spend.
Europe accounts for a sizeable share and shows a 3.01% CAGR through 2031. Joint procurement initiatives under the Beneluxa coalition and national subscription deals in Spain and Portugal have trimmed treatment course prices by 45% since 2022. The United Kingdom reports a 51.6% drop in chronic infection prevalence after integrating whole-genome surveillance with direct community outreach. Eastern European nations, backed by Global Fund transition grants, are scaling harm-reduction, testing, and treatment packages among people who inject drugs, unlocking additional diagnostic volumes.
Asia-Pacific is the fastest-growing territory, expanding at 4.83% CAGR. China's volume-based procurement brought down the sofosbuvir/velpatasvir price ceiling by 68% in the 2024 tender round, catalysing provincial bulk-buy orders. India's National Viral Hepatitis Control Programme finances generics at under USD 100 per course and reimbursed more than 550,000 treatments in 2024. Malaysia, Thailand, and Vietnam deploy the "Netflix" capped-price model, facilitating mass campaigns among high-burden populations. The Hepatitis C market share derived from Asia-Pacific is expected to climb above 28.64% by 2031, powered by aggressive elimination goals paired with domestic manufacturing.
- Abbott Laboratories
- Abbvie
- Alnylam Pharmaceuticals
- Arbutus Biopharma Corporation
- Assembly Biosciences, Inc.
- Atea Pharmaceuticals
- Bayer
- Bristol-Myers Squibb
- Cipla
- Dr. Reddy's Laboratories
- Enanta Pharmaceuticals, Inc.
- Roche
- Gilead Sciences
- Grifols
- GlaxoSmithKline
- Johnson & Johnson
- Merck
- Novartis
- Orasure Technologies
- QIAGEN
- Sun Pharmaceuticals Industries
- Thermo Fisher Scientific
- Viatris
- Vir Biotechnology, Inc.
- Zydus Lifesciences Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising HCV Prevalence & Mandatory Universal Screening
- 4.2.2 Government-Funded National Elimination Initiatives
- 4.2.3 Advances in Point-of-Care and Molecular Diagnostics
- 4.2.4 Superior Cure Rates & Shorter Regimens of DAAs
- 4.2.5 Pharmacy-Led Decentralized "Test-To-Treat" Models
- 4.2.6 AI-Guided Personalized DAA Regimen Optimization
- 4.3 Market Restraints
- 4.3.1 High Branded-Therapy Cost & Reimbursement Gaps
- 4.3.2 Large Undiagnosed Pool & Social Stigma
- 4.3.3 Specialist-Prescription & Retreatment Restrictions
- 4.3.4 Emerging Antiviral-Resistance Mutations
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Component
- 5.1.1 Diagnosis
- 5.1.1.1 Blood Tests
- 5.1.1.2 Rapid/POC Tests
- 5.1.1.3 Molecular (PCR, NAAT)
- 5.1.1.4 Sequencing-based Genotyping
- 5.1.1.5 Others
- 5.1.2 Treatment
- 5.1.2.1 Direct-Acting Antivirals (DAAs)
- 5.1.2.2 Pegylated Interferon + Ribavirin
- 5.1.2.3 Adjunct Immunomodulators
- 5.1.1 Diagnosis
- 5.2 By Age Group
- 5.2.1 Below 18
- 5.2.2 18 - 45
- 5.2.3 Above 45
- 5.3 By Channel
- 5.3.1 Hospitals & Clinics
- 5.3.2 Diagnostic Laboratories
- 5.3.3 Community Pharmacies & Retail Clinics
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.4.1 Abbott Laboratories Inc.
- 6.4.2 AbbVie Inc.
- 6.4.3 Alnylam Pharmaceuticals, Inc.
- 6.4.4 Arbutus Biopharma Corporation
- 6.4.5 Assembly Biosciences, Inc.
- 6.4.6 Atea Pharmaceuticals
- 6.4.7 Bayer AG
- 6.4.8 Bristol-Myers Squibb Co.
- 6.4.9 Cipla Ltd
- 6.4.10 Dr. Reddy's Laboratories
- 6.4.11 Enanta Pharmaceuticals, Inc.
- 6.4.12 F. Hoffmann-La Roche
- 6.4.13 Gilead Sciences Inc.
- 6.4.14 Grifols, S.A.
- 6.4.15 GSK plc
- 6.4.16 Johnson & Johnson Services, Inc.
- 6.4.17 Merck & Co., Inc.
- 6.4.18 Novartis AG
- 6.4.19 OraSure Technologies Inc.
- 6.4.20 QIAGEN N.V.
- 6.4.21 Sun Pharmaceutical Industries Limited
- 6.4.22 Thermo Fisher Scientific Inc.
- 6.4.23 Viatris Inc.
- 6.4.24 Vir Biotechnology, Inc.
- 6.4.25 Zydus Lifesciences Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

