PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100034

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100034
Testing, Inspection, and Certification for the Metals and Minerals Industry - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the testing, inspection, and Certification market size for the metals and minerals industry is expected to grow from USD 21.36 billion in 2025 to USD 22.02 billion in 2026 and is forecast to reach USD 25.64 billion by 2031 at 3.09% CAGR over 2026-2031.
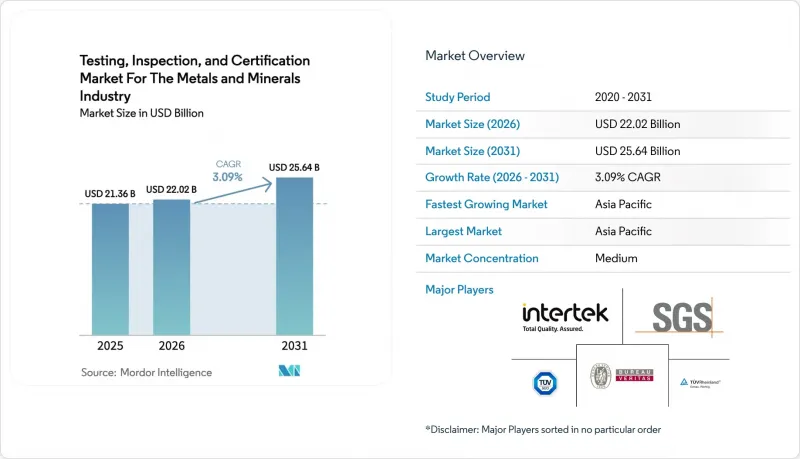
This report is Segmented by Service Type (Testing Services, Inspection Services, and Certification Services), Sourcing Type (In-House and Outsourced), and Geography (North America, South America, Europe, Asia-Pacific, and the Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Testing, Inspection, and Certification for the Metals and Minerals Industry Trends and Insights
Stricter Sustainability and Trace-Metal Disclosure Norms
The EU Corporate Sustainability Reporting Directive now subjects more than 50,000 firms to mandatory third-party assurance, compelling miners to commission external experts for Scope 3 emissions, water stewardship, and biodiversity studies. Major providers, notably SGS, broadened CSRD-aligned services in 2024 to tap an estimated USD 2.3 billion addressable pool for sustainability verification. Institutional investors reference these audits when ranking producers, so mining multinationals replicate the strictest EU formats across global assets. This harmonization makes sustainability testing non-negotiable in contract bidding, effectively locking TIC demand into long-term budgets. It also accelerates the uptake of digital chain-of-custody tools that shorten audit cycles while providing immutable data sets for regulators and financiers. As regional ESG statutes converge, the Testing, Inspection, and Certification for the Metals and Minerals Industry registers stable fee escalations for specialized environmental assays.
Rising Downstream Demand for Battery-Grade Metals
Electric-vehicle OEMs and battery makers tighten impurity thresholds for lithium, nickel, and rare earths, forcing upstream suppliers to prove 99.5% plus purity and sub-ppm contaminant levels. Tesla's 2024 procurement code mandates independent verification of every critical-mineral batch, while CATL requires full trace-element profiles to ensure cathode longevity. These stricter specifications spawn advanced ICP-OES, mass-spectrometry, and laser-ablation programs within TIC labs, alongside tailored reference materials for solid-state and sodium-ion chemistries. Providers monetise premium turnaround guarantees, enabling miners to secure higher-margin offtake agreements. In parallel, battery recyclers employ identical protocols for black-mass input streams, further broadening the Testing, Inspection, and Certification for the Metals and Minerals Industry.
Volatility in Commodity Prices
Sharp price swings alter exploration budgets, deferring drilling campaigns and cut-backs in non-essential assays. Copper slid 23% between Q1 and Q4 2024, prompting Freeport-McMoRan to scale back sampling in marginal pits. Similar retrenchment cascades through contractor labs, eroding utilisation rates and pressuring margins. Providers hedge by structuring output-based contracts and offering modular service tiers that miners can ramp up in bullish cycles. Although volatility curtails near-term volumes, compliance-critical testing remains obligatory, cushioning downside exposure for the Testing, Inspection, and Certification Market for Metals and Minerals Industry.
Other drivers and restraints analyzed in the detailed report include:
- Consolidation of Global Mining Supply Chains
- Digitalization of On-Site Laboratories
- Shortage of Certified Laboratory Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Testing Services accounted for 61.84% of 2025 revenue, anchoring the Testing, Inspection, and Certification Market for Metals and Minerals Industry market size through indispensable grade-control and environmental monitoring obligations. High-volume assays for iron ore, copper, and gold continue despite automation because regulators require externally validated data for export permits and royalty calculations. Certification Services, although smaller, is expanding at a 3.72% CAGR as downstream buyers insist on ESG credentials and blockchain-verified provenance. Providers package carbon-neutral mine labels, responsible-sourcing audits, and ISO 14067 footprints, raising ticket sizes per engagement. Inspection Services occupies a steady middle ground, supported by mandatory conveyor, tailings dam, and rail-wagon integrity checks. Robotics-enabled visual tools and drone-based photogrammetry enrich inspection value propositions and mitigate workforce hazard exposure.
Testing's dominance endures in bulk-commodity jurisdictions where assay density defines ore-body economics. Yet certification will shape margin dynamics because its deliverables command premium pricing and entail higher IP content. Over the forecast period, integrated solutions blending chemical assays with carbon-accounting verification will blur boundaries, allowing providers to upsell certification modules to existing testing clients. For miners, a single supplier simplifies compliance, bolstering stickiness across the Testing, Inspection, and Certification for the Metals and Minerals Industry.
Complete Report Scope:
- By Service Type
- Testing Services
- Inspection Services
- Certification Services
- By Sourcing Type
- In-house
- Outsourced
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held 38.42% of global revenue in 2025 and is growing at a 3.76% CAGR, the quickest among all regions. China's rare-earth processing complex alone generates over USD 3.2 billion in annual TIC demand, driven by stringent wastewater and radionuclide regulations. Indonesia's surge in nickel HPAL projects and Australia's mature iron-ore mines add continuous assay volumes, making the region the core engine for the Testing, Inspection, and Certification Market for Metals and Minerals Industry. Multinationals such as SGS buttress their footprint through acquisitions like RTI Laboratories, ensuring ready access to battery-metal expertise for regional clients.
North America maintains a strong demand anchored in rigorous EPA and MSHA frameworks. Canadian miners leverage high-tech flotation and hydrometallurgical flowsheets that necessitate intricate mineralogical testing. Labor shortages, however, tip the balance toward external labs, especially for high-throughput automation investments that single mines cannot justify. This outsourcing trend ensures stable revenue even as commodity cycles sway exploration volumes. Meanwhile, digital twins, AI-assisted process control, and real-time sensor fusion proliferate across U.S. sites, opening consultancy and calibration add-ons for TIC providers.
Europe gains momentum from the CSRD's far-reaching disclosure requirements. Even non-EU producers exporting into the bloc adopt EU reporting templates, creating spill-over demand into Africa and South America. The Middle East and Africa contribute rising volumes via greenfield copper, lithium, and phosphate ventures, spurred by energy-transition supply deficits. TIC companies harness local partnerships to align with governmental content mandates while importing global QA protocols. Together, these dynamics confirm geography-based opportunities for cross-selling and reinforce the diversified revenue profile of the Testing, Inspection, and Certification for the Metals and Minerals Industry.
- SGS SA
- Bureau Veritas SA
- Intertek Group plc
- ALS Limited
- TUV SUD AG
- TUV Rheinland AG
- Applus+ Servicios Tecnologicos SL
- Eurofins Scientific SE
- Element Materials Technology Group Ltd
- Kiwa NV
- CCIC (China Certification and Inspection Group)
- Cotecna Inspection SA
- DNV AS
- Mistras Group Inc.
- LGC Standards Ltd
- Alex Stewart International Corporation
- Inspectorate International Ltd
- QIMA Ltd
- Mitra SK Testing Services
- Core Laboratories NV
- Scientific and Technical Services Limited
- Peterson and Control Union BV
- CSA Group
- Bureau of Veritas Minerals (AcmeLabs)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Consolidation of global mining supply chains
- 4.2.2 Stricter sustainability and trace-metal disclosure norms
- 4.2.3 Rising downstream demand for battery-grade metals
- 4.2.4 Digitalisation of on-site laboratories
- 4.2.5 Blockchain-enabled provenance audits
- 4.2.6 Geo-political resource nationalism
- 4.3 Market Restraints
- 4.3.1 Volatility in commodity prices
- 4.3.2 Shortage of certified laboratory professionals
- 4.3.3 Consolidation of mining majors reduces vendor count
- 4.3.4 Emerging in-pit real-time sensors bypassing traditional labs
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Testing Services
- 5.1.2 Inspection Services
- 5.1.3 Certification Services
- 5.2 By Sourcing Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 Japan
- 5.3.4.3 India
- 5.3.4.4 South Korea
- 5.3.4.5 South-East Asia
- 5.3.4.6 Rest of Asia-Pacific
- 5.3.5 Middle East and Africa
- 5.3.5.1 Middle East
- 5.3.5.1.1 Saudi Arabia
- 5.3.5.1.2 United Arab Emirates
- 5.3.5.1.3 Turkey
- 5.3.5.1.4 Rest of Middle East
- 5.3.5.2 Africa
- 5.3.5.2.1 South Africa
- 5.3.5.2.2 Nigeria
- 5.3.5.2.3 Rest of Africa
- 5.3.5.1 Middle East
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 SGS SA
- 6.4.2 Bureau Veritas SA
- 6.4.3 Intertek Group plc
- 6.4.4 ALS Limited
- 6.4.5 TUV SUD AG
- 6.4.6 TUV Rheinland AG
- 6.4.7 Applus+ Servicios Tecnologicos SL
- 6.4.8 Eurofins Scientific SE
- 6.4.9 Element Materials Technology Group Ltd
- 6.4.10 Kiwa NV
- 6.4.11 CCIC (China Certification and Inspection Group)
- 6.4.12 Cotecna Inspection SA
- 6.4.13 DNV AS
- 6.4.14 Mistras Group Inc.
- 6.4.15 LGC Standards Ltd
- 6.4.16 Alex Stewart International Corporation
- 6.4.17 Inspectorate International Ltd
- 6.4.18 QIMA Ltd
- 6.4.19 Mitra SK Testing Services
- 6.4.20 Core Laboratories NV
- 6.4.21 Scientific and Technical Services Limited
- 6.4.22 Peterson and Control Union BV
- 6.4.23 CSA Group
- 6.4.24 Bureau of Veritas Minerals (AcmeLabs)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

