PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100035

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100035
Continuous Positive Airway Pressure (CPAP) Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the continuous positive airway pressure devices market size is expected to increase from USD 4.96 billion in 2025 to USD 5.22 billion in 2026 and reach USD 7.94 billion by 2031, growing at a CAGR of 8.76% over 2026-2031.
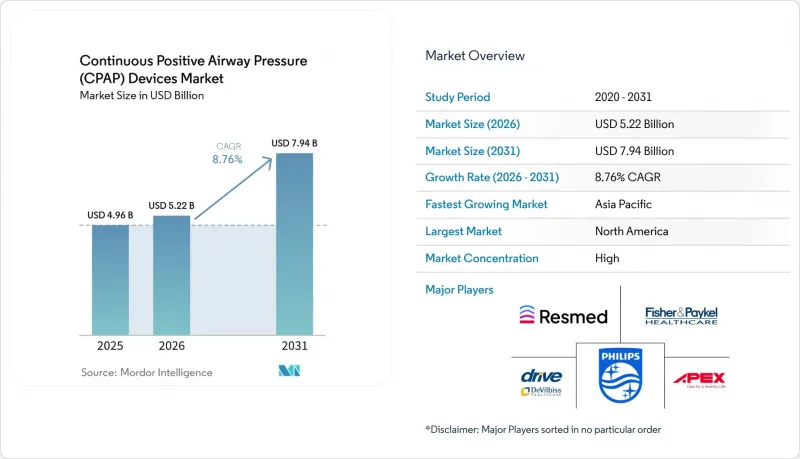
This report is Segmented by Product Type (CPAP Devices [Fixed-Pressure CPAP and More], Accessories [Masks and More]), Interface (Nasal Mask, Nasal Pillow Mask, Full-Face Mask, Oral Mask), End-User (Homecare Settings, and More), Distribution Channel (Offline, Online), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Continuous Positive Airway Pressure (CPAP) Devices Market Trends and Insights
Reimbursement Shift Toward Home-Based Sleep Apnea Treatment
Payer policies now direct funding away from overnight polysomnography toward in-home titration, cutting per-patient diagnostic costs by up to 60% while expanding access in underserved areas. In 2024 Medicare dropped prior-authorization hurdles for auto-titrating units, a move quickly mirrored by large private insurers. The streamlined path from suspicion to prescription accelerates device uptake but compresses margins for suppliers competing under Medicare's revived competitive-bidding framework. The Veterans Health Administration proved the model at scale by enrolling more than 20,000 beneficiaries into a tele-sleep program that pairs remote titration with real-time monitoring. Together, these policies have reshaped demand toward portable devices configured for at-home initiation.
Rising Prevalence of Obesity-Linked Obstructive Sleep Apnea
Global obesity rates continue to climb; the World Health Organization now estimates more than 936 million adults meet clinical thresholds for OSA, up 15% since 2019. In the United States, 42.4% of adults were classified as obese in 2024, creating a direct link between body-mass index and apnea severity. Gulf Cooperation Council states report obesity prevalence above 35%, compounding regional sleep-apnea incidence. Despite rising diagnoses, fewer than 20% of patients in most markets receive therapy, leaving a sizeable treatment gap manufacturers target through consumer advertising and weight-management partnerships. Pharmacological weight-loss therapies will eventually taper device reliance, yet current prescription trends indicate sustained CPAP demand over the medium term across the broader positive air pressure device market.
Frequent Device Recalls and Supply-Chain Disruptions
The Philips DreamStation recall withdrew more than 15 million units between 2021 and 2024 because of degrading sound-abatement foam. Philips agreed to a USD 1.1 billion settlement in April 2024 and now operates under a consent decree that mandates independent oversight, slowing new product launches. The episode highlighted vulnerabilities in component sourcing and spurred competitors to audit supply chains. Semiconductor shortages and elevated freight costs compounded the disruption, squeezing mid-tier manufacturers lacking vertical integration. Heightened regulatory scrutiny raises compliance costs industry-wide and lengthens development timelines.
Other drivers and restraints analyzed in the detailed report include:
- Post-COVID Tele-Sleep Programs Accelerating CPAP Adoption
- Introduction of Ultra-Quiet Micro-Blowers Enabling Travel-Size CPAPs
- Patient Non-Adherence Due to Mask Discomfort and Claustrophobia
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The accessories segment generated 36.48% of 2025 revenue and is expanding at 11.46% CAGR, well above the 8.76% growth for devices. Filters, tubing, and masks require regular replacement, creating subscription-like cash flows that soften cyclicality in hardware demand. Auto-titrating units are gaining favor for their comfort advantages, while bilevel machines remain niche due to higher prices. Compliance with ISO 80601-2-70 standards and stricter FDA review processes elevate entry barriers for newcomers.
CPAP devices market share leadership in devices remains intact, yet manufacturers increasingly subsidize hardware to secure downstream accessory sales. The CPAP devices market size for accessories is projected to add USD 1.2 billion during the forecast, lifting gross-margin profiles across the value chain.
Nasal masks retained 44.26% interface revenue in 2025, but nasal-pillow masks are projected to capture the highest share of incremental sales, expanding at 10.57% CAGR. Lightweight construction and reduced facial coverage ease claustrophobia and improve adherence. Full-face masks remain essential for mouth breathers yet face leakage challenges that spur design innovation.
Improved comfort is key to reducing abandonment. As patients shift toward smaller interfaces, the CPAP devices market expects substitution rather than absolute growth, yet premium pricing and rapid replacement cycles buoy revenue. The CPAP devices industry is likely to witness intensified competition among interface suppliers seeking differentiation through fit and noise reduction.
Complete Report Scope:
- By Product Type
- CPAP Devices
- Fixed-pressure CPAP
- Auto-titrating (APAP)
- Bilevel PAP
- Accessories
- Masks
- Tubing & Filters
- Humidifiers
- CPAP Devices
- By Interface (Mask Type)
- Nasal Mask
- Nasal Pillow Mask
- Full-face Mask
- Oral Mask
- By End-User
- Homecare Settings
- Sleep Laboratories & Clinics
- Hospitals
- By Distribution Channel
- Offline (DME Stores, Hospital Pharmacies)
- Online (E-commerce, Company Webshops)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 34.54% of 2025 revenue, underpinned by Medicare coverage expansion, a robust durable-medical-equipment network, and the Veterans Health Administration's tele-sleep enrollment of more than 20,000 patients. The Philips recall shook regional confidence but simultaneously opened share for ResMed and Fisher & Paykel. Competitive bidding, however, is squeezing smaller distributors and slowing unit growth. The US continuous positive airway pressure CPAP devices market continues to account for the largest share of regional demand.
Europe ranks second, with Germany, France, and the United Kingdom leading demand amid universal health-care coverage and strict quality standards. Germany reimburses devices with minimal co-pay, while France updated guidelines in 2024 to prioritize auto-titration. Southern European nations lag on treatment penetration but are investing in sleep-medicine infrastructure to close the gap.
Asia-Pacific is the growth engine, forecast at 10.36% CAGR. South Korea's national insurance expansion aims for 1.5 million treated users by 2030. Chinese firms supply sub-USD 300 units domestically and abroad, but quality concerns limit penetration in premium segments. India's urban centers are adopting tele-sleep diagnostics, while Australia shows steady replacement demand among an aging yet mobile population.
- 3B Medical
- Apex Medical
- BMC Medical Co. Ltd.
- Cardinal Health
- Curative Medical Inc.
- Dehaier Medical Systems
- Drive DeVilbiss Healthcare
- Fisher & Paykel Healthcare Corporation Limited
- Invacare
- Koninklijke Philips N.V. (Philips Respironics)
- Lowenstein Medical GmbH & Co. KG
- Mercury Medical
- Nihon Kohden
- React Health
- Resmed
- Sefam Medical
- Mindray
- Smiths Group
- Somnetics International Inc.
- Teleflex
- Vyaire Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Reimbursement Shift Toward Home-Based Sleep Apnea Treatment
- 4.2.2 Rising Prevalence Of Obesity-Linked Obstructive Sleep Apnea (OSA)
- 4.2.3 Post-COVID Tele-Sleep Programs Accelerating CPAP Adoption
- 4.2.4 Introduction Of Ultra-Quiet Micro-Blowers Enabling Travel-Size Cpaps
- 4.2.5 AI-Driven Adherence & Cloud Analytics Platforms
- 4.2.6 Pharmacy & Tech-Led Rollout Of Affordable Home-Sleep-Testing Kits
- 4.3 Market Restraints
- 4.3.1 Frequent Device Recalls & Supply-Chain Disruptions
- 4.3.2 Patient Non-Adherence Due To Mask Discomfort & Claustrophobia
- 4.3.3 Emergence Of Mandibular Advancement & Hypoglossal Nerve Stimulation Competing Therapies
- 4.3.4 Re-Activation Of Medicare DMEPOS Competitive Bidding & Similar Tender Reforms
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 CPAP Devices
- 5.1.1.1 Fixed-pressure CPAP
- 5.1.1.2 Auto-titrating (APAP)
- 5.1.1.3 Bilevel PAP
- 5.1.2 Accessories
- 5.1.2.1 Masks
- 5.1.2.2 Tubing & Filters
- 5.1.2.3 Humidifiers
- 5.1.1 CPAP Devices
- 5.2 By Interface (Mask Type)
- 5.2.1 Nasal Mask
- 5.2.2 Nasal Pillow Mask
- 5.2.3 Full-face Mask
- 5.2.4 Oral Mask
- 5.3 By End-User
- 5.3.1 Homecare Settings
- 5.3.2 Sleep Laboratories & Clinics
- 5.3.3 Hospitals
- 5.4 By Distribution Channel
- 5.4.1 Offline (DME Stores, Hospital Pharmacies)
- 5.4.2 Online (E-commerce, Company Webshops)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 United Kingdom
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 3B Medical Inc.
- 6.3.2 Apex Medical Corp.
- 6.3.3 BMC Medical Co. Ltd.
- 6.3.4 Cardinal Health, Inc.
- 6.3.5 Curative Medical Inc.
- 6.3.6 Dehaier Medical Systems
- 6.3.7 Drive DeVilbiss Healthcare LLC
- 6.3.8 Fisher & Paykel Healthcare Corporation Limited
- 6.3.9 Invacare Corporation
- 6.3.10 Koninklijke Philips N.V. (Philips Respironics)
- 6.3.11 Lowenstein Medical GmbH & Co. KG
- 6.3.12 Mercury Medical
- 6.3.13 Nihon Kohden Corporation
- 6.3.14 React Health
- 6.3.15 ResMed Inc.
- 6.3.16 Sefam Medical
- 6.3.17 Shenzhen Mindray Bio-Medical Electronics Co. Ltd.
- 6.3.18 Smiths Medical (ICU Medical)
- 6.3.19 Somnetics International Inc.
- 6.3.20 Teleflex Inc.
- 6.3.21 Vyaire Medical, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment

