PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100734

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2100734
UVC LED - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, UVC LED market size in 2026 is estimated at USD 1.39 billion, growing from 2025 value of USD 1.05 billion with 2031 projections showing USD 5.59 billion, growing at 32.18% CAGR over 2026-2031.
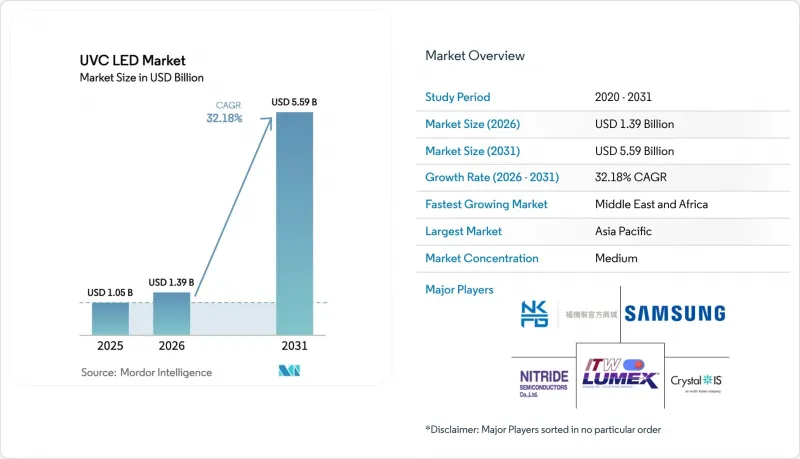
This report is Segmented by Application (Surface Disinfection, Air Disinfection, and More), Optical Power Output (Low-Power (Less Than 50 MW), and More), Peak Wavelength (nm) (250-260 Nm, and More), Packaging Technology (Surface-Mount Device (SMD), Through-Hole, and More), End-User Sector (Municipal Water and Wastewater Treatment, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global UVC LED Market Trends and Insights
Rising demand for water disinfection applications
Municipal utilities are scaling UVC LED modules to safeguard drinking supplies as climate-induced water stress intensifies. Installations grew 78% year-on-year in 2025, reflecting confidence in solid-state devices that target the 260-270 nm germicidal peak while consuming 30% less energy than mercury lamps. Compact architectures allow retrofits within existing pipe galleries, an advantage in dense urban plants where space premiums limit large reactors.Real-time dose monitoring embedded in smart controllers optimizes exposure to varying turbidity, cutting chemical residuals and operating expenditures. Field evidence shows 99.99% pathogen inactivation-including drug-resistant strains-at flow rates once considered unreachable for LEDs. These performance gains position the technology as a cornerstone of next-generation water resilience strategies.
Growing adoption in air disinfection systems
Commercial buildings, transport hubs, and homes are embedding UVC LED arrays into HVAC plenums to counter aerosolized pathogens in the post-pandemic era. Installations in commercial properties climbed 65% in 2025 over 2024, driven by studies demonstrating a 99.9% drop in airborne microbial counts within 15 minutes of operation. Airlines have fitted cabin-air units with high-frequency pulsed LEDs, cutting passenger exposure to respiratory viruses by 87% while consuming 40% less power than continuous-mode fixtures. Facility managers also value instant-on operation that aligns with occupancy sensors, a feature that minimizes wasted irradiation and extends emitter life.
High initial costs compared to traditional UV technologies
System prices remain 2.5-3.5 times higher than mercury lamps, especially where multi-array configurations are essential. The delta is acute in large-capacity water plants where procurement budgets face scrutiny, although falling device ASPs-down 30% since 2024-are closing the gap. Total-cost-of-ownership modeling consistently shows payback within 12-18 months once energy and maintenance savings are tallied, a message that resonates with operators familiar with escalating mercury disposal fees.
Other drivers and restraints analyzed in the detailed report include:
- Increasing focus on healthcare-associated infection prevention
- Technological advancements improving efficiency and reducing costs
- Technical limitations in efficiency and lifespan
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Water disinfection captured 44.20% of the UVC LED market size in 2025, cementing its role as the anchor segment. Utilities favor LEDs for their ability to neutralize chlorine-resistant parasites while occupying footprints 40% smaller than legacy reactors. Point-of-use filters fitted to household taps and smart dispensers posted an 85% shipment spike in 2025, showing that municipal deployments reverberate downstream into consumer demand.
Air disinfection posted the quickest uptick, advancing at a 34.6% CAGR through 2031 as building codes elevate indoor-air-quality thresholds. Hospitals, schools, and aircraft cabins now specify UVC LED retrofits in HVAC coils, a market where self-calibrating sensors verify delivered dose and feed data to building-management dashboards. The synergy between IoT analytics and solid-state UV is encouraging service-based revenue models in which providers guarantee microbial limits instead of selling hardware outright.
Low-power emitters ( Less than 50 mW) dominated with 47.30% UVC LED market share in 2025 owing to lightweight battery-operated gadgets such as travel sterilizers and smart water bottles. Continuous miniaturization lets brands integrate multiple chips into lids and phone cases without compromising ergonomics, a trend that resonates with hygiene-conscious consumers.
High-power devices (Above 100 mW) are the growth pacesetters at a 33.1% CAGR, unlocking municipal water channels and high-throughput conveyor systems in food plants. Samples released in late 2024 sustain 115 mW at 265 nm while preserving lifetime above 20,000 hours, meeting the stringent duty cycles demanded by public utilities. The mid-power tier (50-100 mW) sits in the price-performance sweet spot for decentralized air units in offices and retail, providing redundancy when arranged in tiled arrays.
Complete Report Scope:
- By Application
- Surface Disinfection
- Air Disinfection
- Water Disinfection
- Object/Tool Disinfection
- Biological Research and Laboratory Sterilization
- By Optical Power Output
- Low-Power (Less than 50 mW)
- Medium-Power (50-100 mW)
- High-Power (Above 100 mW)
- By Peak Wavelength (nm)
- 250-260 nm
- 260-270 nm
- 270-280 nm
- By Packaging Technology
- Surface-Mount Device (SMD)
- Through-Hole
- Chip-on-Board (COB)
- Others (Flip-Chip, Wafer-Level)
- By End-User Sector
- Municipal Water and Wastewater Treatment
- Residential and Commercial Point-of-Use Systems
- Healthcare and Medical Devices
- Food and Beverage Processing
- Industrial and Semiconductor Manufacturing
- Consumer Electronics and Appliances
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- South East Asia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia Pacific LED the UVC LED market with 40.60% revenue in 2025, underpinned by Japan, South Korea, and China, which together supply more than 70% of global chip output. National R&D programs-such as South Korea's USD 1.2 billion UV initiative launched in 2025-anchor an ecosystem that pairs AlGaN epitaxy expertise with high-volume ceramic packaging lines. Consumer uptake is equally vigorous; air-purifier sales fitted with LEDs tripled year-on-year in 2024 as smart-home platforms advertised verified microbial kill rates. North America followed with 28.10%, propelled by stringent infection-control norms. By late 2024, two-thirds of large hospital networks had embedded UVC LED regimens into standard operating practice, driving bulk procurement of cart-based and ceiling-mounted fixtures. Public-sector spending remains strong, with more than 120 municipal water plants commissioning LED reactors in 2024 after U.S. Environmental Protection Agency guidance endorsed UV for primary disinfection. Venture capital exceeded USD 170 million in 2024, nurturing start-ups that mash up UV hardware with sensor analytics. Europe secured an 18.10% share, with Germany spearheading industrial deployment in clean-production zones and pharmaceuticals. The Restriction of Hazardous Substances (RoHS) Directive continues to nudge factories away from mercury lamps, sustaining order books for retrofit kits. The Middle East and Africa region, though smaller at 8.10%, is the fastest climber at a 33.2% CAGR to 2031, buoyed by mega-projects that fortify water security and upgrade infection-prevention capacity. South America holds 5.10%, LED by Brazil's push to shield water grids from chlorine-resistant microbes.
- Seoul Viosys Co., Ltd.
- Nichia Corporation
- Crystal IS, Inc. (Asahi Kasei Group)
- ams-Osram AG
- Luminus Devices, Inc.
- Nitride Semiconductors Co., Ltd.
- Stanley Electric Co., Ltd.
- Lite-On Technology Corporation
- Bolb Inc.
- NKFG Corporation
- Hongli Zhihui Group Co., Ltd.
- Lumex Inc. (ITW)
- International Light Technologies, Inc.
- Qingdao Jason Electric Co., Ltd.
- Violumas
- DOWA Electronics Materials Co., Ltd.
- Everlight Electronics Co., Ltd.
- Union Semiconductor (Suzhou) Co., Ltd.
- Sensor Electronic Technology, Inc. (SETi)
- Excelitas Technologies Corp.
- Ushio Inc.
- Heraeus Holding GmbH
- Dr. Honle AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory Push for Mercury-Free Disinfection Solutions in Europe
- 4.2.2 Miniaturization Enabling Integration into Consumer Appliances in North America
- 4.2.3 Stringent Drinking Water Standards in Asian Emerging Economies
- 4.2.4 Uptake in Semiconductor Fabs for Surface Sterilization
- 4.2.5 Hospital-Acquired Infection Reduction Programs in Gulf Cooperation Council Countries Countries
- 4.2.6 Replacement Cycle of Conventional Mercury Lamps Due to EU RoHS 2024 Ban
- 4.3 Market Restraints
- 4.3.1 Heat Management Challenges Above 100 mW Optical Output
- 4.3.2 Photonic Efficiency Ceiling Due to AlGaN Crystal Defects
- 4.3.3 ASP Declines Squeezing Margins for Tier-2 Asian Fabs
- 4.3.4 Limited Standardized Testing Protocols Delaying OEM Qualification in the U.S.
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Pricing Analysis
- 4.8 UV-C LED Manufacturing Process Analysis
- 4.9 Comparison of UV Lamp Technologies
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Application
- 5.1.1 Surface Disinfection
- 5.1.2 Air Disinfection
- 5.1.3 Water Disinfection
- 5.1.4 Object/Tool Disinfection
- 5.1.5 Biological Research and Laboratory Sterilization
- 5.2 By Optical Power Output
- 5.2.1 Low-Power (Less than 50 mW)
- 5.2.2 Medium-Power (50-100 mW)
- 5.2.3 High-Power (Above 100 mW)
- 5.3 By Peak Wavelength (nm)
- 5.3.1 250-260 nm
- 5.3.2 260-270 nm
- 5.3.3 270-280 nm
- 5.4 By Packaging Technology
- 5.4.1 Surface-Mount Device (SMD)
- 5.4.2 Through-Hole
- 5.4.3 Chip-on-Board (COB)
- 5.4.4 Others (Flip-Chip, Wafer-Level)
- 5.5 By End-User Sector
- 5.5.1 Municipal Water and Wastewater Treatment
- 5.5.2 Residential and Commercial Point-of-Use Systems
- 5.5.3 Healthcare and Medical Devices
- 5.5.4 Food and Beverage Processing
- 5.5.5 Industrial and Semiconductor Manufacturing
- 5.5.6 Consumer Electronics and Appliances
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 South Korea
- 5.6.3.4 India
- 5.6.3.5 South East Asia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Seoul Viosys Co., Ltd.
- 6.4.2 Nichia Corporation
- 6.4.3 Crystal IS, Inc. (Asahi Kasei Group)
- 6.4.4 ams-Osram AG
- 6.4.5 Luminus Devices, Inc.
- 6.4.6 Nitride Semiconductors Co., Ltd.
- 6.4.7 Stanley Electric Co., Ltd.
- 6.4.8 Lite-On Technology Corporation
- 6.4.9 Bolb Inc.
- 6.4.10 NKFG Corporation
- 6.4.11 Hongli Zhihui Group Co., Ltd.
- 6.4.12 Lumex Inc. (ITW)
- 6.4.13 International Light Technologies, Inc.
- 6.4.14 Qingdao Jason Electric Co., Ltd.
- 6.4.15 Violumas
- 6.4.16 DOWA Electronics Materials Co., Ltd.
- 6.4.17 Everlight Electronics Co., Ltd.
- 6.4.18 Union Semiconductor (Suzhou) Co., Ltd.
- 6.4.19 Sensor Electronic Technology, Inc. (SETi)
- 6.4.20 Excelitas Technologies Corp.
- 6.4.21 Ushio Inc.
- 6.4.22 Heraeus Holding GmbH
- 6.4.23 Dr. Honle AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

