PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113429

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113429
Asia-Pacific Superabsorbent Polymers (SAP) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Asia-Pacific superabsorbent polymers market size is expected to grow from 1.88 million tons in 2025 to 2 million tons in 2026 and is forecast to reach 2.75 million tons by 2031 at a 6.51% CAGR over 2026-2031.
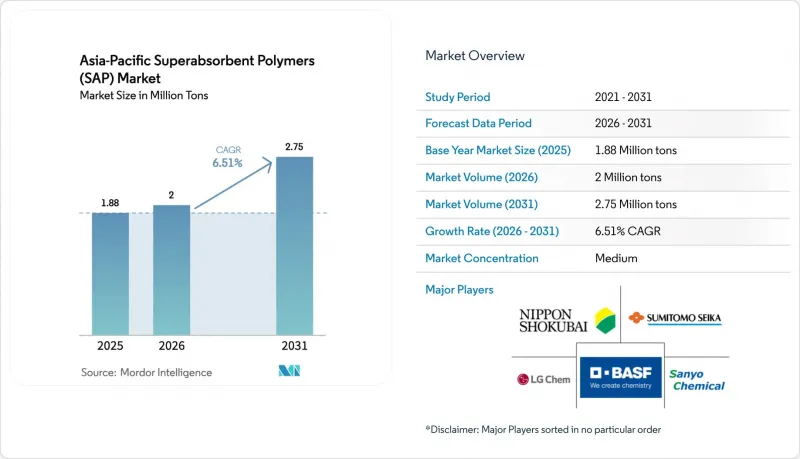
This report is Segmented by Product Type (Polyacrylamide, Acrylic Acid Based, and Others), Application (Baby Diapers, Adult Incontinence Products, Feminine Hygiene, Agriculture Support, and Others), and Geography (China, India, Japan, South Korea, Australia and New Zealand, and Rest of Asia-Pacific). The Market Forecasts are Provided in Terms of Volume (Tons).
Asia-Pacific Superabsorbent Polymers (SAP) Market Trends and Insights
Rising Hygiene Awareness And Disposable Incomes
Lower-tier cities in China and India are switching from cloth to disposables as household incomes rise, keeping penetration below 15% in many Tier-3 districts but creating a steep catch-up path to coastal averages above 90%. Unicharm's new Gujarat plant will lift its Indian output by 50%, while Kimberly-Clark's USD 50 million Nanjing Phase III project, due September 2025, adds four lines aimed at inland demand. Government sanitation campaigns have normalized diaper use even in rural settings, and income elasticity estimates between 1.2 and 1.5 signal that GDP expansion translates directly into superabsorbent polymer offtake. Multinationals localize production for fiscal advantages, yet still rely on regionally sourced SAP grades customized for thinner cores. The driver's medium-term runway remains intact despite near-term macro cycles.
Rapid Aging Population Boosting Adult Incontinence Product Demand
Japan's mature market already sells more adult pants than baby diapers, and South Korea's 65-plus cohort is on track to hit 46.4% by 2070. Adult briefs command unit prices 30%-50% higher than baby products, rewarding SAP suppliers capable of low-rewet, odor-control chemistries. Chinese urban centers are beginning to shift in the same direction as population aging accelerates. This demand mix change favors producers with advanced surface-treatment know-how over commodity players. Long-term visibility allows incumbents to allocate research and development toward high-margin grades even while defending baby-diaper volumes.
Volatile Acrylic Acid Feedstock Pricing
Spot acrylic acid in China fell from CNY 15,800 per ton in February 2022 to CNY 6,550 by December 2022, squeezing margins for SAP makers tied to fixed diaper contracts. New acrylate units from BASF and Changhong Polymer will add more than 450 kilotons of capacity by 2026, potentially tempering spikes, but exposure remains acute until integration spreads. Sanyo Chemical's March 2024 exit after a JPY 1.6 billion loss spotlights how non-integrated producers are most vulnerable. Hedging strategies and propane-based acrylic routes may mitigate the short-term drag, yet pricing volatility still subtracts 1.1 percentage points from forecast growth.
Other drivers and restraints analyzed in the detailed report include:
- Expansion Of Diaper Manufacturing Capacity Within APAC
- Government Incentives For Water-Saving Agriculture Using SAP Hydrogels
- Environmental And End-Of-Life Concerns For Petro-Based SAP
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyacrylamide captured 25.74% of regional volume in 2025 and is on track for a 6.08% CAGR, giving it the fastest growth among established chemistries in the Asia-Pacific superabsorbent polymers market. Acrylic-acid grades still dominate premium baby and adult briefs thanks to superior absorption and retention, but they concede price-sensitive agricultural and feminine-care niches to polyacrylamide.
Producers enhance acrylic-acid SAP through surface-treatment upgrades that cut gel-blocking and enable thinner diaper cores, a key requirement for value brands pushing down gram-per-piece costs. Nippon Shokubai's 2022 global retrofit that lifted plant productivity by roughly 10% underscores how incumbents lean on process gains to defend share. Bio-based or cellulose-grafted SAP posts double-digit growth, helped by pilot launches such as BAYSE. The trajectory suggests a gradual mix shift rather than a sudden displacement, so supply chains for both legacy and emerging chemistries will coexist through the decade.
Complete Report Scope:
- By Product Type
- Polyacrylamide
- Acrylic Acid based
- Others
- By Application
- Baby Diapers
- Adult Incontinence Products
- Feminine Hygiene
- Agriculture Support
- Others
- By Geography
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- ADM
- BASF SE
- Chemtex Speciality Limited
- Evonik Industries AG
- Formosa Plastics Group (Nan Ya Plastics)
- Gel Frost Packs Kalyani Enterprises
- Kao Corporation
- LG Chem
- NIPPON SHOKUBAI CO.,LTD.
- Qingdao SOCO New Material Co.,Ltd.
- SANYO CHEMICAL, LTD.
- Satellite Chemical Co., Ltd.
- Shandong Nuoer Biological Technology
- SNF Floerger
- SUMITOMO SEIKA CHEMICALS CO.,LTD.
- Wanhua Chemical Group Co., Ltd.
- Yixing Danson Technology
- Zhejiang Satellite Petrochemical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising hygiene awareness and disposable incomes
- 4.2.2 Rapid ageing population boosting adult-incontinence product demand
- 4.2.3 Expansion of diaper manufacturing capacity within APAC
- 4.2.4 Government incentives for water-saving agriculture using SAP hydrogels
- 4.2.5 Shift toward bio-based SAP chemistries
- 4.3 Market Restraints
- 4.3.1 Volatile acrylic-acid feedstock pricing
- 4.3.2 Environmental and end-of-life concerns for petro-based SAP
- 4.3.3 Looming micro-plastics regulations on absorbent hygiene products
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Polyacrylamide
- 5.1.2 Acrylic Acid based
- 5.1.3 Others
- 5.2 By Application
- 5.2.1 Baby Diapers
- 5.2.2 Adult Incontinence Products
- 5.2.3 Feminine Hygiene
- 5.2.4 Agriculture Support
- 5.2.5 Others
- 5.3 By Geography
- 5.3.1 China
- 5.3.2 India
- 5.3.3 Japan
- 5.3.4 South Korea
- 5.3.5 Australia and New Zealand
- 5.3.6 Rest of Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ADM
- 6.4.2 BASF SE
- 6.4.3 Chemtex Speciality Limited
- 6.4.4 Evonik Industries AG
- 6.4.5 Formosa Plastics Group (Nan Ya Plastics)
- 6.4.6 Gel Frost Packs Kalyani Enterprises
- 6.4.7 Kao Corporation
- 6.4.8 LG Chem
- 6.4.9 NIPPON SHOKUBAI CO.,LTD.
- 6.4.10 Qingdao SOCO New Material Co.,Ltd.
- 6.4.11 SANYO CHEMICAL, LTD.
- 6.4.12 Satellite Chemical Co., Ltd.
- 6.4.13 Shandong Nuoer Biological Technology
- 6.4.14 SNF Floerger
- 6.4.15 SUMITOMO SEIKA CHEMICALS CO.,LTD.
- 6.4.16 Wanhua Chemical Group Co., Ltd.
- 6.4.17 Yixing Danson Technology
- 6.4.18 Zhejiang Satellite Petrochemical
7 Market Opportunities and Future Outlook
- 7.1 White-space and unmet-need assessment

