PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113479

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113479
Telecom Cloud - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the telecom cloud market size is expected to grow from USD 31.34 billion in 2025 to USD 39.79 billion in 2026 and is forecast to reach USD 131.19 billion by 2031 at 26.95% CAGR over 2026-2031.
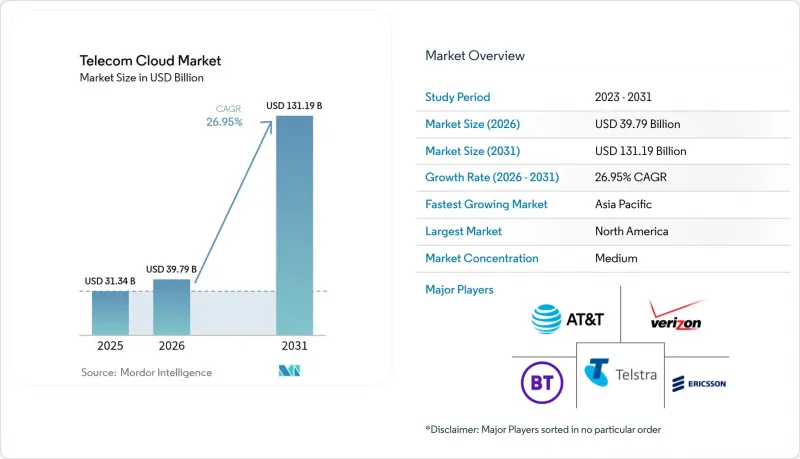
This report is Segmented by Type (Solution, Services, and More), Application (Billing and Provisioning, Traffic Management, and More), Cloud Platform (SaaS, Iaas, and PaaS), End User (BFSI, Retail, Manufacturing, and More) and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Telecom Cloud Market Trends and Insights
Surge in 5G roll-outs demanding cloud-native core networks
Standalone 5G mandates cloud-native cores, dismantling monolithic architectures in favor of micro-services that enable automated network slicing and real-time provisioning. Deutsche Telekom's work with Google Cloud on AI-driven RAN orchestration proves that automation is now indispensable to manage the scale and complexity of 5G traffic. Telefonica Germany migrated 45 million subscribers to Ericsson's cloud-native 5G core, cutting service-activation times and fortifying network agility.These transformations signal that 5G revenue relies on cloud-native capabilities deployed at carrier grade.
Growing adoption of hybrid and multi-cloud by telecom operators
Rakuten Symphony's multi-cloud blueprint showcases workload portability across providers while guarding sovereignty obligations. Hybrid architectures allow latency-sensitive network functions to remain on-premise while scalable workloads burst to public clouds. Cisco finds 82% of enterprises now run hybrid models, validating the strategy for resilience and cost optimization. This dual-environment adoption is accelerating as operators link compliance with innovation velocity.
Data-sovereignty and security compliance hurdles
Google Cloud's telecom-specific compliance frameworks attest to the maze of regional privacy rules carriers must meet. Localization mandates inflate compute costs by up to 60%, eroding the telecom cloud market's cost-saving allure. VMware sovereign-cloud blueprints show architecture complexity rises when carriers enforce in-country residency and encryption at rest. Evolving statutes constrain deployment flexibility and lengthen project timelines.
Other drivers and restraints analyzed in the detailed report include:
- Edge-cloud federation enabling ultra-low-latency enterprise 4.0
- Convergence of Open RAN accelerating RAN-cloudification
- Integration complexity with legacy BSS/OSS stacks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025 solution segment held 52.85% share, reflecting operators' first-wave focus on foundational cloud stacks. Yet Services are accelerating at a 27.25% CAGR, forecast to close the gap as carriers outsource operations to specialist partners. Unified communication, CDN, and security workloads continue to lift Solution revenues, but managed hosting, professional services, and network-as-a-service contracts are growing faster.
Operators increasingly adopt managed models to de-risk transformation and redeploy staff toward customer innovation. Colocation footprints give carriers proximity to edge zones, while professional-service engagements address skills shortages. This trend signals a structural shift toward opex-based consumption, aligning telco spending with traffic elasticity and subscriber seasonality across the telecom cloud market.
Billing and Provisioning retained 45.10% of telecom cloud market size in 2025, underpinning revenue assurance activities critical to every carrier. Traffic Management, however, is projected to grow 27.6% annually as 5G data surges strain networks. Cisco's Ultra Traffic Optimization and Opanga's RAIN AI showcase AI-driven congestion relief that boosts QoE without fresh spectrum buys.
AI-infused engines that predict congestion and reroute packets in real time are becoming must-have capabilities. HCL's Augmented Network Automation illustrates 20% capacity lifts alongside OPEX cuts, explaining the outsized growth. Ancillary workloads such as security analytics and customer-experience portals also migrate to cloud in lockstep, reinforcing application-layer diversification within the telecom cloud market.
Complete Report Scope:
- By Type
- Solution
- Unified Communication and Collaboration
- Content Delivery Network
- Other Solutions
- Service
- Colocation Services
- Network Services
- Professional Services
- Managed Services
- Other Types
- Solution
- By Application
- Billing and Provisioning
- Traffic Management
- Other Applications
- By Cloud Platform
- Software-as-a-Service (SaaS)
- Infrastructure-as-a-Service (IaaS)
- Platform-as-a-Service (PaaS)
- By End User
- BFSI
- Retail
- Manufacturing
- Transportation and Distribution
- Healthcare
- Government
- Media and Entertainment
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Taiwan
- Rest of Asia-Pacific
- Middle-East and Africa
- Middle-East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle- East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle-East
- North America
Geography Analysis
North America accounted for 34.90% revenue in 2025 as early 5G roll-outs, established hyperscaler partnerships, and favorable regulations aligned. Carriers monetized edge services and enterprise connectivity, strengthening regional leadership in the telecom cloud market. Federal funding streams for rural 5G also bolster investment momentum.
Asia-Pacific is projected to expand at 26.85% CAGR through 2031, supported by government digitalization programs and massive data-center investments. AWS's USD 15 billion commitment and Microsoft's USD 2.9 billion plan in Japan illustrate capital intensity, while Huawei's 77% cloud-service revenue jump in 2023 signals domestic demand acceleration. China's USD 9.2 billion 2023 cloud-infrastructure spend positions its carriers and local providers for growth.
Europe remains a sizeable market, where stringent sovereignty mandates foster sovereign-cloud builds and spark Open RAN experiments. Energy-efficiency goals align with cloud consolidation, giving European carriers strategic imperatives to modernize networks. Middle East and Africa and Latin America show rising adoption curves fueled by smart-city initiatives, fintech penetration, and mobile-first demographics, though regulatory gaps and skills shortages temper near-term scale.
- ATandT Inc.
- Verizon Communications Inc.
- BT Group plc
- Deutsche Telekom AG
- NTT Communications Corp.
- China Telecommunications Corp.
- Telstra Corp. Ltd
- Telefonaktiebolaget LM Ericsson
- CenturyLink (Lumen Technologies)
- Singapore Telecommunications Ltd
- Telus Corp.
- Swisscom AG
- Amazon Web Services
- Microsoft Azure
- Google Cloud
- IBM Cloud
- Oracle Communications Cloud
- Huawei Cloud
- VMware (Telco Cloud Platform)
- Cisco Systems (Telco Cloud)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in 5G roll-outs demanding cloud-native core networks
- 4.2.2 Growing adoption of hybrid and multi-cloud by telecom operators
- 4.2.3 Cost efficiency via NFV-enabled OPEX savings
- 4.2.4 Convergence of Open RAN accelerating RAN-cloudification
- 4.2.5 Edge-cloud federation enabling ultra-low-latency enterprise 4.0
- 4.2.6 Sustainability pledges shifting telcos to green public clouds
- 4.3 Market Restraints
- 4.3.1 Data-sovereignty and security compliance hurdles
- 4.3.2 Integration complexity with legacy BSS/OSS stacks
- 4.3.3 Shortage of cloud-native skills in telco ops teams
- 4.3.4 High cross-border cloud exit-cost risk exposures
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Force Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Solution
- 5.1.1.1 Unified Communication and Collaboration
- 5.1.1.2 Content Delivery Network
- 5.1.1.3 Other Solutions
- 5.1.2 Service
- 5.1.2.1 Colocation Services
- 5.1.2.2 Network Services
- 5.1.2.3 Professional Services
- 5.1.2.4 Managed Services
- 5.1.3 Other Types
- 5.1.1 Solution
- 5.2 By Application
- 5.2.1 Billing and Provisioning
- 5.2.2 Traffic Management
- 5.2.3 Other Applications
- 5.3 By Cloud Platform
- 5.3.1 Software-as-a-Service (SaaS)
- 5.3.2 Infrastructure-as-a-Service (IaaS)
- 5.3.3 Platform-as-a-Service (PaaS)
- 5.4 By End User
- 5.4.1 BFSI
- 5.4.2 Retail
- 5.4.3 Manufacturing
- 5.4.4 Transportation and Distribution
- 5.4.5 Healthcare
- 5.4.6 Government
- 5.4.7 Media and Entertainment
- 5.4.8 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Taiwan
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Middle-East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle- East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle-East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 ATandT Inc.
- 6.4.2 Verizon Communications Inc.
- 6.4.3 BT Group plc
- 6.4.4 Deutsche Telekom AG
- 6.4.5 NTT Communications Corp.
- 6.4.6 China Telecommunications Corp.
- 6.4.7 Telstra Corp. Ltd
- 6.4.8 Telefonaktiebolaget LM Ericsson
- 6.4.9 CenturyLink (Lumen Technologies)
- 6.4.10 Singapore Telecommunications Ltd
- 6.4.11 Telus Corp.
- 6.4.12 Swisscom AG
- 6.4.13 Amazon Web Services
- 6.4.14 Microsoft Azure
- 6.4.15 Google Cloud
- 6.4.16 IBM Cloud
- 6.4.17 Oracle Communications Cloud
- 6.4.18 Huawei Cloud
- 6.4.19 VMware (Telco Cloud Platform)
- 6.4.20 Cisco Systems (Telco Cloud)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

