PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113766

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113766
Chipless RFID - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
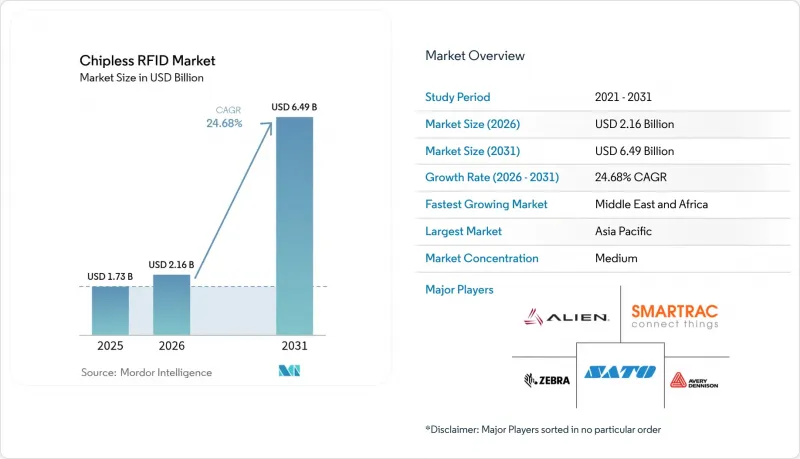
According to Mordor Intelligence, the chipless RFID market size was valued at USD 1.73 billion in 2025 and estimated to grow from USD 2.16 billion in 2026 to reach USD 6.49 billion by 2031, at a CAGR of 24.68% during the forecast period (2026-2031).
This report is Segmented by Product Type (Tag, Reader, Middleware), Printing Technology (Ink-Jet, Screen, and More), Operating Frequency (LF 125-134 KHz, and More), Material (Silver-Nano Ink, Copper-Based Ink, and More), Application (Smart Cards, Smart Tickets, and More), End-User Industry (Retail and E-Commerce, Healthcare and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Chipless RFID Market Trends and Insights
Lower-cost Mass Production of IC-less Tags in Asian FMCG Packaging
Manufacturers in China and Southeast Asia have combined flexible substrates with silver-nano paste to reach sub-5-cent tags, positioning the chipless RFID market for high-volume adoption in consumer-goods multipacks. Contract printers are running multi-lane flexographic lines at speeds above 120 m/min, allowing over 2 billion units per plant annually. Fast payback on retrofits and geographic proximity to packaging converters accelerate uptake. Suppliers are piloting recyclable cellulose substrates to align with brand sustainability targets. As costs fall, single-use tags are extending into disposable electronics and unit-dose pharmaceutical packs.
Government Excise / Tax-stamp Mandates
EU loss estimates of EUR 16 billion (USD 17.3 billion) in counterfeited goods prompted Directive 2024/1640, which endorses tamper-evident identifiers with unique RF signatures. Ministries of finance in Italy, Spain, and Saudi Arabia now specify chipless formats for alcohol and tobacco stamps so printers can embed security in a single press pass. Long-run contracts incentivise end-to-end traceability platforms and open replacement cycles for high-resolution readers. Similar legislation is under review in ASEAN, suggesting a second wave of demand by 2028.
Limited Read Range versus Chipped UHF Systems
Chipless tags typically peak at 3 m in free air, compared with over 10 m for chipped UHF tags, forcing warehouses to increase reader density, which can double infrastructure budgets. Multi-layer metamaterial antennas now in prototype add 40% range, yet metallic racks and liquid contents still attenuate signals. Integrators respond with zone-based portals and hybrid deployments, reserving chipless tags for package-level items while pallets continue to carry chipped inlays.
Other drivers and restraints analyzed in the detailed report include:
- Printable Conductive-Ink Advances in North American Label Converting
- Passive Sensor Adoption for Cold-chain Healthcare Logistics
- Absence of Harmonised ISO / IEC Encoding Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tag sales generated 70.42% of 2025 revenue, underscoring their indispensability across every deployment scenario in the chipless RFID market. Asian contract printers leverage scale to drive unit costs down, while European security printers focus on high-value authenticators. Middleware revenues, although smaller today, are set to climb faster at a 26.05% CAGR because enterprises require cloud connectors, data cleansing, and analytics to turn raw RF echoes into actionable dashboards.
Accelerated middleware growth alters bargaining power; software vendors now influence hardware design road maps and push for open APIs. As a result, tag manufacturers invest in data-services teams to defend share. The trend positions middleware as a gatekeeper for future functionality such as predictive maintenance and AI-based signature matching.
Screen printing held a 37.35% share in 2025 thanks to long-run productivity and mature supply chains, especially within food and beverage packaging. The chipless RFID market now sees ink-jet processes expanding at 27.15% CAGR because droplet-on-demand heads create fine-line antennas suitable for high-density signature encoding.
Ink-jet adoption also supports on-site customisation. Brand owners can print limited-edition authenticity marks days before product launch, cutting obsolescence risk. Screen lines keep their advantage in very high-volume SKUs where tooling amortisation offsets changeover costs. Hybrid lines that start with screen for ground planes and finish with ink-jet for micro-antennas are gaining traction, reflecting a transition phase rather than outright displacement.
Complete Report Scope:
- By Product Type
- Tag
- Reader
- Middleware
- By Operating Frequency
- LF (125-134 kHz)
- HF (13.56 MHz)
- UHF (860-960 MHz)
- By Material
- Silver-nano Ink
- Copper-based Ink
- Graphene/Carbon Ink
- By Application
- Smart Cards
- Smart Tickets
- Brand and Document Authentication
- Asset Tracking
- By End-user Industry
- Retail and E-commerce
- Healthcare and Pharmaceuticals
- Logistics and Transportation
- Banking, Financial Services and Insurance (BFSI)
- Government and Public Sector
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific led the chipless RFID market with 39.30% revenue in 2025. China's converters run integrated screen and flexographic lines, serving domestic and export FMCG brands, while Japanese rail operators extend RFID-enabled fare systems to rural routes. Australia's postal service is trialling chipless tags on cross-border parcels to cut declaration fraud. Regional governments co-fund research into biodegradable substrates, aligning with zero-plastic directives.
North America follows with strong intellectual-property portfolios and an early-adopter customer base in healthcare and aerospace. Universities collaborate with start-ups to commercialise graphene inks, and federal grants support secure supply chains for biologics and critical spare parts. Supermarket chains deploy chipless tags to reduce perishables wastage and tie item-level data into ESG reporting.
Europe ranks third yet posts steady gains driven by anti-counterfeiting mandates. Tax-stamp programs in Italy and Poland stipulate chipless RF security layers. Nordic packaging firms integrate paper inlays to meet circular-economy targets, and German machine builders ship modular ink-jet heads to Asian OEMs. The Middle East & Africa region, while smaller today, is the fastest growing; GCC central banks standardise banknote RF authentication and South African customs rolls out chipless seals on high-value exports.
- Alien Technology
- Avery Dennison
- Zebra Technologies
- SATO Holdings
- Smartrac Technology
- NXP Semiconductors
- Thinfilm Electronics ASA
- PragmatIC Semiconductor
- Impinj Inc.
- Stora Enso
- Spectra Systems Corp.
- Linxens
- TagSense
- Tageos SA
- Variuscard GmbH
- IDTRONIC GmbH
- SML Group
- Toppan Printing Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Deliverables
- 1.2 Study Assumptions
- 1.3 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Lower-cost Mass-production of IC-less Tags in Asian FMCG Packaging
- 4.2.2 Government Excise/Tax-stamp Mandates (EU Counter-feiting)
- 4.2.3 Printable Conductive-Ink Advances in North American Label Converting
- 4.2.4 Passive Sensor Adoption for Cold-chain Healthcare Logistics
- 4.2.5 Banknote and Secure-Document Authentication Demand (Middle East)
- 4.3 Market Restraints
- 4.3.1 Limited Read Range vs. Chipped UHF Systems
- 4.3.2 Absence of Harmonised ISO/IEC Encoding Standards
- 4.3.3 Retrofit Cost of Reader Infrastructure
- 4.3.4 Moisture and Abrasion Vulnerability of Printed Antennas
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.5.1 Printing Technologies
- 4.5.1.1 Ink-jet
- 4.5.1.2 Screen
- 4.5.1.3 Flexographic
- 4.5.1.4 Gravure
- 4.5.1 Printing Technologies
- 4.6 Regulatory Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Tag
- 5.1.2 Reader
- 5.1.3 Middleware
- 5.2 By Operating Frequency
- 5.2.1 LF (125-134 kHz)
- 5.2.2 HF (13.56 MHz)
- 5.2.3 UHF (860-960 MHz)
- 5.3 By Material
- 5.3.1 Silver-nano Ink
- 5.3.2 Copper-based Ink
- 5.3.3 Graphene/Carbon Ink
- 5.4 By Application
- 5.4.1 Smart Cards
- 5.4.2 Smart Tickets
- 5.4.3 Brand and Document Authentication
- 5.4.4 Asset Tracking
- 5.5 By End-user Industry
- 5.5.1 Retail and E-commerce
- 5.5.2 Healthcare and Pharmaceuticals
- 5.5.3 Logistics and Transportation
- 5.5.4 Banking, Financial Services and Insurance (BFSI)
- 5.5.5 Government and Public Sector
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 GCC
- 5.6.5.2 South Africa
- 5.6.5.3 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Alien Technology
- 6.4.2 Avery Dennison
- 6.4.3 Zebra Technologies
- 6.4.4 SATO Holdings
- 6.4.5 Smartrac Technology
- 6.4.6 NXP Semiconductors
- 6.4.7 Thinfilm Electronics ASA
- 6.4.8 PragmatIC Semiconductor
- 6.4.9 Impinj Inc.
- 6.4.10 Stora Enso
- 6.4.11 Spectra Systems Corp.
- 6.4.12 Linxens
- 6.4.13 TagSense
- 6.4.14 Tageos SA
- 6.4.15 Variuscard GmbH
- 6.4.16 IDTRONIC GmbH
- 6.4.17 SML Group
- 6.4.18 Toppan Printing Co.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

