PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113974
PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113974
Capacitive Ceramic Pressure Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the capacitive ceramic pressure sensors market size is expected to grow from USD 1.06 billion in 2025 to USD 1.14 billion in 2026 and is forecast to reach USD 1.61 billion by 2031 at 7.18% CAGR over 2026-2031.
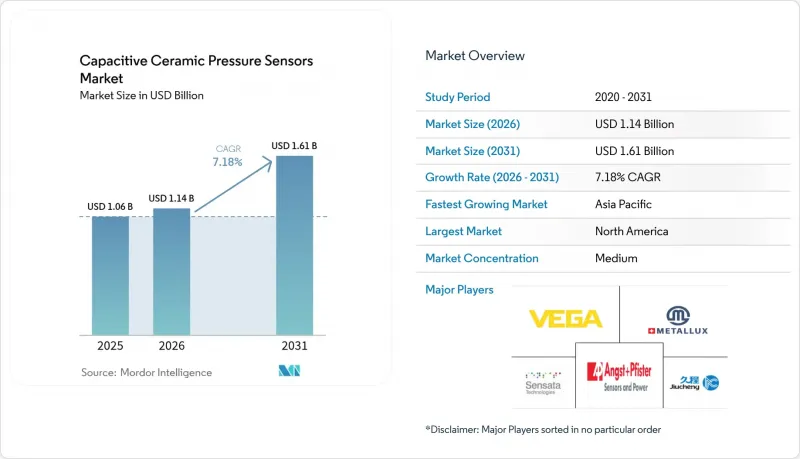
This report is Segmented by Sensor Type (Absolute, Gauge, Differential, and Sealed), Application (Automotive and Transportation, Industrial, Medical and Healthcare, and More), Pressure Range (Low-Pressure, Medium-Pressure, and High-Pressure), End-Use Industry (Automotive OEMs, Industrial OEMs, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Capacitive Ceramic Pressure Sensors Market Trends and Insights
Regulatory mandates for TPMS drive automotive integration
Safety rules such as FMVSS 138 in the United States and ECE R64 in Europe require tire pressure monitoring in every new passenger vehicle, locking in stable demand for robust sensing solutions. Ceramic capacitive elements preserve calibration from -40 °C to +125 °C, whereas silicon MEMS variants drift above +85 °C. Electric-vehicle makers additionally install ceramic units in sealed battery enclosures to monitor pack pressure during rapid charging events that create thermal spikes. The move toward 800 V powertrains elevates electromagnetic interference, yet ceramic devices exhibit lower intrinsic noise than semiconductor alternatives, helping automakers protect data integrity. In 2024, automotive OEMs accounted for 35.83% of global offtake, underscoring the segment's volume influence.
Industry 4.0 retrofits accelerate industrial sensor adoption
Factories modernizing under Industry 4.0 connect established controllers with digital feedback loops and predictive-maintenance software. Ceramic capacitive sensors ship with 4-20 mA and IO-Link outputs, enabling rapid plant-wide installation without rewiring legacy input cards. Corrosion-proof diaphragms minimize unplanned downtime caused by caustic cleaners or acidic process media. As analytics platforms rank sensor stability above lowest piece-price, ceramic units benefit from life-cycle savings that outweigh higher purchase cost. Wireless gateways exploit their low leakage current to extend battery life in remote assets. Industrial OEMs now form the second-largest buyer cohort, particularly in chemical and pulp-and-paper lines operating up to 500 °C.
Cost competition from silicon MEMS alternatives pressures pricing
High-volume MEMS fabs ship basic piezoresistive sensors below USD 5, whereas ceramic capacitive units often list between USD 15-50 depending on range and certification tier. Consumer IoT buyers frequently accept tighter temperature deratings to hit aggressive bill-of-materials targets. While ceramics hold favor in harsh settings, downward price pressure forces makers to streamline LTCC firing cycles and automate final calibration. Some vendors now co-package thin-film signal conditioners to eliminate external electronics and trim module cost.
Other drivers and restraints analyzed in the detailed report include:
- Post-pandemic medical device expansion boosts precision requirements
- Ceramic sensors' high-temperature and chemical-resistance edge
- High ceramic manufacturing costs limit market penetration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gauge devices accounted for 38.32% of the capacitive ceramic pressure sensors market in 2025, reflecting wide deployment in tire pressure monitoring, brake hydraulics, and industrial compressors. The capacitive ceramic pressure sensors market size for gauge designs stood at USD 0.41 billion the same year and is projected to expand steadily as electric-vehicle makers integrate in-wheel pressure nodes. Automotive compliance cycles drive steady, high-volume bids, enabling suppliers to amortize their tooling investments. In parallel, the rollout of smart meters by water utilities is creating incremental demand for gauges, as submerged installations favor ceramic corrosion immunity.
Differential variants are projected to advance at an 7.96% CAGR through 2031, driven by HVAC filter monitoring and fuel-cell stack management. These devices exploit the inherent linearity of capacitive plates to resolve sub-20 Pa pressure drops, a key metric in medical ventilators. Absolute and sealed sensors together occupy a modest niche but gain relevance in altitude drones and deep-well pumping. Across the broader capacitive ceramic pressure sensor market, technology vendors are increasingly bundling digital ASICs inside stainless housings to simplify installation.
Automotive and transportation dominated revenue with 41.25% share in 2025, underpinned by statutory TPMS inclusion and emerging battery-pack pressure loops. Vehicle architectures adopting 800 V inverters generate electromagnetic fields that ceramic sensors tolerate without signal distortion, protecting traction-control algorithms. Rail operators also specify ceramic diaphragms for brake-line safety in alpine routes where -40 °C ambient is routine.
Medical and healthcare spending accelerates fastest at an 8.06% CAGR to 2031, fueled by intensive-care ventilators, infusion pumps, and dialysis circuits that demand zero drift over thousands of sterilization cycles. The capacitive ceramic pressure sensors market size for medical equipment is predicted to reach USD 0.32 billion by 2031, translating into meaningful supply contracts for firms holding ISO 13485 lines. Long-term home respiratory therapy and remote monitoring further widen the revenue funnel as aging populations seek outpatient options.
Industrial automation remains a resilient third pillar. Plants handling sulfuric acid, ammonia, or hydrogen sulfide migrate to ceramic inserts because polymer MEMS coatings blister under chemical attack. Consumer wearables adopt miniature ceramic chips for barometric altitude, though volumes remain modest versus automotive.
Complete Report Scope:
- By Sensor Type
- Absolute
- Gauge
- Differential
- Sealed
- By Application
- Automotive and Transportation
- Marine Systems
- Electric and Hybrid Vehicles
- Industrial
- Food and Beverage Processing
- HVAC and Refrigeration
- Energy and Chemical
- Industrial Robotics and Factory Automation
- Medical and Healthcare
- Respiratory and Ventilation Equipment
- Hemodialysis and Infusion Pumps
- Consumer Electronics and IoT
- Other Applications (Aerospace, Smart Agriculture)
- Automotive and Transportation
- By Pressure Range
- Low-Pressure (less than 10 bar)
- Medium-Pressure (10-100 bar)
- High-Pressure (above 100 bar)
- By End-Use Industry
- Automotive OEMs
- Industrial OEMs
- Medical Device Manufacturers
- Process Industries
- Utilities and Energy
- ODMs / Contract Manufacturers
- By Geography
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Mexico
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 38.40% of global sales in 2025 and remains the single largest region thanks to early TPMS legislation, entrenched medical-device clusters, and substantial electric-vehicle output. U.S. sensor suppliers leverage DOE grants targeting hydrogen supply chains to pilot 700 bar ceramic assemblies. Canada's cold-weather truck market values ceramic consistency at -30 °C, supporting domestic Tier-2 fabrication.
Asia-Pacific is the growth engine at 7.97% CAGR. China's EV leaders such as BYD embed ceramic nodes inside blade-battery modules to monitor gas formation during fast charging. Japan's robotics integrators specify alumina diaphragms for six-axis arms that sanitize with pressurized steam. South Korea channels public subsidies into green-hydrogen hubs where electrolyzer stacks operate near 30 bar and demand ceramic reliability. Europe sustains a solid share through German automotive giants Bosch and Continental, which co-develop ceramic chips for next-generation driver-assistance platforms. Scandinavia deploys sensors in offshore wind turbine gearboxes exposed to salt spray and oscillating load cycles. Middle East refiners adopt ceramic packages for sulfur recovery units running above 400 °C, while Africa's mining firms experiment with ceramic telemetry in acid leach pads.
- Sensata Technologies Holding plc
- Metallux SA
- Vega Americas, Inc.
- Pewatron AG
- BD|SENSORS GmbH
- Angst+Pfister Sensors and Power AG
- Nanjing Jiucheng Technology Co. Limited
- Baumer Electric AG
- ifm electronic gmbh
- Sitron Sensores Industriais Ltda.
- Shenzhen Amperon Technology Co., Ltd.
- Suzhou Novosense Microelectronics Co., Ltd.
- TE Connectivity Ltd.
- STMicroelectronics N.V.
- Bosch Sensortec GmbH
- Honeywell International Inc.
- Amphenol Advanced Sensors
- Infineon Technologies AG
- NXP Semiconductors N.V.
- Shanghai Camozzi Automation Co., Ltd.
- WIKA Alexander Wiegand SE and Co. KG
- ABB Ltd.
- Emerson Electric Co.
- Analog Devices, Inc.
- Endress+Hauser Group Services AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory mandates for TPMS and engine management in next-gen vehicles
- 4.2.2 Industry 4.0 retrofits demanding rugged, corrosion-resistant sensors
- 4.2.3 Post-pandemic boom in ventilators and infusion pumps
- 4.2.4 Ceramic sensors' high-temperature and chemical-resistance edge
- 4.2.5 Electro-lyzer pressure monitoring for green-hydrogen plants
- 4.2.6 Chiplet-based sensor-fusion modules for EV battery packs
- 4.3 Market Restraints
- 4.3.1 Cost-competition from piezoresistive MEMS alternatives
- 4.3.2 High tooling and calibration cost of ceramic capacitive lines
- 4.3.3 Supply-risk of high-purity alumina feedstock
- 4.3.4 EMI issues in 800-V EV platforms
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sensor Type
- 5.1.1 Absolute
- 5.1.2 Gauge
- 5.1.3 Differential
- 5.1.4 Sealed
- 5.2 By Application
- 5.2.1 Automotive and Transportation
- 5.2.1.1 Marine Systems
- 5.2.1.2 Electric and Hybrid Vehicles
- 5.2.2 Industrial
- 5.2.2.1 Food and Beverage Processing
- 5.2.2.2 HVAC and Refrigeration
- 5.2.2.3 Energy and Chemical
- 5.2.2.4 Industrial Robotics and Factory Automation
- 5.2.3 Medical and Healthcare
- 5.2.3.1 Respiratory and Ventilation Equipment
- 5.2.3.2 Hemodialysis and Infusion Pumps
- 5.2.4 Consumer Electronics and IoT
- 5.2.5 Other Applications (Aerospace, Smart Agriculture)
- 5.2.1 Automotive and Transportation
- 5.3 By Pressure Range
- 5.3.1 Low-Pressure (less than 10 bar)
- 5.3.2 Medium-Pressure (10-100 bar)
- 5.3.3 High-Pressure (above 100 bar)
- 5.4 By End-Use Industry
- 5.4.1 Automotive OEMs
- 5.4.2 Industrial OEMs
- 5.4.3 Medical Device Manufacturers
- 5.4.4 Process Industries
- 5.4.5 Utilities and Energy
- 5.4.6 ODMs / Contract Manufacturers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Mexico
- 5.5.5.3 Argentina
- 5.5.5.4 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Sensata Technologies Holding plc
- 6.4.2 Metallux SA
- 6.4.3 Vega Americas, Inc.
- 6.4.4 Pewatron AG
- 6.4.5 BD|SENSORS GmbH
- 6.4.6 Angst+Pfister Sensors and Power AG
- 6.4.7 Nanjing Jiucheng Technology Co. Limited
- 6.4.8 Baumer Electric AG
- 6.4.9 ifm electronic gmbh
- 6.4.10 Sitron Sensores Industriais Ltda.
- 6.4.11 Shenzhen Amperon Technology Co., Ltd.
- 6.4.12 Suzhou Novosense Microelectronics Co., Ltd.
- 6.4.13 TE Connectivity Ltd.
- 6.4.14 STMicroelectronics N.V.
- 6.4.15 Bosch Sensortec GmbH
- 6.4.16 Honeywell International Inc.
- 6.4.17 Amphenol Advanced Sensors
- 6.4.18 Infineon Technologies AG
- 6.4.19 NXP Semiconductors N.V.
- 6.4.20 Shanghai Camozzi Automation Co., Ltd.
- 6.4.21 WIKA Alexander Wiegand SE and Co. KG
- 6.4.22 ABB Ltd.
- 6.4.23 Emerson Electric Co.
- 6.4.24 Analog Devices, Inc.
- 6.4.25 Endress+Hauser Group Services AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

