PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114046

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114046
Tuberculosis Diagnostics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the tuberculosis diagnostics market size is expected to increase from USD 2.58 billion in 2025 to USD 2.73 billion in 2026 and reach USD 3.63 billion by 2031, growing at a CAGR of 5.87% over 2026-2031.
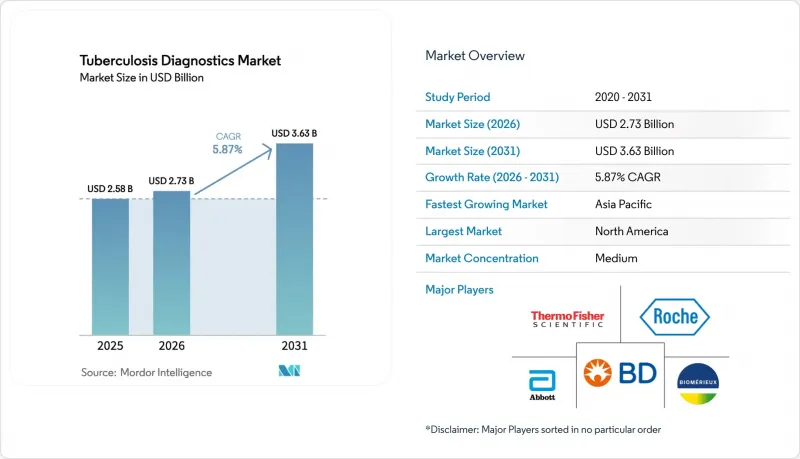
This report is Segmented by Diagnostic Test Type (Culture Based Test, Smear Microscopy, and More), Technology (Culture-Based), Molecular Diagnostics (PCR/NAAT) and More), End-User (Hospital/Clinics, Diagnostics/Research Laboratory, and Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America. The Market Forecasts are Provided in Terms of Value (USD).
Global Tuberculosis Diagnostics Market Trends and Insights
Rising Prevalence of Drug-Resistant TB Strains
Multidrug-resistant tuberculosis cases climbed to an estimated 410,000 globally in 2025, with rifampicin-resistant strains accounting for 3.6% of new cases and 18% of previously treated cases, according to WHO surveillance data. This epidemiological shift is forcing national programs to pivot from empirical treatment to genotypic drug-susceptibility testing, which requires molecular assays capable of detecting mutations in rpoB, katG, and inhA genes within 2 hours. This technical bar only cartridge-based NAAT platforms currently meet at scale. Germany's 5.7% multidrug-resistant incidence and Cote d'Ivoire's 22% rifampicin resistance among retreatment cases show how resistance patterns differ by geography. Xpert MTB/XDR delivers actionable drug profiles in 90 minutes, while Abbott's RealTime MTB RIF/INH assay achieves 94.8% sensitivity for rifampicin and 88.3% for isoniazid, letting clinicians tailor therapy promptly. Nations are also piloting targeted next-generation sequencing to comprehensively map resistance, moving diagnostic workflows from culture-dependent to molecular-first approaches.
WHO Endorsement & National Roll-Outs of NAAT Platforms
WHO's March 2024 guideline update placed molecular rapid tests at the front of all diagnostic algorithms and introduced targeted sequencing advice for drug-resistant surveillance WHO. India's Initiative for Promoting Affordable and Quality TB Tests boosted Xpert uptake tenfold and cut prices by up to 50%, scaling from 56 to 211 labs in five years. Uganda: by decentralizing NAATs to district hospitals, shortened the median time to treatment initiation and increased same-day confirmations, NEJM. WHO prequalification is the de facto gatekeeper for Global Fund, USAID, and UNITAID financing; Cepheid's Ultra assay and Eiken's TB-LAMP together triggered USD 340 million of commitments in 1Q 2025. India's NTEP scaled molecular capacity nationwide, while the Philippines achieved a 1,008% surge in case detection during a Truenat pilot on the Bantayan Islands, where battery-powered devices bypass erratic grid supply. The policy cascade shortens technology diffusion cycles to fewer than 24 months across Asia-Pacific, a timeline once witnessed only in high-income markets.
High Cost of Molecular Tests & Cartridges
Traditional desktop platforms can exceed USD 19,000, whereas Tulane's lab-in-tube device costs under USD 800 and keeps per-test pricing below USD 3. Economic analyses in Brazil and India showed Diaskintest at USD 22.6 and USD 41.0 per correct case, while TSPOT.TB delivered greater effectiveness at incremental costs of USD 55-74. Cepheid's cost-price cartridge offer narrows the gap, yet a sustainable reimbursement model remains critical for widespread adoption.
Other drivers and restraints analyzed in the detailed report include:
- Emergence of AI-Powered Microscopy & Digital Radiology
- Decentralized Near-POC Molecular Platforms
- Shortage of Skilled Laboratory Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, culture-based assays accounted for 38.45% of the revenue, with projections indicating a 6.54% annual growth rate. This increase is driven by WHO guidelines requiring phenotypic confirmation for all rifampicin-resistant cases. While NAAT remains the leading method for primary screening, laboratories are increasingly integrating rapid genotyping with subsequent culture testing. This dual-track workflow enables quick therapy initiation through molecular methods, while culture testing provides detailed insights to optimize treatment regimens.
Continued donor funding sustains the cost-effectiveness of smear microscopy at USD 2 per slide, particularly in regions conducting high volumes of Ziehl-Neelsen tests, such as India. However, as digital microscopy and AI algorithms achieve sensitivity levels comparable to NAAT at significantly lower reagent costs, traditional smear microscopy is gradually being relegated to peripheral triage applications.
Complete Report Scope:
- By Test Type
- Culture-based Tests
- Smear Microscopy
- Nucleic Acid Amplification Tests (NAAT)
- Interferon-Gamma Release Assays (IGRA)
- Tuberculin Skin Test (Mantoux)
- Radiographic & Imaging Tests
- Other Tests
- By Technology
- Culture-based
- Molecular Diagnostics
- Immunoassays
- Radiology / X-ray
- AI-enhanced Digital Microscopy
- Others
- By End-User
- Hospitals & Clinics
- Diagnostic Laboratories
- Academic & Research Institutes
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 39.10% of the tuberculosis diagnostics market in 2025, aided by comprehensive insurance coverage and consistent CDC laboratory upgrades. Asia-Pacific is forecast to expand at a 6.75% CAGR, driven by India's one-third share of the global burden and policy shifts from smear microscopy to NAAT. Europe posted 38,993 cases across 29 EU/EEA nations in 2024; Ukrainian refugee screening recorded 12.8 per 100,000 incidence with 26% multidrug resistance, prompting intensified entry screening. South America benefits from national Xpert scale-up; Brazil's rollout increased notifications by 9.7% and catalyzed multisector coordination. The Middle East and Africa see uneven progress: while Nigeria's AI-linked vans record 1.75 times higher positivity in hotspots, only 4% of labs can run Line Probe Assays. Diaskintest is cheaper than tuberculin in Brazil and India, but TSPOT.TB delivers higher accuracy at added expense, underscoring divergent procurement choices
- Abbott Laboratories
- Beckton Dickinson
- bioMerieux
- Danaher
- Roche
- FUJIFILM
- Hologic
- Luminex Corporation (DiaSorin)
- LumiraDx Ltd.
- Meridian Bioscience
- Molbio Diagnostics Private Limited.
- Oxford Immunotec Ltd.
- QIAGEN
- QuantuMDx Ltd.
- SD Biosensor Inc.
- Seegene
- Siemens Healthineers
- Tauns Laboratories Inc
- Thermo Fisher Scientific
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Drug-Resistant TB Strains
- 4.2.2 WHO Endorsement & National Roll-Outs of NAAT Platforms
- 4.2.3 Government Funding & Global Health Initiatives
- 4.2.4 Emergence of AI-Powered Microscopy & Digital Radiology Triage
- 4.2.5 Decentralised Near-POC Molecular Platforms
- 4.2.6 Subscription-Based Diagnostics-As-A-Service Models
- 4.3 Market Restraints
- 4.3.1 High Cost of Molecular Tests & Cartridges
- 4.3.2 Shortage of Skilled Laboratory Infrastructure
- 4.3.3 Supply-Chain Fragility for Single-Source Cartridges
- 4.3.4 Competition from Emerging Non-Sputum Biomarkers
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Test Type
- 5.1.1 Culture-based Tests
- 5.1.2 Smear Microscopy
- 5.1.3 Nucleic Acid Amplification Tests (NAAT)
- 5.1.4 Interferon-Gamma Release Assays (IGRA)
- 5.1.5 Tuberculin Skin Test (Mantoux)
- 5.1.6 Radiographic & Imaging Tests
- 5.1.7 Other Tests
- 5.2 By Technology
- 5.2.1 Culture-based
- 5.2.2 Molecular Diagnostics
- 5.2.3 Immunoassays
- 5.2.4 Radiology / X-ray
- 5.2.5 AI-enhanced Digital Microscopy
- 5.2.6 Others
- 5.3 By End-User
- 5.3.1 Hospitals & Clinics
- 5.3.2 Diagnostic Laboratories
- 5.3.3 Academic & Research Institutes
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Becton, Dickinson and Company
- 6.3.3 BioMerieux SA
- 6.3.4 Danaher Corporation (Cepheid)
- 6.3.5 F. Hoffmann-La Roche Ltd.
- 6.3.6 Fujifilm Corporation
- 6.3.7 Hologic Inc.
- 6.3.8 Luminex Corporation (DiaSorin)
- 6.3.9 LumiraDx Ltd.
- 6.3.10 Meridian Bioscience
- 6.3.11 Molbio Diagnostics Private Limited.
- 6.3.12 Oxford Immunotec Ltd.
- 6.3.13 Qiagen N.V.
- 6.3.14 QuantuMDx Ltd.
- 6.3.15 SD Biosensor Inc.
- 6.3.16 Seegene Inc.
- 6.3.17 Siemens Healthineers AG
- 6.3.18 Tauns Laboratories Inc
- 6.3.19 Thermo Fisher Scientific Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

