PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114053

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114053
FEVE Fluoropolymer Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the FEVE fluoropolymer coatings market size is expected to grow from USD 200.45 million in 2025 to USD 211.24 million in 2026 and is forecast to reach USD 274.46 million by 2031 at 5.38% CAGR over 2026-2031.
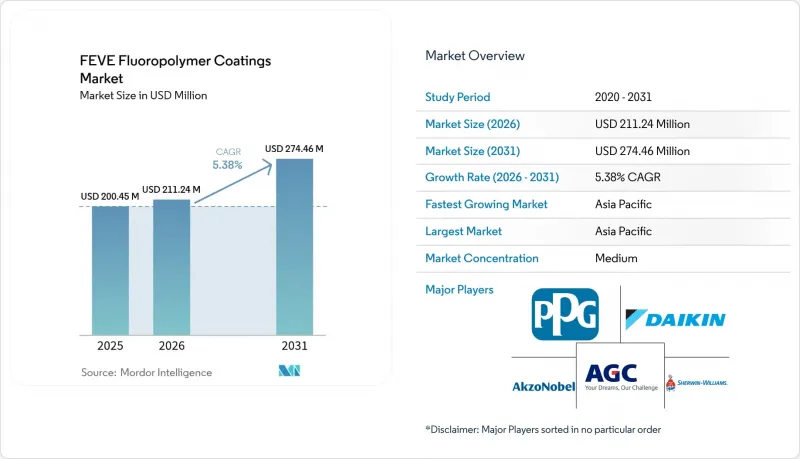
This report is Segmented by End-User Industry (Industrial, Building and Construction, Automotive, Marine, Aviation and Aerospace, and Other End-User Industries) and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global FEVE Fluoropolymer Coatings Market Trends and Insights
Long-Life Facade Demand in Global Construction Boom
Skyscraper developers select FEVE curtain-wall coatings because the annual film erosion rate stays below 0.1 µm, roughly half that of polyurethane, which limits expensive scaffold cycles. The Japan Paint Manufacturers Association values the total 30-year costs at 37% of those for chlorinated rubber systems when repainting savings are factored in. China, the Gulf states, and Southeast Asia supply the largest pipelines of high-rise projects needing American Architectural Manufacturers Association 2605 compliance. Case studies such as Ferrari World Abu Dhabi and Burj al Arab show FEVE protecting aluminum panels under UV swings exceeding 50°C. Lighter cladding panels permitted by seismic codes intensify the need for low-temperature cures that FEVE powders deliver without panel distortion.
Renewable-Energy Hardware Adoption of FEVE Powders
Photovoltaic module backsheets coated with FEVE sustain more than 95% of initial power after one year of outdoor exposure, outperforming uncoated controls by 10 percentage points. Wind-turbine towers utilize single-coat FEVE powder finishes that cure at temperatures below 200 °C, recycle overspray, and resist salt-spray corrosion in offshore environments. Hybrid FEVE/polyurethane blends reinforced with graphene achieve up to 99% leading-edge erosion resistance, supporting megawatt-scale blade production targets in Europe and China. Supply chains value the resin's zero-VOC profile as the U.S. and EU ratchet solvent regulations.
Premium Price Versus Polyurethane Systems
FEVE lists at two to four times the price of polyurethane, discouraging adoption in budget-constrained regions. ChemQuest survey data show 2023 architectural volumes dipped 4.6% as remodelers delayed projects, squeezing budgets and elevating first-cost hurdles. Polysiloxane topcoats, priced at 1.5 times the cost of polyurethane, now capture mid-range demand, especially where operators calculate only five- to 15-year horizons. FEVE vendors respond with lifecycle calculators and training to spotlight 15-30% total cost savings over decades.
Other drivers and restraints analyzed in the detailed report include:
- Industrial Infrastructure Corrosion-Control Programs
- Regulatory Pivot to Low-VOC/High-Durability Coatings
- Rising PFAS-Related Regulatory Scrutiny
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Building and Construction commanded 47.38% of the FEVE Fluoropolymer Coatings market share in 2025, reflecting the segment's early embrace of 30-year, single-coat facade programs. The FEVE Fluoropolymer Coatings market size for this segment is projected to expand at a 6.59% CAGR from 2026 to 2031. Curtain-wall owners credit service life extensions that defer two to three repaint cycles, cutting scaffold expenses and tenant disruption in dense urban cores. Japan's updated bridge standards, which name FEVE as the sole approved topcoat, embed demand across public works.
Industrial equipment follows at a measured pace. Operators in oil and gas weigh FEVE's longer intervals against polysiloxane options that cost 30-40% less. Automotive applications remain niche, covering specialty vehicles and aluminum trim that require UV and chip resistance. Marine and aviation buyers pursue FEVE for antifouling and wire-bundle protection where acceptable alternatives are scarce. Growing retrofit markets in Asia and North America lean on low-odor, waterborne FEVE grades to avoid occupant evacuation. Powder variants win share in factory-coated roof panels and aluminum extrusions because they cure below 200 °C and recycle overspray. Hybrid FEVE-ceramic blends emerge in bridge arch ribs needing color stability and barrier strength. Demand remains price-sensitive in Latin American municipal projects, yet lifecycle calculators reveal 15-30% cost savings that gradually shift procurement criteria.
Complete Report Scope:
- By End-user Industry
- Industrial
- Building & Construction
- Automotive
- Marine
- Aviation & Aerospace
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of APAC
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific governs the FEVE Fluoropolymer Coatings market with a 51.05% share in 2025 and a forecasted 6.42% CAGR, driven by Chinese urbanization, Japanese bridge standards, and South Korean offshore fabrication. Chinese coil coaters offer waterborne grades that meet HG/T 4104-2019 to bypass VOC penalties while preserving a 30-year gloss. Japan's Ministry of Land, Infrastructure, Transport, and Tourism restricts topcoats on public bridges to FEVE, securing premium prices. South Korean yards specify long-life finishes for LNG carrier topsides, reducing dry-dock frequency.
North America accounts for approximately 24.85% of the market. AASHTO's 75-year bridge design life shifts new construction and rehabilitation to FEVE, illustrated by the I-74 Mississippi River Bridge, where Sherwin-Williams Fluorokem shields 3,400 ft of steel. The EPA's aerosol rule tightens VOC controls yet raises compliance efforts through PFAS reporting. Canadian lifecycle studies promote low-VOC solutions that reduce social costs, such as traffic congestion. Mexico sees a selective uptake in refinery and specialty vehicle projects, where long service life offsets capital expenditures.
Europe accounts for 17.80% of the value but faces the steepest regulatory tests. The proposed 50 ppm total-fluorine cap will complicate supply chains. Germany and the Nordics lean on FEVE powder grades for offshore wind towers under QUALICOAT Class 3 standards. Southern Europe's public budgets lag, though airport and retail facades still specify FEVE. Russia's Arctic pipeline opportunities remain limited amid trade sanctions.
- A&I Coatings
- AGC Inc.
- Akzo Nobel N.V.
- Axalta Coating Systems Ltd.
- DAIKIN INDUSTRIES, Ltd.
- IFS Coatings
- Innocoat Systems
- Kansai Paint Co., Ltd.
- KCC CORPORATION
- PPG Industries Inc.
- The Sherwin-Williams Company
- Tnemec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Long-life facade demand in global construction boom
- 4.2.2 Industrial infrastructure corrosion-control programs
- 4.2.3 Regulatory pivot to low-VOC/high-durability coatings
- 4.2.4 Renewable-energy hardware (solar/wind) adopA-tion of FEVE powders
- 4.2.5 Government service-life mandates for public bridges & tanks
- 4.3 Market Restraints
- 4.3.1 Premium price versus polyurethane & acrylic systems
- 4.3.2 Rising PFAS-related regulatory scrutiny in United States/European Union
- 4.3.3 Shortage of trained applicators & specialized spray equipment
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By End-user Industry
- 5.1.1 Industrial
- 5.1.2 Building & Construction
- 5.1.3 Automotive
- 5.1.4 Marine
- 5.1.5 Aviation & Aerospace
- 5.1.6 Other End-user Industries
- 5.2 By Geography
- 5.2.1 Asia-Pacific
- 5.2.1.1 China
- 5.2.1.2 India
- 5.2.1.3 Japan
- 5.2.1.4 South Korea
- 5.2.1.5 ASEAN Countries
- 5.2.1.6 Rest of APAC
- 5.2.2 North America
- 5.2.2.1 United States
- 5.2.2.2 Canada
- 5.2.2.3 Mexico
- 5.2.3 Europe
- 5.2.3.1 Germany
- 5.2.3.2 United Kingdom
- 5.2.3.3 France
- 5.2.3.4 Italy
- 5.2.3.5 Spain
- 5.2.3.6 Russia
- 5.2.3.7 NORDIC Countries
- 5.2.3.8 Rest of Europe
- 5.2.4 South America
- 5.2.4.1 Brazil
- 5.2.4.2 Argentina
- 5.2.4.3 Colombia
- 5.2.4.4 Rest of South America
- 5.2.5 Middle-East and Africa
- 5.2.5.1 Saudi Arabia
- 5.2.5.2 South Africa
- 5.2.5.3 Rest of Middle-East and Africa
- 5.2.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 A&I Coatings
- 6.4.2 AGC Inc.
- 6.4.3 Akzo Nobel N.V.
- 6.4.4 Axalta Coating Systems Ltd.
- 6.4.5 DAIKIN INDUSTRIES, Ltd.
- 6.4.6 IFS Coatings
- 6.4.7 Innocoat Systems
- 6.4.8 Kansai Paint Co., Ltd.
- 6.4.9 KCC CORPORATION
- 6.4.10 PPG Industries Inc.
- 6.4.11 The Sherwin-Williams Company
- 6.4.12 Tnemec
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

