PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114134

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114134
Turbine Control System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the turbine control system market size was valued at USD 21.98 billion in 2025 and estimated to grow from USD 23.16 billion in 2026 to reach USD 30.02 billion by 2031, at a CAGR of 5.36% during the forecast period (2026-2031).
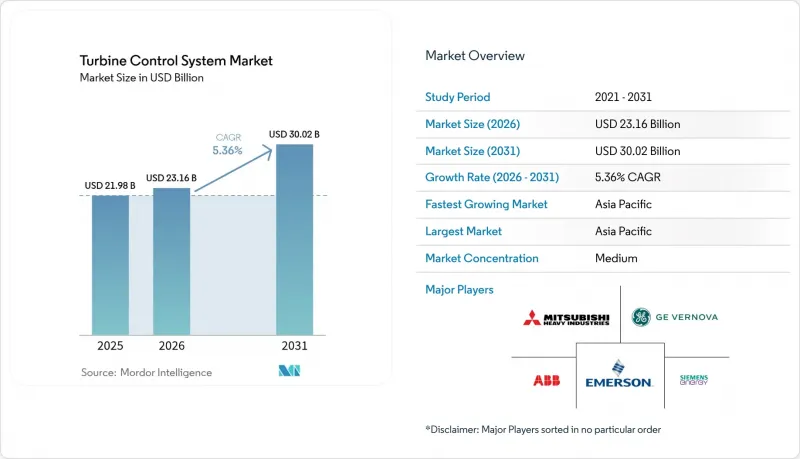
This report is Segmented by Type (Gas Turbine Control Systems, Wind Turbine Control Systems, and More), Function (Speed Control, Load Control, Temperature Control, Pressure Control, and Other Functions), Component (Controllers and PLCs, Services, and More), End-User (Power Generation Utilities, Independent Service Providers, and More), and Geography (North America, Europe, Asia-Pacific, and More).
Global Turbine Control System Market Trends and Insights
Expansion of Wind Capacity Requiring Advanced Pitch & Yaw Controls
Modern 15-MW offshore turbines operate with rotor diameters exceeding 240 m, magnifying aerodynamic loads and structural fatigue. Their control software, therefore, blends pitch, yaw, and torque commands in 20-millisecond cycles to balance power extraction against blade strain. Grid codes in Europe and China add another layer by compelling wind farms to contribute frequency support, forcing controllers to momentarily reduce active power to emulate spinning inertia. Floating installations raise the bar again, as the nacelle must coordinate with mooring-line dynamics in real-time. Suppliers armed with high-fidelity aeroelastic models and edge-computing processors are capturing share in this fast-growing slice of the turbine control systems market.
Reliability Push in Global Gas-Turbine Fleet
As combined-cycle blocks transition from baseload to peaker duty, hot-section parts experience increased temperature cycling and potential flame instability. Mitsubishi Heavy Industries' A-CPFM platform integrates machine learning into the combustion loop, enabling the controller to fine-tune fuel splits and eliminate vibration-driven trips -a feature now validated at the 600 MW Jackson facility in Mississippi. Hydrogen blending introduces further complexity because the flame speed and calorific value differ from those of pure methane; therefore, control logic must track these variables to prevent auto-ignition events. Plant owners, especially in the Middle East, where water desalination relies on cogeneration units, are prioritizing software retrofits that ensure greater than 99% availability.
Declining Fossil CAPEX as Renewables Scale
European utilities such as Vattenfall have sold or mothballed coal and gas assets to unlock capital for offshore wind and battery projects. These divestments lower the addressable base for new turbine control installations. Remaining fossil operators funnel budgets into only the most necessary upgrades-chiefly emissions-compliance and flexible-operation retrofits-rather than full control-room overhauls. The net effect is a shift from green-field hardware awards to brown-field optimization contracts, which tempers overall revenue expansion even as it boosts demand for software licensing and field-service expertise within the turbine control systems industry.
Other drivers and restraints analyzed in the detailed report include:
- AI Data-Center Peak-Demand Surges Driving Fast-Ramp Controls
- Digital-Twin-Enabled Predictive Maintenance
- Cyber-Security & Integration Complexity in Brown-Field Retrofits
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gas platforms supplied 43.40% of the turbine control systems market in 2025, a lead built on their dual role as baseload anchors and rapid-response units when renewable output sags. Machine-learning-infused combustion control now trims start-up fuel consumption by up to 10%, a saving eagerly adopted by merchant-plant operators exposed to volatile spot prices. Conversely, wind solutions are projected to climb a 7.16% CAGR slope between 2026 and 2031, driven by 20 GW per year of global offshore additions that require multi-axis control to handle wake interactions and grid-support duties. The steam and hydro categories, while mature, continue to experience moderate spending, particularly where pumped-storage hydropower is repurposed for long-duration energy storage.
A second factor sustaining gas leadership is hydrogen readiness. OEMs are shipping software updates that adjust firing-temperature maps and diluent-flow curves if blend ratios exceed 30%. Owners of GE 7F and Siemens SGT-800 fleets are therefore opting for incremental control-platform upgrades rather than full hardware swaps. Wind, by contrast, is embracing distributed-edge processors mounted directly in the nacelle so that feedback loops stay below 5 ms despite limited offshore bandwidth. Those architecture shifts are drawing IT-oriented entrants into the turbine control systems market.
Speed control represented 31.95% of 2025 revenues, reflecting its universality across steam, gas, hydro, and wind machines. Even so, auxiliary packages such as vibration suppression, combustion emissions, and cyber-intrusion monitoring will together post a 6.05% CAGR. Emissions modules are trending from simple lookup tables toward adaptive neural-network regulators that balance NOx targets, ramp rates, and fuel blends in real-time. Pressure-control logic, critical in once-through steam generators, is also being upgraded, with new algorithms coordinating variable-speed feed-water pumps to dampen drum-level oscillations. Across all functions, the guiding pattern is convergence: a single high-availability PLC now hosts multiple advanced applications that once required separate controllers, streamlining footprint and maintenance.
The turbine control systems market size attributed to these emerging functions is poised to surpass USD 6.18 billion by 2031 as grid-code revisions tighten inertia, frequency-ride-through, and black-start requirements. For fleet managers, bundling advanced functions into a single license simplifies compliance audits, thereby further boosting adoption.
Complete Report Scope:
- By Type
- Steam Turbine Control Systems
- Gas Turbine Control Systems
- Wind Turbine Control Systems
- Hydro Turbine Control Systems
- By Function
- Speed Control
- Load Control
- Temperature Control
- Pressure Control
- Other Functions
- By Component
- Controllers and PLCs
- Sensors and Transducers
- HMI and SCADA Software
- Actuators and Valves
- Services (Installation, Retrofit, Cyber-security)
- By End-user
- Power Generation Utilities
- Oil and Gas (Upstream, Midstream, Downstream)
- Process Industries (Chemicals, Paper, Metals)
- Marine and Aviation
- Independent Service Providers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
The Asia-Pacific region commanded 38.05% of 2025 revenue and is projected to expand at a 5.78% annual rate through 2031. Chinese offshore wind auctions now stipulate grid-forming capability, prompting developers to specify multi-function controllers right at the bidding stage. India's renovation and modernization program for ~44 GW of subcritical coal units also generates new orders for the turbine control systems market. Southeast Asian countries, particularly Thailand, following its 5,300 MW Bang Pakong CCGT milestone, procure high-efficiency J-class gas turbines whose control suites synchronize eight units across a single 500 kV bus.
North America remains the second-largest region, buoyed by data-center clustering in Texas, Virginia, and Alberta. Local utilities collaborate with turbine OEMs to co-develop "black-park" modes so that aeroderivative units can island sensitive IT loads during grid faults, a capability that commands sizeable service premiums in the turbine control systems industry. Environmental agencies' emphasis on the methane-to-hydrogen transition further accelerates control-software spending, as existing turbines must receive logic capable of handling variable Wobbe-index fuels.
Europe places a strong emphasis on flexible operations and cyber-resilience. Germany's grid operator now rewards fast frequency response of less than 2 seconds, encouraging retrofitted steam units to implement over-fire logic plus advanced governor-valve sequencing. Simultaneously, the EU NIS2 regulation adds legal teeth to cybersecurity obligations, prompting plant owners to adopt monitored firewalls and anomaly-detection analytics. These factors sustain software and services revenue even though green-field fossil builds are rare.
In the Middle East and Africa, combined-cycle and mechanical-drive projects for desalination and midstream gas continue to be active. High ambient temperatures and dust necessitate control algorithms that anticipate compressor surge margins and automate inlet-bleed cooling sequences to prevent compressor surge. South American growth centers on Brazil's pumped-storage assets, which now engage four-quadrant turbines that alternate between generation and motoring, requiring sophisticated transitions that only the latest controllers can coordinate.
- ABB Ltd
- Emerson Electric Co.
- General Electric (GE Vernova)
- Siemens Energy AG
- Honeywell International Inc.
- Rockwell Automation Inc.
- Mitsubishi Heavy Industries Ltd
- Rolls-Royce plc
- Schneider Electric SE
- Woodward Inc.
- Yokogawa Electric Corp.
- Baker Hughes Co.
- Mita-Teknik A/S
- Innoway-Sea Group
- Turbine Controls Ltd
- Eaton Corporation
- Hitachi Energy Ltd
- CCC (Compressor Controls Corp.)
- Voith Turbo GmbH
- Bosch Rexroth AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Modernization of ageing thermal fleets
- 4.2.2 Expansion of wind capacity requiring advanced pitch & yaw controls
- 4.2.3 Reliability push in global gas-turbine fleet
- 4.2.4 AI-data-center peak-demand surges driving fast-ramp controls
- 4.2.5 Digital-twin-enabled predictive maintenance
- 4.3 Market Restraints
- 4.3.1 Declining fossil CAPEX as renewables scale
- 4.3.2 Cyber-security & integration complexity in brown-field retrofits
- 4.3.3 Stricter grid-code inertia limits constraining ramp algorithms
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Steam Turbine Control Systems
- 5.1.2 Gas Turbine Control Systems
- 5.1.3 Wind Turbine Control Systems
- 5.1.4 Hydro Turbine Control Systems
- 5.2 By Function
- 5.2.1 Speed Control
- 5.2.2 Load Control
- 5.2.3 Temperature Control
- 5.2.4 Pressure Control
- 5.2.5 Other Functions
- 5.3 By Component
- 5.3.1 Controllers and PLCs
- 5.3.2 Sensors and Transducers
- 5.3.3 HMI and SCADA Software
- 5.3.4 Actuators and Valves
- 5.3.5 Services (Installation, Retrofit, Cyber-security)
- 5.4 By End-user
- 5.4.1 Power Generation Utilities
- 5.4.2 Oil and Gas (Upstream, Midstream, Downstream)
- 5.4.3 Process Industries (Chemicals, Paper, Metals)
- 5.4.4 Marine and Aviation
- 5.4.5 Independent Service Providers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Chile
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Emerson Electric Co.
- 6.4.3 General Electric (GE Vernova)
- 6.4.4 Siemens Energy AG
- 6.4.5 Honeywell International Inc.
- 6.4.6 Rockwell Automation Inc.
- 6.4.7 Mitsubishi Heavy Industries Ltd
- 6.4.8 Rolls-Royce plc
- 6.4.9 Schneider Electric SE
- 6.4.10 Woodward Inc.
- 6.4.11 Yokogawa Electric Corp.
- 6.4.12 Baker Hughes Co.
- 6.4.13 Mita-Teknik A/S
- 6.4.14 Innoway-Sea Group
- 6.4.15 Turbine Controls Ltd
- 6.4.16 Eaton Corporation
- 6.4.17 Hitachi Energy Ltd
- 6.4.18 CCC (Compressor Controls Corp.)
- 6.4.19 Voith Turbo GmbH
- 6.4.20 Bosch Rexroth AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

