PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114137

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114137
Admission Management Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the admission management software market size was valued at USD 1.46 billion in 2025 and estimated to grow from USD 1.59 billion in 2026 to reach USD 2.41 billion by 2031, at a CAGR of 8.71% during the forecast period (2026-2031).
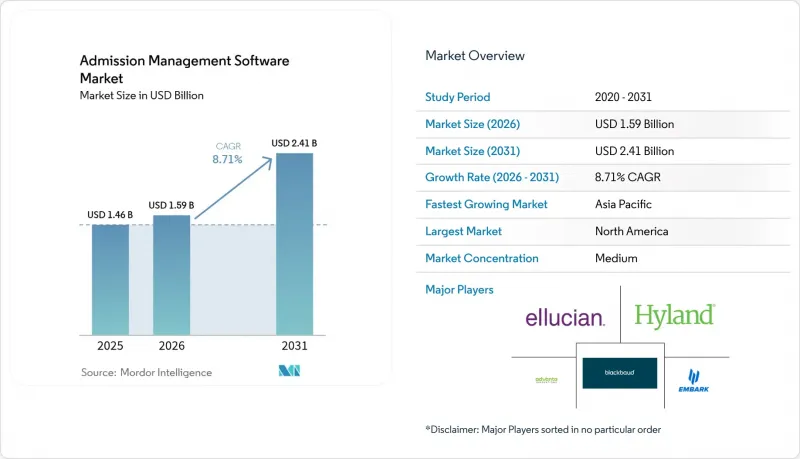
This report is Segmented by Component (Software, Services), Deployment Mode (Cloud, On-Premises), Application (Click Path and Website Optimization, Basket Analysis and Personalization and More), Industry Vertical (Retail and E-Commerce, Media and Entertainment and More), Organization Size (Large Enterprises and SMEs), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Admission Management Software Market Trends and Insights
Phasing-out of third-party cookies fuels first-party analytics
Google's shifting cookie-deprecation schedule created a sense of urgency rather than relief. Enterprises that invested early in cookieless pipelines now highlight stronger consent compliance and richer first-party datasets, prompting competitors to accelerate similar upgrades. Vendors are embedding Privacy Sandbox workflows and customer data platforms into the admission management software market, enabling unified profiles across web, mobile and owned media. Early adopters anticipate smoother transitions as regulatory scrutiny intensifies.
E-commerce push for real-time personalization and conversion lift
Personalisation has become table stakes. Retailers report sales uplifts of about 20% when product recommendations react instantly to clicks, driving heavy demand for streaming analytics and low-latency decision engines. The admission management software market benefits because point-and-click tooling lets marketers launch dynamic offers without deep coding skills, while machine learning models surface next-best actions within milliseconds of each interaction.
Global privacy regulations tighten data collection
Nineteen US states added stricter consent mandates in 2025, while GDPR fines rose, forcing analytics pipelines to reduce personally identifiable data. Vendors that bundle automated consent management within the admission management software market gain favour, yet privacy filters remove some behavioural detail, limiting model accuracy and restraining overall CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Cloud cost efficiency enables massive click-data ingestion
- Digital-marketing ROI pressure drives journey analytics
- Integration complexity across streaming stacks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The software segment held 60.35% of admission management software market share in 2025, underscoring the primacy of platforms that map every click to revenue outcomes. Yet services revenue is rising at a 13.05% CAGR because enterprises need hands-on help aligning data governance, privacy and machine-learning models with business goals. The admission management software market relies on integrators to orchestrate complex hybrid cloud topologies and fine-tune user-journey dashboards.
A second growth driver is changing management. Large rollouts often fail when end-users cannot interpret new metrics. Advisory partners therefore bundle enablement workshops, experimentation playbooks, and continuous optimisation audits. As privacy rules evolve, recurring compliance assessments expand services billings, narrowing the gap with pure-play licences.
Cloud deployments captured 67.75% of admission management software market size in 2025 and are scaling at a 14.02% CAGR. Elastic compute absorbs traffic surges during seasonal campaigns, while managed security controls help satisfy emerging cross-border data regulations. Real-time AI features-such as automated anomaly flags-tend to launch first on SaaS editions, further accelerating cloud preference.
On-premises persists in sectors with strict data-sovereignty clauses, but most of these organisations are introducing hybrid patterns that keep sensitive identifiers inside the firewall yet stream event aggregates to cloud analytics engines. Over the forecast window, existing licence renewals increasingly convert to SaaS, reinforcing the admission management software market's subscription-based revenue mix.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud
- On-premise
- By Application
- Click Path and Website Optimization
- Customer Analysis
- Basket Analysis and Personalization
- Traffic Analysis
- Website / App Performance Optimization
- By Industry Vertical
- Retail and E-commerce
- Media and Entertainment
- BFSI
- Telecommunications and IT
- Travel and Hospitality
- Healthcare
- Others
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America delivered 41.10% of global revenue in 2025 due to high digital-commerce penetration, mature cloud infrastructure, and concentration of leading vendors. Enterprises in the region treat analytics as a make-or-break competency, funnelling budgets into AI augmentation and privacy-by-design frameworks. While growth is slowing as adoption saturates, wallet share remains high because buyers expand use cases within the same platforms, sustaining account-based revenue.
Europe ranks second, driven by GDPR-induced demand for platforms that blend insight depth with strict consent controls. Vendors localise data-hosting options and integrate multilingual consent banners, boosting uptake in Germany, France and the Nordics. The admission management software market benefits from pan-EU data-transfer rules that favour providers offering in-region datacentres and advanced security certifications. Growth is steady as organisations embed analytics deeper into marketing resource-management workflows.
Asia-Pacific is the flash-growth engine, forecast to log a 15.38% CAGR. Mobile-first consumer behaviour in India, Indonesia and the Philippines requires multi-device identity stitching, pushing local firms to adopt event-stream analytics early. Generative-AI-centric feature sets resonate with digitally native start-ups eager for low-code insight extraction. Regional governments' push for cross-border data flows and cloud adoption further enlarges the admission management software market, especially in e-payments and super-app ecosystems.
- Adobe Inc.
- Google LLC (Google Analytics / GA4)
- Microsoft Corp. (Azure Data Explorer)
- IBM Corp. (Tealeaf / Watson CX)
- Oracle Corp. (Oracle CX Suite)
- SAP SE (Customer Data Platform)
- Amplitude Inc.
- Mixpanel Inc.
- Heap Inc.
- Piano Analytics (AT Internet)
- Contentsquare SA
- FullStory Inc.
- Quantum Metric Inc.
- Snowplow Analytics Ltd
- Hotjar Ltd
- Crazy Egg Inc.
- Matomo (Innocraft Ltd)
- Piwik PRO SA
- Twilio Inc. (Segment CDP)
- Yandex Metrica (YANDEX LLC)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Phasing-out of third-party cookies fuels first-party analytics
- 4.2.2 E-commerce push for real-time personalization and conversion lift
- 4.2.3 Cloud cost efficiency enables massive click-data ingestion
- 4.2.4 Digital-marketing ROI pressure drives journey analytics
- 4.2.5 Edge browser analytics (Wasm) preserves privacy-by-design
- 4.2.6 Retail-media networks monetise aggregated click panels
- 4.3 Market Restraints
- 4.3.1 Global privacy regulations tighten data collection
- 4.3.2 Integration complexity across streaming stacks
- 4.3.3 Browser anti-tracking (ITP, ETP) erodes data fidelity
- 4.3.4 Scarcity of event-stream engineering talent
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.3 By Application
- 5.3.1 Click Path and Website Optimization
- 5.3.2 Customer Analysis
- 5.3.3 Basket Analysis and Personalization
- 5.3.4 Traffic Analysis
- 5.3.5 Website / App Performance Optimization
- 5.4 By Industry Vertical
- 5.4.1 Retail and E-commerce
- 5.4.2 Media and Entertainment
- 5.4.3 BFSI
- 5.4.4 Telecommunications and IT
- 5.4.5 Travel and Hospitality
- 5.4.6 Healthcare
- 5.4.7 Others
- 5.5 By Organisation Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium Enterprises
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Israel
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 United Arab Emirates
- 5.6.5.4 Turkey
- 5.6.5.5 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Google LLC (Google Analytics / GA4)
- 6.4.3 Microsoft Corp. (Azure Data Explorer)
- 6.4.4 IBM Corp. (Tealeaf / Watson CX)
- 6.4.5 Oracle Corp. (Oracle CX Suite)
- 6.4.6 SAP SE (Customer Data Platform)
- 6.4.7 Amplitude Inc.
- 6.4.8 Mixpanel Inc.
- 6.4.9 Heap Inc.
- 6.4.10 Piano Analytics (AT Internet)
- 6.4.11 Contentsquare SA
- 6.4.12 FullStory Inc.
- 6.4.13 Quantum Metric Inc.
- 6.4.14 Snowplow Analytics Ltd
- 6.4.15 Hotjar Ltd
- 6.4.16 Crazy Egg Inc.
- 6.4.17 Matomo (Innocraft Ltd)
- 6.4.18 Piwik PRO SA
- 6.4.19 Twilio Inc. (Segment CDP)
- 6.4.20 Yandex Metrica (YANDEX LLC)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

