PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114171

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114171
AI In Agriculture - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the aI in agriculture market size is expected to grow from USD 2.43 billion in 2025 to USD 3.11 billion in 2026 and is forecast to reach USD 8.39 billion by 2031 at a 21.96% CAGR over 2026-2031.
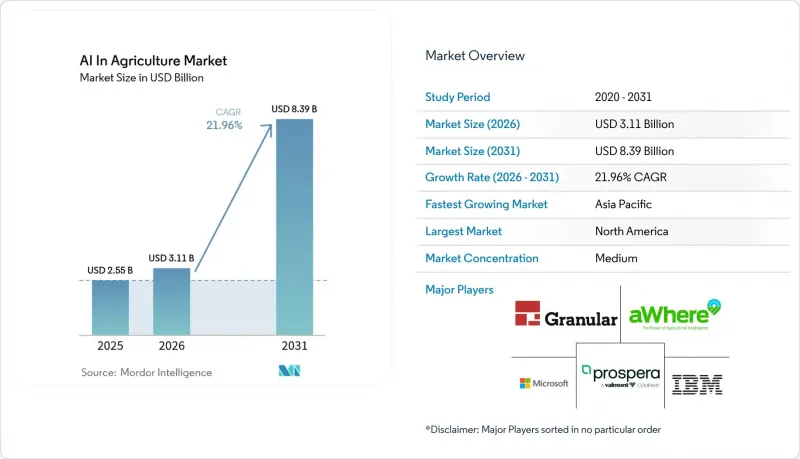
This report is Segmented by Application (Precision Farming, Livestock Monitoring, Drone Analytics, Smart Greenhouse Management, and Supply-Chain and Post-Harvest Optimization), Technology (Machine Learning, Computer Vision, and More), Component (Hardware, Software Platforms, and Services), Deployment Mode (Cloud, and Hybrid), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global AI In Agriculture Market Trends and Insights
Rapid Adoption of Precision Agriculture Platforms
Deere and Company embedded machine-learning algorithms into its Operations Center in 2025, allowing the platform to ingest multi-year yield maps and soil conductivity readings, then automatically generate seeding prescriptions that trimmed seed outlays by 8-12% for early adopters. Trimble followed in early 2026 by layering generative-AI report-writing tools onto its Ag Software suite, letting farm managers brief financiers without manually compiling dashboards. Carbon-accounting modules are now standard add-ons because protocols such as Verra VM0042 require plot-level quantification of sequestration before issuing credits. As growers trade verified carbon credits, they reinvest proceeds into additional sensors, reinforcing data network effects. The result is a flywheel in which platform usage deepens each season, making switching increasingly costly.
Expansion of High-Resolution Drone and Satellite Imagery Services
PrecisionHawk launched a 2025 service tier that fuses drone imagery with Sentinel-1 synthetic-aperture radar, providing all-weather soil-moisture and biomass maps. Aerobotics deployed computer-vision models in 2026 to count individual citrus fruit, enabling packers to lock forward contracts six weeks earlier than before. Planet Labs' SuperDove constellation now revisits every field daily at 3-meter resolution, giving agronomists near-real-time feedback for double-cropping systems. Such temporal density compresses decision cycles and minimizes yield penalties caused by timing errors.
Fragmented Agronomic Data Standards
Only 30% of farm-management software vendors had adopted AgGateway's ADAPT data-exchange framework by 2025, forcing growers to reconcile incompatible file formats when switching suppliers. Soil taxonomies diverge; the USDA recognizes 12 soil orders, while the World Reference Base lists 32, confounding model portability. Weather-station protocols and pest nomenclatures vary, degrading forecast accuracy when datasets are pooled internationally. Vendors must build and maintain regional models, inflating development costs and delaying feature launches.
Other drivers and restraints analyzed in the detailed report include:
- Government Digital-Farming Subsidies and Mandates
- Affordable Cloud-Based AI-as-a-Service Offerings
- High Upfront Cost of Sensors and Robotics for Smallholders
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Precision farming held the largest AI in agriculture market share at 43.29% in 2025, reflecting widespread variable-rate equipment on corn and soybean acres. Smart greenhouse management, however, is projected to lead application growth, expanding at 22.47% through 2031. Intelligent Growth Solutions' generative-AI copilot fine-tunes CO2 levels and LED spectra every few minutes, enabling vertical farms to cut energy use by 18% without yield loss. Livestock monitoring is gaining velocity as computer-vision systems flag lameness and calving risks days in advance, reducing vet costs and mortality. Drone analytics maintains a mid-teens position but can rise once regulators enable beyond-visual-line-of-sight flights.
Dense greenhouse datasets sensor readings every five minutes across dozens of variables accelerate model iteration, whereas open-field crops produce sparser data, slowing algorithm refinement. Certifications such as GlobalGAP are beginning to require AI-enabled traceability, nudging post-harvest optimization platforms into mainstream budgets. As a result, the AI in agriculture market size for controlled-environment applications is on track to close part of the gap with mainstream row crops by 2031.
Machine learning commanded 48.19% of 2025 spending, anchoring the broader AI in agriculture market. Computer vision, though smaller, is forecast to expand at 22.68% over 2026-2031, outpacing other technologies as drone fleets and edge processors proliferate. Deere's See and Spray system uses convolutional networks to differentiate crops from weeds at 20 frames per second, cutting herbicide use by up to 90%. Taranis captures sub-millimeter imagery to spot early fungal lesions, enabling fungicide precision that lowers chemical bills by 30-40%.
Edge-inference chips such as NVIDIA Jetson Orin and Google Coral now retail below USD 200, allowing real-time processing on sprayers without cloud latency. European AI-Act proposals that rate some agricultural systems as "limited risk" could tilt demand toward interpretable algorithms, adding a regional flavour to global technology splits. In numerical terms, the computer-vision segment's share of AI in agriculture market size is projected to climb steadily, even as machine learning retains core workload dominance.
Complete Report Scope:
- By Application
- Precision Farming
- Livestock Monitoring
- Drone Analytics
- Smart Greenhouse Management
- Supply-Chain and Post-Harvest Optimization
- By Technology
- Machine Learning
- Computer Vision
- Predictive Analytics
- Natural-Language Processing (NLP)
- By Component
- Hardware (Sensors, Drones, Robots)
- Software Platforms
- Services (Consulting, Integration, Support)
- By Deployment Mode
- Cloud
- On-Premise
- Hybrid
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America commanded 38.91% of 2025 spending thanks to high penetration of GPS-guided machinery, broadband coverage in rural counties, and climate-smart subsidies. USDA's Conservation Stewardship revisions reimburse up to 75% of AI sensor and software costs when nutrient plans are machine-verified. Canada's Agricultural Clean Technology Program disbursed CAD 50 million (USD 37 million) in 2025 for precision-farming gear. Mexico's avocado exporters now integrate AI traceability to meet United States import rules. Labor limits still slow fully autonomous robots pending regulatory clearance.
Asia-Pacific is projected to grow fastest at a 22.98% CAGR through 2031. China's 200 smart-farm zones mandate local AI stack deployment, anchoring domestic cloud partnerships. India's Kisan Suvidha serves 50 million users with satellite-based advisories. Japan targets 100,000 hectares under autonomous tractors by 2027 to offset rural aging. Australia leverages AI evapotranspiration models to ration Murray-Darling water. Regulatory divergence from China's data-localization rules to India's consent-based regime forces vendors to regionalize data flows, yet demand outstrips these frictions.
Europe, South America, the Middle East, and Africa each held single-digit to low-teens slices in 2025. The EU earmarks over one-third of rural-development funds for digital farming, spurring sensor rollouts across Germany and Poland. Brazil's Agro 4.0 tax incentives catalyse AI uptake on soybean estates. Saudi Arabia's National Center for Agriculture Technology backs AI-optimized vertical farms to cut import dependency. South Africa's citrus packers deploy computer-vision grading to meet EU standards, while Nigeria pilots satellite crop monitoring for rice in the Niger Delta. Collectively, these initiatives expand the global AI in agriculture market, even where infrastructure gaps persist.
- Microsoft Corporation
- IBM Corporation
- Deere and Company
- Trimble Inc.
- Bayer Crop Science - Climate FieldView
- Granular Inc.
- Prospera Technologies Ltd.
- Gamaya SA
- aWhere Inc.
- CropX Technologies
- Taranis
- Raven Industries
- PrecisionHawk Inc.
- AgEagle Aerial Systems
- Aerobotics
- Syngenta Group
- Topcon Agriculture
- Tule Technologies Inc.
- Intelligent Growth Solutions (IGS)
- Blue River Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Precision Agriculture Platforms
- 4.2.2 Expansion of High-Resolution Drone and Satellite Imagery Services
- 4.2.3 Government Digital-Farming Subsidies and Mandates
- 4.2.4 Affordable Cloud-Based AI-as-a-Service Offerings
- 4.2.5 On-Farm GenAI Copilots Reducing Agronomist Field Visits
- 4.2.6 5G Open-RAN Sub-Meter Positioning for Autonomous Robots
- 4.3 Market Restraints
- 4.3.1 Fragmented Agronomic Data Standards
- 4.3.2 High Upfront Cost of Sensors and Robotics for Smallholders
- 4.3.3 Limited AI-Ready Agronomic Datasets and Privacy Hurdles
- 4.3.4 Slow Soil-Carbon Credit Verification Cycles
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Precision Farming
- 5.1.2 Livestock Monitoring
- 5.1.3 Drone Analytics
- 5.1.4 Smart Greenhouse Management
- 5.1.5 Supply-Chain and Post-Harvest Optimization
- 5.2 By Technology
- 5.2.1 Machine Learning
- 5.2.2 Computer Vision
- 5.2.3 Predictive Analytics
- 5.2.4 Natural-Language Processing (NLP)
- 5.3 By Component
- 5.3.1 Hardware (Sensors, Drones, Robots)
- 5.3.2 Software Platforms
- 5.3.3 Services (Consulting, Integration, Support)
- 5.4 By Deployment Mode
- 5.4.1 Cloud
- 5.4.2 On-Premise
- 5.4.3 Hybrid
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 IBM Corporation
- 6.4.3 Deere and Company
- 6.4.4 Trimble Inc.
- 6.4.5 Bayer Crop Science - Climate FieldView
- 6.4.6 Granular Inc.
- 6.4.7 Prospera Technologies Ltd.
- 6.4.8 Gamaya SA
- 6.4.9 aWhere Inc.
- 6.4.10 CropX Technologies
- 6.4.11 Taranis
- 6.4.12 Raven Industries
- 6.4.13 PrecisionHawk Inc.
- 6.4.14 AgEagle Aerial Systems
- 6.4.15 Aerobotics
- 6.4.16 Syngenta Group
- 6.4.17 Topcon Agriculture
- 6.4.18 Tule Technologies Inc.
- 6.4.19 Intelligent Growth Solutions (IGS)
- 6.4.20 Blue River Technology
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

