PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114275

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114275
Plastisols - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the plastisols market size is estimated at USD 7.15 billion in 2026, and is expected to reach USD 9.67 billion by 2031, at a CAGR of 6.22% during the forecast period (2026-2031).
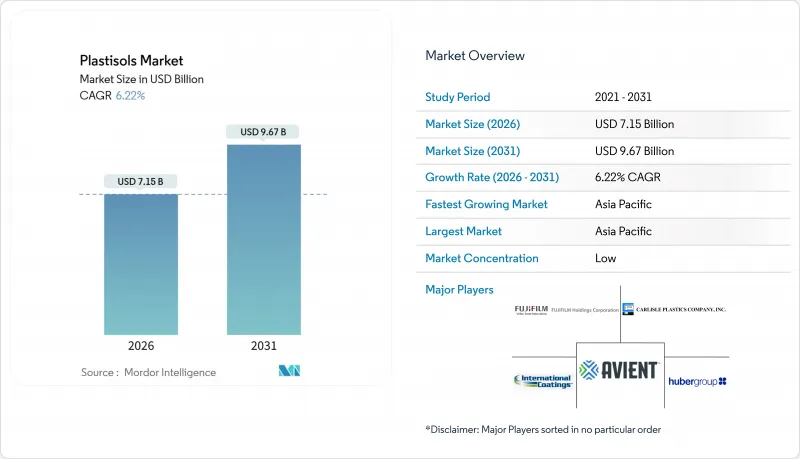
This report is Segmented by Application (Adhesives and Sealants, Paints and Coatings, Printing Inks, Moldings, and Other Applications), End-User Industry (Building and Construction, Transportation, Textiles, Appliances and Machines, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Plastisols Market Trends and Insights
Construction Boom Driving Coatings and Sealants Demand
Saudi Arabia's Vision 2030 emphasizes the use of flexible plastisol sealants, ideal for the region's high-temperature desert climate. In Brazil, an infrastructure initiative is driving up the demand for plastisol roofing membranes and bridge-joint compounds. ASEAN's spending on protective coatings was bolstered by AkzoNobel's takeover of Kansai Paint's assets in Southeast Asia and Jotun's expansion of capacity in Indonesia. Coated-steel roofing and cladding increasingly prefer plastisol, as its impact resistance justifies the premium over polyester finishes. However, macro-projects in Argentina face challenges due to currency fluctuations and delays in import licenses, curbing short-term growth prospects.
Expansion of Textile Screen-Printing Capacity in Asia-Pacific
India's Production Linked Incentive scheme has infused significant investment into the textile manufacturing sector. This, in conjunction with seven PM MITRA mega-parks, aims to boost the domestic screen-printing output. China's printing-and-dyeing sector saw a rise in export volume in 2025, despite a dip in unit prices. This trend hints at capacity defense strategies, which, in turn, amplify ink consumption. A reduction in GST on man-made fiber has slashed input costs. This move promotes the use of plastisol inks, which cure at lower temperatures, potentially cutting per-run energy consumption. Vietnam and Bangladesh are poised to drive up the demand for plastisol formulations as they target substantial textile exports by 2030. Inks certified under GOTS and RoHS are gaining traction among regional buyers, steering formulators towards premium non-phthalate chemistries.
Stringent PVC and Phthalate Regulations (REACH, RoHS, CPSIA)
Effective 2023, ECHA's bans on DINP, DIDP, and DnOP in toys and childcare goods necessitate dual inventories, inflating working-capital needs. In the U.S., TSCA notifications introduce administrative burdens, with small compounders incurring costs for mandated third-party phthalate testing. China's GB 6675 aligns with European standards, and India is on the verge of finalizing its IS 9873 rules, underscoring a global regulatory convergence. The rising complexity of compliance has fueled mergers and acquisitions activity, highlighted by Novolex's acquisition of Pactiv Evergreen in 2024, aiming to bolster regulatory spending and intensify competition in the mid-tier market.
Other drivers and restraints analyzed in the detailed report include:
- Automotive Corrosion-Protection and Lightweighting Needs
- Shift to Phthalate-Free Plastisols for Toys and Childcare Goods
- Volatile PVC Resin and Plasticizer Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Printing Inks led 2025 revenue with 33.24% plastisol market share and will maintain the top position by expanding at a 7.18% CAGR through 2031. India's PLI incentives, China's aggressive export strategies, and ASEAN's sourcing diversification have fueled a surge in garment-decoration demand. This uptick has led to consistent re-orders for plastisol formulations, known for their opacity and elasticity on cotton and polyester blends. These formulations not only outpace water-based inks in flash-curing speed but also in color saturation. In premium niches, there's a clear preference for phthalate-free, GOTS-approved versions, allowing apparel exporters to seamlessly navigate European chemical-management audits.
The unwavering dominance of screen-printing ensures a steady demand for raw materials, bolstering capacity expansions among global ink manufacturers. The industry's shift towards non-phthalate, partially bio-based chemistries is evident. While Paints and Coatings, Adhesives and Sealants, and Moldings play a smaller role, their strategic importance is undeniable. Automotive underbody coatings, based on plastisol, provide sound-damping and corrosion protection. Meanwhile, dip-molded tool handles and electrical connectors benefit from enhanced thick-film qualities. In high-insolation areas, outdoor signage utilizes UV-resistant plastisol coats, extending its service life.
Complete Report Scope:
- By Application
- Adhesives and Sealants
- Paints and Coatings
- Printing Inks
- Moldings
- Other Applications
- By End-user Industry
- Building and Construction
- Transportation
- Textiles
- Appliances and Machines
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific posted 51.12% of the global plastisol market revenue in 2025 and will climb at a 6.33% CAGR through 2031. India's PLI scheme backs new printing lines, while China, despite facing unit-price erosion, staunchly defends its export volume, collectively bolstering ink sales growth. Construction expenditures in ASEAN fuel a surge in sealant demand, prompting AkzoNobel and Jotun to expand their regional capacities. As Japan and South Korea enhance their automotive corrosion-protection layers, they cater to the burgeoning EV fleets. A reduced GST on synthetic yarn solidifies the region's cost leadership.
North America reaps benefits from a consistent light-vehicle output. With an increasing mix of EVs, each vehicle demands a larger underbody coating area. In response to CPSIA phthalate bans, there's a notable shift towards non-phthalate plastisol in toys and childcare products, bolstering the market share of ISO-certified manufacturers. Mexico's assembly sector capitalizes on tariff-free coatings under the USMCA. Meanwhile, Canadian construction projects require niche roofing applications that must withstand challenging freeze-thaw cycles.
Europe grapples with tempered growth due to REACH restrictions, which necessitate maintaining dual inventories and inflate compliance costs. Stricter CO2 regulations push automakers towards lighter metals, consequently boosting the demand for adhesion-enhanced plastisols. Germany, France, and the UK lead the charge in regional applications spanning automotive, construction, and textile sectors. While Russia faces supply constraints due to sanctions, the Nordics leverage plastisol for offshore wind installations, emphasizing the need for fatigue-resistant coatings.
- Avient Corporation
- Campbell Plastics
- Carlisle Plastics Company
- Chemionics Corporation
- Fujifilm Holdings Corporation
- Huber Group
- International Coatings
- Lancer Group International
- MONARCH COLOR CORPORATION
- PATCHAM
- Polyblend
- PolySol LLC
- Sinclair & Rush, Inc.
- Sushee Coatings
- Uniway Asia Limited
- VITA LIQUID POLYMERS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Construction boom driving coatings and sealants demand
- 4.2.2 Expansion of textile screen-printing capacity in Asia-Pacific
- 4.2.3 Automotive corrosion-protection and lightweighting needs
- 4.2.4 Shift to phthalate-free plastisols for toys and childcare goods
- 4.2.5 Emergence of 3-D-printable and smart-functional plastisols
- 4.3 Market Restraints
- 4.3.1 Stringent PVC and phthalate regulations (REACH, RoHS, CPSIA)
- 4.3.2 Volatile PVC resin and plasticizer feedstock prices
- 4.3.3 Competition from powder and water-borne coatings
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Application
- 5.1.1 Adhesives and Sealants
- 5.1.2 Paints and Coatings
- 5.1.3 Printing Inks
- 5.1.4 Moldings
- 5.1.5 Other Applications
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Transportation
- 5.2.3 Textiles
- 5.2.4 Appliances and Machines
- 5.2.5 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 NORDIC Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Avient Corporation
- 6.4.2 Campbell Plastics
- 6.4.3 Carlisle Plastics Company
- 6.4.4 Chemionics Corporation
- 6.4.5 Fujifilm Holdings Corporation
- 6.4.6 Huber Group
- 6.4.7 International Coatings
- 6.4.8 Lancer Group International
- 6.4.9 MONARCH COLOR CORPORATION
- 6.4.10 PATCHAM
- 6.4.11 Polyblend
- 6.4.12 PolySol LLC
- 6.4.13 Sinclair & Rush, Inc.
- 6.4.14 Sushee Coatings
- 6.4.15 Uniway Asia Limited
- 6.4.16 VITA LIQUID POLYMERS
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

