PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114485

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114485
Fusion Splicer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the fusion splicer market size is expected to grow from USD 735.45 million in 2025 to USD 774.23 million in 2026 and is forecast to reach USD 993.12 million by 2031 at 5.11% CAGR over 2026-2031.
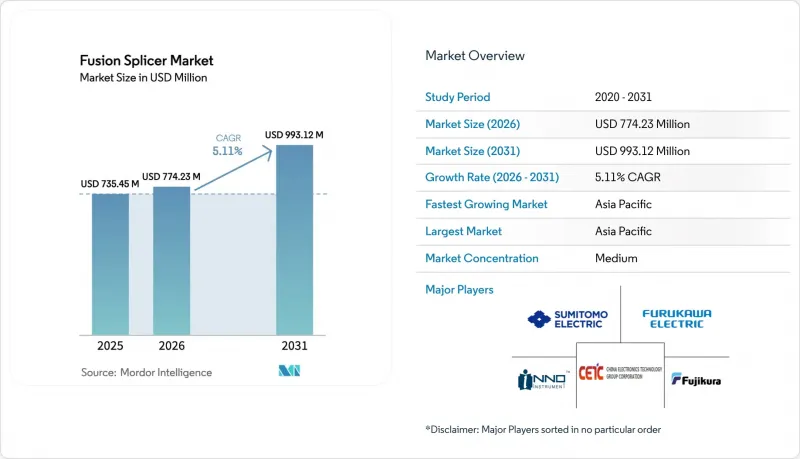
This report is Segmented by Alignment Type (Core Alignment, Cladding Alignment), Product Type (Single-Fiber, Ribbon-Fiber, Specialty-Fiber), End-User (Telecom Operators, Data Centers, Contractors and System Integrators, Aerospace and Defense), Application (Telecommunications, Cable TV, Premises and Enterprise, Research and Specialty), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Fusion Splicer Market Trends and Insights
Surge in Hyperscale Data Center Construction
Hyperscale operators are adding server capacity at a pace that eclipses traditional enterprise build cycles. Each data hall requires tens of thousands of low-loss fiber terminations, and 400 G to 800 G optical transceivers demand parallel fiber ribbons that magnify splice counts. In 2024 hyperscale capacity grew 18%, underpinned by 120 new facilities that collectively stretched global splice demand. Contractors now specify 12- and 24-fiber ribbon units that cut per-splice time to under 90 seconds, improving labor productivity and ensuring consistent optical performance across high-fiber-count interconnects.
Accelerating 5G Backhaul Fiber Deployment
Mobile operators continue to densify mid-band and millimeter-wave cells, with each small-cell node requiring several dedicated fibers. China plans to install fiber to more than 3 million 5G base stations by 2024, a build that will multiply splice points well beyond legacy macro architectures. Portable, battery-driven splicers that withstand aerial and underground conditions are in high demand as field crews race to meet rollout deadlines.
Shortage of Certified Fiber-Splicing Technicians
The United States alone faces a projected deficit of 700,000 qualified fiber technicians through 2029, a gap that prolongs project timelines and inflates labor rates. Europe reports similar hiring delays, with vacancies for installers remaining open twice as long as general construction trades. Although AI-enabled units reduce the learning curve, complex ribbon or specialty fiber tasks still require experienced personnel, limiting deployment velocity in rural and remote builds.
Other drivers and restraints analyzed in the detailed report include:
- Rising Rural Broadband Funds
- Transition From Mechanical to Automated Fusion Splicing
- High Up-Front Equipment Costs for Contractors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Core-alignment systems delivered 63% of fusion splicer market revenue in 2025, underscoring their role in long-haul and metro backbones where ultralow loss is mandatory. Precise imaging aligns fiber cores within sub-micron tolerances, holding attenuation to 0.02-0.05 dB. The fusion splicer market size for core-alignment units is projected to stay ahead as telecom operators refresh existing fleets for AI-assisted versions.
Cladding-alignment demand is nevertheless climbing, expanding at a 5.87% CAGR as quantum sensing and aerospace programs rely on non-standard fiber geometries that preclude core-based alignment. Lower equipment prices, typically 15-20% below core units, help contractors address specialty projects without straining budgets. Manufacturers are now introducing hybrid platforms that toggle between modes, ensuring one chassis covers both mainstream and niche requirements.
Single-fiber models retained 58% of 2025 revenue owing to their versatility across access and enterprise links. Yet ribbon splicers are on a faster 6.12% trajectory because a single 12-fiber splice replaces a dozen sequential terminations, cutting labor time by up to 85%. The fusion splicer market share for ribbon equipment is poised to widen further as 400 G and 800 G transceivers proliferate across hyperscale sites.
Specialty-fiber units occupy a small volume yet command premium pricing, capturing 18% of vendor revenue on just 8% of shipments. Photonic crystal and polarization-maintaining fibers used in defense, quantum, and laser systems drive this niche, and vendors differentiate through programmable arc profiles and extended warranties that align with mission-critical reliability standards.
Complete Report Scope:
- By Alignment Type
- Core Alignment
- Cladding Alignment
- By Product Type
- Single-Fiber Fusion Splicer
- Ribbon-Fiber Fusion Splicer
- Specialty-Fiber Fusion Splicer
- By End-User
- Telecom Operators
- Data Centers
- Contractors and System Integrators
- Aerospace and Defense
- By Application
- Telecommunications
- Cable TV
- Premises and Enterprise
- Research and Specialty Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Rest of Asia-Pacific
- Middle East
- Gulf Cooperation Council
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
the Asia-Pacific accounted for 42.1% of 2025 revenue. China's operators added 65 million new fiber-to-the-home lines in 2024, while India's BharatNet targets village-level connectivity by 2026. Japan, South Korea, and Singapore focus on 10-gigabit passive optical network upgrades that require low-loss re-splicing at distribution hubs. Emerging Southeast Asian economies such as Indonesia and Vietnam are scaling mobile backhaul, favoring ruggedized portable units for aerial and underground cable runs.
North America is the largest regional market, coupling rural buildouts with relentless data-center additions. BEAD funding ensures multi-year equipment orders from contractors expanding fiber to unserved communities, and hyperscale operators keep ribbon splicer demand elevated around Ashburn, Phoenix, and Columbus clusters. Canada's Universal Broadband Fund mirrors this pattern, especially in provinces with harsh winters that require durable field hardware.
Europe presents a patchwork. Scandinavia approaches universal fiber penetration, shifting vendor focus to replacement cycles and ribbon upgrades in data centers. Southern and Eastern European markets lag, but EU Digital Decade targets gigabit coverage for all households by 2030, translating into accelerated purchases as national programs unlock grants. The Middle East and Africa trail in absolute volume yet post one of the steepest growth slopes, propelled by smart-city mega-projects in the Gulf and 5G backhaul across select African metros where operators migrate traffic from congested microwave links to fiber.
- Fujikura Ltd.
- Sumitomo Electric Industries, Ltd.
- Furukawa Electric Co., Ltd.
- INNO Instrument Inc.
- Ilsintech Co., Ltd.
- AFL Telecommunications LLC
- Corning Incorporated
- 3SAE Technologies, Inc.
- UCL Swift Co., Ltd.
- Darkhorsechina (Beijing) Telecom Technology Co., Ltd.
- Nanjing Jilong Optical Communication Co., Ltd.
- Shenzhen Ruiyan Communication Equipment Co., Ltd.
- Signal Fire Technology Co., Ltd.
- Shanghai Xianghe Optical Communication Co., Ltd.
- COMWAY Technology LLC
- Skycom Fibre Ltd.
- GAO Tek Inc.
- Thorlabs, Inc.
- Viavi Solutions Inc.
- EXFO Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating 5G Backhaul Fiber Deployment
- 4.2.2 Rising Rural Broadband Funds in North America and Asia-Pacific
- 4.2.3 Surge in Hyperscale Data Center Construction
- 4.2.4 Transition From Mechanical to Automated Fusion Splicing
- 4.2.5 Adoption of AI-Enabled Self-Aligning Splicers
- 4.2.6 Growing Use of Specialty Fibers in Quantum and Sensing Applications
- 4.3 Market Restraints
- 4.3.1 High Up-Front Equipment Costs for Contractors
- 4.3.2 Shortage of Certified Fiber-Splicing Technicians
- 4.3.3 Price Pressure From Low-Cost Chinese Entrants
- 4.3.4 Volatility in Rare-Earth Electrode Materials
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Alignment Type
- 5.1.1 Core Alignment
- 5.1.2 Cladding Alignment
- 5.2 By Product Type
- 5.2.1 Single-Fiber Fusion Splicer
- 5.2.2 Ribbon-Fiber Fusion Splicer
- 5.2.3 Specialty-Fiber Fusion Splicer
- 5.3 By End-User
- 5.3.1 Telecom Operators
- 5.3.2 Data Centers
- 5.3.3 Contractors and System Integrators
- 5.3.4 Aerospace and Defense
- 5.4 By Application
- 5.4.1 Telecommunications
- 5.4.2 Cable TV
- 5.4.3 Premises and Enterprise
- 5.4.4 Research and Specialty Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Gulf Cooperation Council
- 5.5.5.2 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Fujikura Ltd.
- 6.4.2 Sumitomo Electric Industries, Ltd.
- 6.4.3 Furukawa Electric Co., Ltd.
- 6.4.4 INNO Instrument Inc.
- 6.4.5 Ilsintech Co., Ltd.
- 6.4.6 AFL Telecommunications LLC
- 6.4.7 Corning Incorporated
- 6.4.8 3SAE Technologies, Inc.
- 6.4.9 UCL Swift Co., Ltd.
- 6.4.10 Darkhorsechina (Beijing) Telecom Technology Co., Ltd.
- 6.4.11 Nanjing Jilong Optical Communication Co., Ltd.
- 6.4.12 Shenzhen Ruiyan Communication Equipment Co., Ltd.
- 6.4.13 Signal Fire Technology Co., Ltd.
- 6.4.14 Shanghai Xianghe Optical Communication Co., Ltd.
- 6.4.15 COMWAY Technology LLC
- 6.4.16 Skycom Fibre Ltd.
- 6.4.17 GAO Tek Inc.
- 6.4.18 Thorlabs, Inc.
- 6.4.19 Viavi Solutions Inc.
- 6.4.20 EXFO Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

