PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114535

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114535
Laboratory Proficiency Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the laboratory proficiency testing market size is expected to grow from USD 1.58 billion in 2025 to USD 1.68 billion in 2026 and is forecast to reach USD 2.26 billion by 2031 at 6.18% CAGR over 2026-2031.
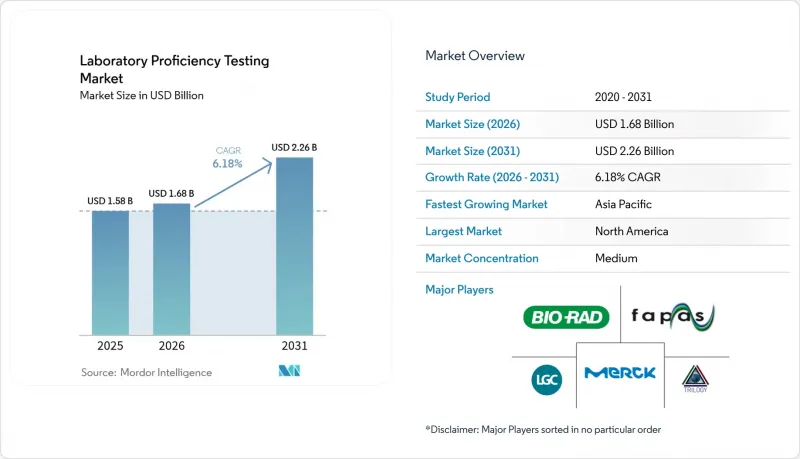
This report is Segmented by Industry Type (Clinical Diagnostics, Microbiology, Pharmaceutical & Biologics and More), by Technology (Chromatography, Spectrophotometry, Immunoassays and More), by Provider Type (Independent / Third-Party Providers, Instrument-Manufacturer Programs, and More) and Geography (North- America, Europe and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Laboratory Proficiency Testing Market Trends and Insights
Stricter ISO/IEC 17025 & 17043 Accreditation Mandates
Global alignment toward ISO/IEC 17025:2017 and the 2023 update of ISO/IEC 17043 pushes laboratories to demonstrate quantitative competence instead of procedural compliance. Hong Kong's HKAS adopted the new 17043 criteria in November 2024, while Canada's Standards Council enforced parallel upgrades in May 2024. Accreditation bodies may suspend non-conforming labs, spurring consolidation and increasing demand for statistically robust external quality assessment. As ISO convergence expands to emerging markets, the laboratory proficiency testing market gains momentum through mandatory participation clauses tied to accreditation renewals.
Growing Clinical Diagnostics Volume Amid Chronic Disease Burden
Rising incidence of diabetes, cardiovascular disease and oncology testing has increased the average test menu per U.S. laboratory and extended participation to next-generation sequencing panels. CLIA rules obligate all moderate- and high-complexity labs to enroll in approved programs, and CMS authorized new cytology schemes for 2025. Large networks such as Quest Diagnostics reported USD 9.3 billion revenue in 2023, highlighting how scale multiplies proficiency testing subscriptions across multiple sites. The laboratory proficiency testing market therefore scales directly with diagnostic volume, particularly where advanced molecular assays require tailored external quality assessment.
High Subscription Costs for Small & Mid-Size Laboratories
Independent studies by the Association of Public Health Laboratories indicate that annual proficiency testing outlays can exceed 3% of gross revenue for low-volume labs, constraining participation particularly in developing economies. The termination of the USP scheme in August 2023 raised switching costs, underscoring how market exits can inflate pricing pressure on smaller facilities .
Other drivers and restraints analyzed in the detailed report include:
- Tightening Food & Water-Safety Regulations Worldwide
- Biologics Manufacturing Boom Demanding Validated Analytical Methods
- Sample Logistics & Stability Hurdles in Emerging Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Clinical Diagnostics held 38.21% of laboratory proficiency testing market share in 2025 as CLIA mandates coupled with rising chronic disease testing volumes sustained program enrollment. Laboratories routinely parcel the laboratory proficiency testing market size for hematology, chemistry and infectious disease panels across multiple providers, reinforcing predictable renewal revenue. Meanwhile, Pharmaceutical & Biologics posted the quickest 7.32% CAGR, propelled by stringent analytical method validation in monoclonal antibody potency and mRNA vaccine release.
The laboratory proficiency testing industry is also witnessing consistent microbiology uptake driven by dual demand from food safety and clinical bacteriology labs. Cosmetics & Personal Care inquiries grew after the FDA's MoCRA enforcement date in July 2024, prompting new schemes for heavy metals and microbial challenge. Cannabis and psychedelics testing rounds widened the application base, indicating that differentiated external quality assessment can precede formal regulatory edicts in emerging niches.
Complete Report Scope:
- By Industry
- Clinical Diagnostics
- Microbiology
- Pharmaceutical & Biologics
- Food & Animal Feed
- Water & Environmental
- Commercial Beverages
- Cosmetics & Personal Care
- Others
- By Technology
- Chromatography
- Spectrophotometry
- Immunoassays
- PCR & Molecular Methods
- Cell Culture-based Assays
- Other Emerging Techniques
- By Provider Type
- Independent / Third-party Providers
- Instrument-Manufacturer Programs
- Government & Accreditation-body Schemes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America generated 41.98% of 2025 revenues, anchored by CLIA-based compulsory enrollment of more than 260,000 U.S. laboratories and by Canada's harmonized accreditation system. The region's laboratory proficiency testing market also benefits from niche demand in cannabis testing as state-level legalization continues. Consolidation among commercial super-networks such as Labcorp and BioReference supports volume robustness even as unit pricing comes under negotiation.
Asia-Pacific records the fastest 7.96% CAGR to 2031, reflecting China's CNAS accreditation requirements, Japan's Food Sanitation Act testing obligations and India's expanding bio-manufacturing corridor. APAC mutual recognition arrangements further enlarge cross-border acceptance, lowering redundant test costs and raising adoption of sophisticated external quality controls. Logistics constraints remain a drag in parts of South-East Asia, yet digital reporting platforms partially offset physical distribution gaps.
Europe sustains mature albeit steady growth under EN ISO/IEC 17025 implementation and evolving monographs such as the European Pharmacopoeia's cannabis flower inclusion in July 2024. Brexit complexities marginally elevate administrative overhead but have not dampened the laboratory proficiency testing market given maintained mutual recognition agreements. Latin America and the Middle East & Africa represent long-term upside once cold-chain and customs bottlenecks resolve, with regional governments already signaling alignment with ISO norms.
- College of American Pathologists (CAP)
- LGC Group
- Bio-Rad Laboratories
- Randox Laboratories
- AOAC International
- American Proficiency Institute
- Waters ERA (Waters Corp.)
- UK NEQAS
- Fera Science (Fapas)
- Proficiency Testing Australia
- QACS Labs
- QSE GmbH
- European Proficiency Testing Service (EPTIS)
- AAFCO Proficiency Testing Program
- Inpas SL
- Bipea
- NSI Lab Solutions
- Global Proficiency Ltd.
- Phenova
- Absolute Standards Inc.
- FSS Proficiency Testing
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter ISO/IEC 17025 & 17043 Accreditation Mandates
- 4.2.2 Growing Clinical Diagnostics Volume Amid Chronic Disease Burden
- 4.2.3 Tightening Food & Water-Safety Regulations Worldwide
- 4.2.4 Biologics Manufacturing Boom Demanding Validated Analytical Methods
- 4.2.5 Legalization Of Cannabis & Psychedelics Spurring Niche PT Schemes
- 4.2.6 Rise Of Remote / At-Home Testing Creating Digital PT Opportunities
- 4.3 Market Restraints
- 4.3.1 High Subscription Costs For Small & Mid-Size Laboratories
- 4.3.2 Sample Logistics & Stability Hurdles In Emerging Regions
- 4.3.3 Consolidation-Driven Discontinuation Of Key PT Programs
- 4.3.4 Data-Privacy Rules Limiting Inter-Lab Data Sharing Analytics
- 4.4 Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Threat of Substitutes
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Bargaining Power of Suppliers
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Industry
- 5.1.1 Clinical Diagnostics
- 5.1.2 Microbiology
- 5.1.3 Pharmaceutical & Biologics
- 5.1.4 Food & Animal Feed
- 5.1.5 Water & Environmental
- 5.1.6 Commercial Beverages
- 5.1.7 Cosmetics & Personal Care
- 5.1.8 Others
- 5.2 By Technology
- 5.2.1 Chromatography
- 5.2.2 Spectrophotometry
- 5.2.3 Immunoassays
- 5.2.4 PCR & Molecular Methods
- 5.2.5 Cell Culture-based Assays
- 5.2.6 Other Emerging Techniques
- 5.3 By Provider Type
- 5.3.1 Independent / Third-party Providers
- 5.3.2 Instrument-Manufacturer Programs
- 5.3.3 Government & Accreditation-body Schemes
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 United Kingdom
- 5.4.2.2 Germany
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 College of American Pathologists (CAP)
- 6.3.2 LGC Limited
- 6.3.3 Bio-Rad Laboratories
- 6.3.4 Randox Laboratories
- 6.3.5 AOAC International
- 6.3.6 American Proficiency Institute
- 6.3.7 Waters ERA (Waters Corp.)
- 6.3.8 UK NEQAS
- 6.3.9 Fera Science (Fapas)
- 6.3.10 Proficiency Testing Australia
- 6.3.11 QACS Labs
- 6.3.12 QSE GmbH
- 6.3.13 European Proficiency Testing Service (EPTIS)
- 6.3.14 AAFCO Proficiency Testing Program
- 6.3.15 Inpas SL
- 6.3.16 Bipea
- 6.3.17 NSI Lab Solutions
- 6.3.18 Global Proficiency Ltd.
- 6.3.19 Phenova
- 6.3.20 Absolute Standards Inc.
- 6.3.21 FSS Proficiency Testing
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

