PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114624

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114624
Calcium Channel Blocker - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, calcium channel blocker market size in 2026 is estimated at USD 17.79 billion, growing from 2025 value of USD 16.92 billion with 2031 projections showing USD 22.91 billion, growing at 5.18% CAGR over 2026-2031.
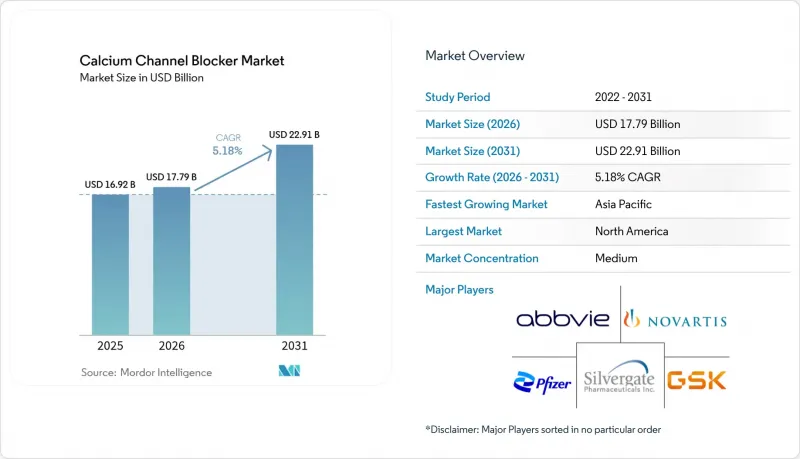
This report is Segmented by Drug Class (Dihydropyridines and Non-Dihydropyridines), Indication (Hypertension, and More), Formulation (Immediate-Release, and More), Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Other Distribution Channels), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Calcium Channel Blocker Market Trends and Insights
Growing Geriatric Population Demanding Long-Term Antihypertensive Therapy
The proportion of adults aged >= 65 years rose to 11% globally in 2024 and is climbing fastest in Japan and Southern Europe. Stroke risk doubles every decade after 55, and calcium channel blockers demonstrate durable protection without compromising renal function. A real-world study that followed 714,000 hypertensive seniors for 2.5 years linked continuous amlodipine therapy to lower dementia incidence relative to non-users. These overlapping cardiovascular and cognitive benefits encourage geriatricians to prioritize once-daily dihydropyridines in complex polypharmacy regimens, strengthening the growth trajectory of the calcium channel blocker market.
Increasing Availability of Affordable Generic Formulations
Amlodipine lost exclusivity in most territories years ago, shaving up to 70% off treatment costs and widening access among low-income patients. India and China now account for a majority of global API output, yet freight disruptions in 2025 briefly pushed ex-works prices up by double digits. Despite episodic volatility, therapeutic equivalence studies confirm that generic amlodipine delivers identical blood-pressure control, reassuring clinicians and supporting high substitution rates. Margin pressure from generics prompts originators to defend share through lifecycle strategies such as polypill launches and controlled-release reformulations.
Stringent Regulatory Scrutiny Over Nitrosamine Impurities
The US FDA's 2024 guidance requires every manufacturer to map potential nitrosamine formation pathways, tighten specification limits, and validate mitigation steps before batch release. Similar expectations now apply across Europe and Japan. Compliance forces companies to upgrade analytical methods, vet excipient suppliers, and retrofit older facilities, elevating cost of goods. Voluntary suspensions during investigation phases have temporarily restricted supply, although most firms ultimately resume production once corrective actions satisfy regulators. The extra burden trims near-term profitability but is unlikely to derail the long-term trajectory of the calcium channel blocker market.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Use of Fixed-Dose Combination Therapies to Improve Compliance
- Emerging Clinical Evidence Supporting Neuroprotective Applications
- Supply Chain Vulnerabilities in Active Pharmaceutical Ingredient Sourcing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dihydropyridines held 61.78% of revenue in 2025, reflecting prescriber familiarity and once-daily convenience for drugs such as amlodipine, cilnidipine, and felodipine. The calcium channel blocker market size for this class is forecast to achieve mid-single-digit growth through 2031 as payers widen access to generics and physicians exploit vascular selectivity to avoid conduction disturbances. Uptake remains particularly strong in Asia-Pacific, where guideline committees often recommend amlodipine as the preferred starter drug for patients of any age group.
Non-dihydropyridines, comprising verapamil and diltiazem, are projected to post a 7.12% CAGR, outpacing the broader calcium channel blocker market. Their dual vascular and nodal activity makes them attractive in atrial tachyarrhythmias, postoperative rate control, and concomitant angina. Growth also benefits from research into N- and L-type dual inhibitors like cilnidipine that may reduce sympathetic overdrive in chronic kidney disease. Innovation therefore supports diversification without undermining the primacy of traditional dihydropyridines.
Hypertension accounted for 70.65% of 2025 prescriptions, preserving first-line status across North America, Europe, and most of Asia. Evidence that L-type blockade cuts stroke risk more than beta-blockade sustains confidence among primary-care physicians. In volume terms, the calcium channel blocker market size for hypertension should maintain a low-mid single-digit trajectory despite therapeutic inertia and guideline updates that encourage starting two agents at once.
Neurological disorders are on track to expand at an 7.86% CAGR to 2031, the highest among all use cases. Real-world analyses link chronic exposure to a 20% lower Parkinson's disease incidence, and randomised trials are evaluating verapamil for cluster headache and cilnidipine for neurogenic hypertension. Small but growing off-label demand therefore provides an incremental avenue of diversification within the calcium channel blocker market.
Complete Report Scope:
- By Drug Class
- Dihydropyridines
- Amlodipine
- Nifedipine
- Felodipine & Others
- Non-Dihydropyridines
- Phenylalkylamine (Verapamil)
- Benzothiazepine (Diltiazem)
- Dihydropyridines
- By Indication
- Hypertension
- Angina Pectoris
- Arrhythmia
- Raynaud's Phenomenon
- Neurological Disorders (Migraine, SAH)
- Other Indications
- By Formulation
- Immediate-Release
- Extended / Controlled-Release
- Fixed-Dose Combinations
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Other Distribution Channels
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 39.12% of global turnover in 2025 on the back of high insurance coverage and rapid adoption of novel polypills. Prescription audits show that calcium channel blocker use among Black patients jumped 41% between 2018-2019 compared with earlier years after the JNC 8 committee advocated the class as first-line therapy. Generic intensification offsets price erosion, while brand extensions like once-weekly patches attract niche cohorts with adherence challenges. Continuous medical education reinforces class familiarity, cushioning the calcium channel blocker market from short-term competition.
Europe ranked second, characterized by cost-containment and proactive safety surveillance. Class 2 recalls for amlodipine tablets in early 2025 underscored the region's vigilance in microbial quality management. Health technology appraisal agencies such as NICE routinely favour low-priced generics but still reimburse branded combinations when economic models demonstrate fewer cardiovascular events. The advent of nifedipine-lidocaine ointment for chronic anal fissure adds a novel non-cardiac dimension, diversifying regional demand.
Asia-Pacific remains the fastest-growing territory at 6.18% CAGR. The twin forces of epidemiological transition and public insurance expansion elevate annual prescription volumes. Local firms in China and India supply competitively priced APIs and finished doses, ensuring affordability. Observational studies across 12 countries confirm that calcium channel blockers constitute the most frequently prescribed antihypertensive class, although intra-regional heterogeneity persists. Government bulk-purchase schemes continue to widen patient reach, supplying structural growth to the calcium channel blocker market.
Elsewhere, Latin America and the Middle East & Africa record steady uptake as urbanization increases cardiovascular risk. International donor programs that supply essential antihypertensive drugs to remote clinics enlarge the still-small baseline, contributing additional incremental units.
- Abbvie
- Alvogen
- Arbor Pharmaceuticals
- Bausch Health
- Covis Pharma
- Exela Pharma Sciences
- GlaxoSmithKline
- Lupin
- Novartis
- Pfizer
- Sanofi
- Silvergate Pharmaceuticals
- Teva Pharmaceutical Industries
- Viatris
- Sun Pharma Industries Ltd.
- Aurobindo Pharma Ltd.
- Cipla
- Hikma Pharmaceuticals
- Zydus Lifesciences Ltd.
- Daiichi Sankyo Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Hypertension and Cardiovascular Disorders
- 4.2.2 Growing Geriatric Population Demanding Long-Term Antihypertensive Therapy
- 4.2.3 Increasing Availability of Affordable Generic Formulations
- 4.2.4 Expanding Use of Fixed-Dose Combination Therapies to Improve Compliance
- 4.2.5 Emerging Clinical Evidence Supporting Neuroprotective Applications
- 4.2.6 Government Initiatives for Universal Health Coverage in Emerging Markets
- 4.3 Market Restraints
- 4.3.1 Stringent Regulatory Scrutiny over Nitrosamine Impurities
- 4.3.2 Adverse Effect Profile Leading to Therapy Switches
- 4.3.3 Supply Chain Vulnerabilities in Active Pharmaceutical Ingredient Sourcing
- 4.3.4 Competitive Pressure from Novel Cardiovascular Drug Classes
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat Of New Entrants
- 4.6.2 Bargaining Power Of Buyers
- 4.6.3 Bargaining Power Of Suppliers
- 4.6.4 Threat Of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Drug Class
- 5.1.1 Dihydropyridines
- 5.1.1.1 Amlodipine
- 5.1.1.2 Nifedipine
- 5.1.1.3 Felodipine & Others
- 5.1.2 Non-Dihydropyridines
- 5.1.2.1 Phenylalkylamine (Verapamil)
- 5.1.2.2 Benzothiazepine (Diltiazem)
- 5.1.1 Dihydropyridines
- 5.2 By Indication
- 5.2.1 Hypertension
- 5.2.2 Angina Pectoris
- 5.2.3 Arrhythmia
- 5.2.4 Raynaud's Phenomenon
- 5.2.5 Neurological Disorders (Migraine, SAH)
- 5.2.6 Other Indications
- 5.3 By Formulation
- 5.3.1 Immediate-Release
- 5.3.2 Extended / Controlled-Release
- 5.3.3 Fixed-Dose Combinations
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies
- 5.4.3 Other Distribution Channels
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 Alvogen
- 6.3.3 Arbor Pharmaceuticals LLC
- 6.3.4 Bausch Health Companies Inc.
- 6.3.5 Covis Pharma BV
- 6.3.6 Exela Pharma Sciences LLC
- 6.3.7 GlaxoSmithKline plc
- 6.3.8 Lupin Pharmaceuticals Inc.
- 6.3.9 Novartis AG
- 6.3.10 Pfizer Inc.
- 6.3.11 Sanofi SA
- 6.3.12 Silvergate Pharmaceuticals Inc.
- 6.3.13 Teva Pharmaceutical Industries Ltd.
- 6.3.14 Viatris Inc.
- 6.3.15 Sun Pharma Industries Ltd.
- 6.3.16 Aurobindo Pharma Ltd.
- 6.3.17 Cipla Ltd.
- 6.3.18 Hikma Pharmaceuticals plc
- 6.3.19 Zydus Lifesciences Ltd.
- 6.3.20 Daiichi Sankyo Co. Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

