PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114632

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114632
Global Cardiac Arrest Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
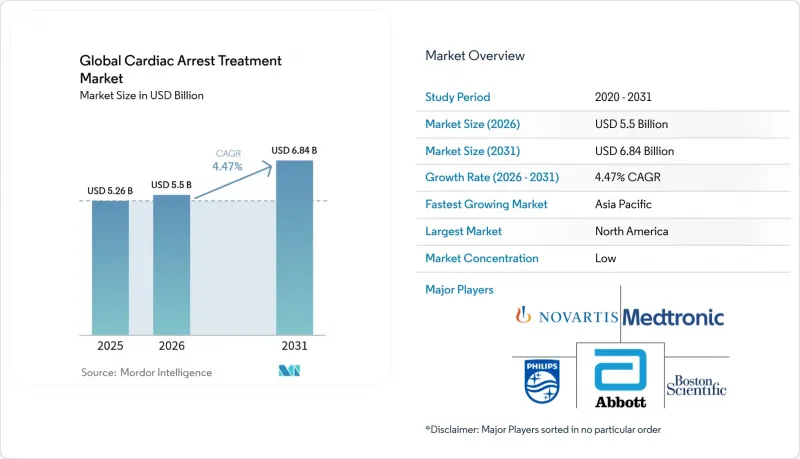
According to Mordor Intelligence, the global cardiac arrest treatment market size in 2026 is estimated at USD 5.5 billion, growing from 2025 value of USD 5.26 billion with 2031 projections showing USD 6.84 billion, growing at 4.47% CAGR over 2026-2031.
This report Segments the Industry Into by Treatment (Devices [Defibrillators, Extracorporeal Membrane Oxygenation (ECMO) and More], Drugs [Class I - Sodium-Channel Blockers, Class II - Beta-Blockers and More]), by Distribution Channel (Hospitals, Pharmacies and More), and Geography (North America, Europe, Asia-Pacific and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cardiac Arrest Treatment Market Trends and Insights
Growing Burden of Sudden Cardiac Arrest & Ageing Populations
Population ageing increases sudden cardiac death incidence, especially among adults over 65. The American Heart Association notes that 356,000 Americans experience out-of-hospital cardiac arrest each year, with survival remaining at 8-10%. Its 2030 Impact Goals target more than 50% bystander CPR and 20% AED use before EMS arrival to offset the 10% survival decline that occurs for every untreated minute. These goals push health systems to procure integrated device ecosystems rather than one-off equipment. Growing recognition of COVID-19-related myocardial micro-scarring in younger age groups further broadens the addressable patient pool. Consequently, the cardiac arrest treatment market continues to prioritize scalable platforms that combine monitoring, predictive software, and therapy delivery in a single continuum of care.
Public-Access Defibrillator Programmes and Legislation
State-mandated AED deployment in schools, sports arenas, and transit hubs expands device density and improves lay-rescuer readiness. South Carolina's Smart Heart Act and Ohio's House Bill 47 require both AED placement and cardiac emergency response plans, lowering legal barriers that once deterred facility managers. The Centers for Disease Control and Prevention offers a 13-point implementation toolkit that standardises procurement and maintenance, while federal proposals to reauthorise the Cardiac Arrest Survival Act strengthen liability protections. Connected AED platforms that feed status data into 911 dispatch networks therefore enjoy higher adoption, especially when bundled with subscription-based training modules.
Product Recalls & Device-Related Adverse Events
Quality lapses remain a central concern. Boston Scientific issued a Class I recall for certain Accolade pacemakers after 832 injuries and 2 deaths were linked to devices entering Safety Mode. Abbott simultaneously recalled HeartMate pump accessories due to power unit failures, triggering the FDA's pilot programme that accelerates public safety alerts for cardiovascular implants. These incidents reduce clinician confidence, delay new-product clearances, and push companies to allocate larger budgets to post-market surveillance, thereby slowing the overall cardiac arrest treatment market.
Other drivers and restraints analyzed in the detailed report include:
- Advances in Implantable & Wearable Defibrillator Technology
- Miniaturised ECMO for Refractory Cardiac Arrest
- High Capital Cost & Reimbursement Gaps in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Devices contributed USD 3.64 billion in 2025, equal to 69.12% of total revenue. Technological leaps like AI-driven arrhythmia prediction and miniaturised ECMO propel this category toward a 6.33% CAGR, keeping the cardiac arrest treatment market size for devices ahead of pharmacologic alternatives. Defibrillators dominate hospital code carts, while drone-mounted AEDs extend reach to remote communities. Portable ECMO platforms win guideline endorsements for refractory cases, and mechanical circulatory support systems such as Impella add incremental hemodynamic stability. FDA approval of the VARIPULSE pulsed-field ablation system confirms regulators' willingness to fast-track high-impact devices, reinforcing vendor confidence in sustained R&D.
The drug segment accounts for the remaining revenue and grows at a slower pace as formulary constraints and generic competition bite. Class III agents like amiodarone remain standard for ventricular arrhythmias, yet shortages of vasopressors such as epinephrine sporadically disrupt critical-care supply chains nih.gov. Investigational mRNA therapies, including AZD8601, mark the first significant mechanistic shift since dronedarone's 2009 launch, but large-scale efficacy data are pending. RNAi approaches that silence arrhythmogenic pathways show promise in preclinical settings, although commercial timelines extend beyond the current forecast window.
Complete Report Scope:
- By Product (Value)
- Devices
- Defibrillators
- Extracorporeal Membrane Oxygenation (ECMO)
- Intra-aortic Balloon Pump (IABP)
- Percutaneous VAD (Impella)
- Other Devices
- Drugs
- Anti-arrhythmic Drugs
- Class I - Sodium-channel Blockers
- Class II - Beta-blockers
- Class III - Potassium-channel Blockers
- Class IV - Calcium-channel Blockers|||
- Others (Digoxin, Adenosine)
- Vasopressors & Inotropes
- Anti-arrhythmic Drugs
- Devices
- By End User (Value)
- Hospitals & Cardiac Centres
- Emergency Medical Services (EMS)
- Home & Alternate Care Settings
- By Region
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- North America
Geography Analysis
North America holds 41.83% of 2025 revenue, benefiting from established EMS protocols, widespread AED saturation, and an FDA ecosystem that offers breakthrough device designations for life-saving tools. Federal liability shields under the Cardiac Arrest Survival Act nurture community responders, and the American Heart Association's targets push states to intensify public-access programmes. Integrated delivery networks negotiate fleet-wide service contracts for defibrillators and monitoring platforms, which sustains predictable replacement cycles. In parallel, large-scale field trials of drone-delivered AEDs in rural regions demonstrate response-time cuts of 4-6 minutes, materially improving neurological outcomes nih.gov.
Asia-Pacific is the fastest-growing territory at 7.55% CAGR, chiefly due to rising cardiovascular mortality and expanded emergency-care funding in urban provinces. Domestic manufacturers from China and Japan increase exports of cost-effective AEDs, challenging Western incumbents on price while meeting International Electrotechnical Commission (IEC) standards. Nevertheless, fragmented reimbursement landscapes still slow uptake of high-ticket ECMO and conduction-system pacing devices, keeping the cardiac arrest treatment market share for expensive capital equipment modest. Multilateral regulatory harmonisation projects, including the Asian Harmonisation Working Party, aim to trim approval times by synchronising dossier requirements-a factor that gradually reduces entry hurdles for global brands.
Europe delivers steady but cautious growth under unified medical-device regulations that emphasise clinical-evidence depth. The region champions clinical quality registries that feed outcome data into guideline updates, guiding hospitals toward evidence-backed purchases. Pilot drone networks in the Netherlands achieved sub-5-minute AED delivery to cardiac arrest scenes, prompting the European Union to fund cross-border replication studies nhs.uk. Budget pressures keep purchasing decisions under health-technology assessment review, yet outcome-based procurement models reward platforms that present clear reductions in out-of-hospital mortality. EU MDR transition costs remain a factor, but established suppliers with robust post-market surveillance capabilities maintain favourable status on tender lists
- Medtronic PLc
- Boston Scientific
- Koninklijke Vjke
- ZOLL Corporation
- Abbott Laboratories
- Stryker
- Nihon Corporation
- BIOTRONIK
- GE Technologies
- Shenzhen Electronic
- MicroPort Corporation
- LivaNova
- Abiomed
- Getinge
- Edwards Corporation
- Masimo Corpoporation
- Amphastar Inc
- Adamis Pharmaceuticals
- Zoll Medical
- Bristol-Myers Squibb
- Teleflex
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing burden of Sudden Cardaic Arrest & ageing Populations
- 4.2.2 Public-access defibrillator programmes and Legislation
- 4.2.3 Advances in implantable & wearable Defibrillator Technology
- 4.2.4 Miniaturised ECMO for refractory cardiac arrest
- 4.2.5 AI-powered rhythm-prediction integrated into EMS workflows
- 4.2.6 mRNA-based anti-arrhythmic therapeutics in pipeline
- 4.3 Market Restraints
- 4.3.1 Product recalls & device-related adverse events
- 4.3.2 High capital cost & reimbursement gaps in emerging markets
- 4.3.3 API shortages for key vasopressors
- 4.3.4 Ethical & regulatory hurdles for field-deployed hypothermia drones
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product (Value)
- 5.1.1 Devices
- 5.1.1.1 Defibrillators
- 5.1.1.2 Extracorporeal Membrane Oxygenation (ECMO)
- 5.1.1.3 Intra-aortic Balloon Pump (IABP)
- 5.1.1.4 Percutaneous VAD (Impella)
- 5.1.1.5 Other Devices
- 5.1.2 Drugs
- 5.1.2.1 Anti-arrhythmic Drugs
- 5.1.2.1.1 Class I - Sodium-channel Blockers
- 5.1.2.1.2 Class II - Beta-blockers
- 5.1.2.1.3 Class III - Potassium-channel Blockers
- 5.1.2.1.4 Class IV - Calcium-channel Blockers|||
- 5.1.2.1.5 Others (Digoxin, Adenosine)
- 5.1.2.2 Vasopressors & Inotropes
- 5.1.2.1 Anti-arrhythmic Drugs
- 5.1.1 Devices
- 5.2 By End User (Value)
- 5.2.1 Hospitals & Cardiac Centres
- 5.2.2 Emergency Medical Services (EMS)
- 5.2.3 Home & Alternate Care Settings
- 5.3 By Region
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Russia
- 5.3.2.7 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 Japan
- 5.3.3.3 India
- 5.3.3.4 South Korea
- 5.3.3.5 Australia
- 5.3.3.6 Rest of Asia-Pacific
- 5.3.4 Middle East & Africa
- 5.3.4.1 GCC
- 5.3.4.2 South Africa
- 5.3.4.3 Rest of Middle East & Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Competition Benchmarking
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Medtronic PLc
- 6.4.2 Boston Scientific
- 6.4.3 Koninklijke Vjke
- 6.4.4 ZOLL Corporation
- 6.4.5 Abbott Laboratories
- 6.4.6 Stryker
- 6.4.7 Nihon Corporation
- 6.4.8 Biotronik
- 6.4.9 GE Technologies
- 6.4.10 Shenzhen Electronic
- 6.4.11 MicroPort Corporation
- 6.4.12 LivaNova PLC
- 6.4.13 Abiomed
- 6.4.14 Getinge AB
- 6.4.15 Edwards Corporation
- 6.4.16 Masimo Corpoporation
- 6.4.17 Amphastar Inc
- 6.4.18 Adamis Pharmaceuticals
- 6.4.19 ZOLL Medical Corporation
- 6.4.20 Bristol Myers Squibb
- 6.4.21 Teleflex Incorporated
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

