PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114637

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114637
Otoscope - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the otoscope market size was valued at USD 206.69 million in 2025 and estimated to grow from USD 215.41 million in 2026 to reach USD 264.81 million by 2031, at a CAGR of 4.22% during the forecast period (2026-2031).
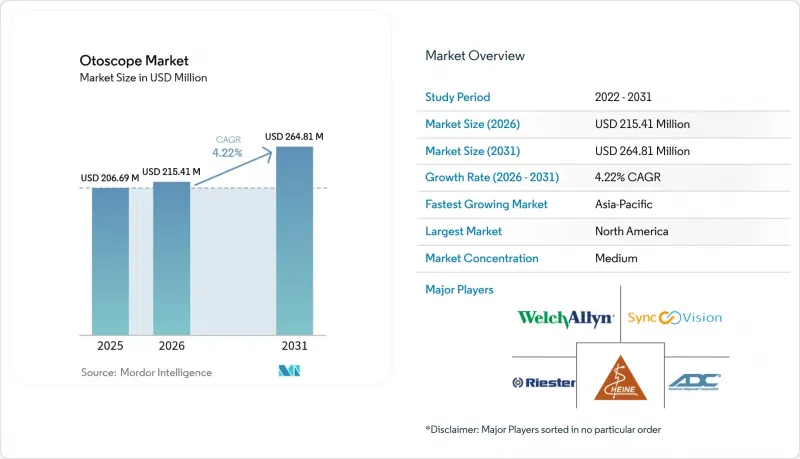
This report is Segmented by Product Type (Standard-Sized Otoscopes, Pocket-Sized Otoscopes), by Portability (Portable, Wall-Mounted), by Power Source (Battery-Operated, Mains-Powered), by Application (Diagnosis, Surgical / Interventional), by End-User (Hospitals, ENT Clinics, Ambulatory Surgery Centers, Others), by Geography (North America, Europe, Asia-Pacific, Middke East and Africa, South America).
Global Otoscope Market Trends and Insights
Growing burden of ENT-related diseases
More precise otologic imaging reduces unnecessary antibiotic use by 50%, as shown with PhotoniCare's OtoSight platform. Despite pneumococcal conjugate vaccines, otitis media prevalence remains stubborn, spotlighting unmet diagnostic needs. High-definition OTO Endoscopes introduced in 2024 deliver superior visuals for chronic otitis media assessment, enhancing diagnostic accuracy at clinics such as Mallige Hospital. Healthcare authorities now link preventable childhood hearing loss to educational performance, strengthening procurement budgets for advanced otoscopes in underserved districts.
Technological advancement in digital & video otoscopes
Optical coherence tomography (OCT) enables cross-sectional tympanic-membrane imaging via the University of Southern California's handheld device, revealing pathologies such as myringitis previously hidden from traditional scopes. Deep residual-recurrent neural networks achieve clinician-level classification of acute otitis media, underpinning AI-enhanced otoscope market growth. On the research horizon, terahertz endoscopes under development at Waseda University promise non-invasive cochlear visualization, suggesting a future leap in ear-disease management.
Social stigma associated with ENT disorders
Cosmetic concerns slow adoption of hearing assistance in traditional societies, despite United States regulatory moves to widen over-the-counter access. Innovative designs like Nuance Audio glasses embed hearing aids into stylish frames, but uptake hinges on public-awareness campaigns and discreet diagnostic options.
Other drivers and restraints analyzed in the detailed report include:
- Rising geriatric population-linked hearing disorders
- Tele-otoscopy adoption in primary care & remote triage
- Shortage of skilled ENT professionals in LMICs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standard-sized instruments controlled 55.26% of the otoscope market in 2025, reflecting clinical preference for high-end optics and durable construction. Procurement departments favor these units for high-volume environments, particularly where accessory compatibility and long-term service contracts matter. Nonetheless, pocket designs will outpace at a 5.09% CAGR, supported by primary-care mobility and community health outreach. Portable OCT scopes from the University of Southern California bridge premium imaging with handheld convenience. Smart-phone-linked sub-segments integrate AI to deliver 93.8% diagnostic sensitivity, cutting training curves and broadening access. Supply-chain savings during a period when production costs have risen to about 20% of revenue favor compact material-efficient builds, reinforcing pocket uptake.
Portable models contributed 72.12% of the otoscope market size in 2025 and will also log the fastest 5.36% CAGR. Their twin leadership position signals a structural shift toward distributed care rather than early-cycle penetration. Adoption surged when video-enabled scopes such as OtoSpec allowed real-time patient education. Battery advances narrow performance gaps with wall-mounted systems and trim installation overhead, making portable units the default choice for tele-medicine networks and school screenings.
Complete Report Scope:
- By Product Type
- Standard-sized Otoscopes
- Pocket-sized Otoscopes
- By Portability
- Portable
- Wall-mounted
- By Power Source
- Battery-operated
- Mains-powered
- By Application
- Diagnosis
- Surgical / Interventional
- By End-User
- Hospitals
- ENT Clinics
- Ambulatory Surgery Centers
- Others
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 37.15% of 2025 revenue, buoyed by insurance coverage, standardized ENT protocols, and expedited U.S. FDA approval pathways that now include a clearer De Novo route for novel otoscopes. Canadian universal coverage embeds otoscopy in primary-care check-ups, whereas Mexico expands device import quotas to modernize public hospitals.
Asia-Pacific posts the swiftest 5.92% CAGR during 2026-2031. China is projected to spend USD 210 billion on medical devices by 2025, spurred by healthy-aging priorities and favorable reimbursement rules. India's National Medical Devices Policy 2023 and its single-window approval system streamline licensing, though delays noted by a 2025 Parliamentary panel have driven some manufacturers to weigh relocation to Vietnam or Malaysia. Japan's advanced physician networks, Australia's universal system, and South Korea's digital-health incentives round out regional momentum.
Europe sustains mid-single-digit growth despite the stricter Medical Device Regulation (MDR) EU 2017/745, which raises clinical-evidence demands and post-market scrutiny. Germany, United Kingdom, and France lead adoption, while Italy and Spain upgrade ENT suites under health-modernization grants. The European Parliament's 2025 call for MDR revisions seeks to avoid supply shortages by setting binding conformity-assessment timelines.
- HEINE Optotechnik
- Welch Allyn (Hill-Rom / Baxter)
- Rudolf Riester
- American Diagnostic
- Kirchner & Wilhelm (KaWe)
- Midmark
- Luxamed
- Olympus
- Sync Vision
- Adam Rouilly
- Fazzini
- AUG Medical
- orlvision GmbH
- OtoNexus Medical Technologies
- Firefly Global
- Spengler SA
- Inventis SRL
- Interacoustics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing burden of ENT-related diseases
- 4.2.2 Technological advancement in digital & video otoscopes
- 4.2.3 Rising geriatric population-linked hearing disorders
- 4.2.4 Expanding healthcare expenditure in emerging economies
- 4.2.5 Tele-otoscopy adoption in primary care & remote triage
- 4.2.6 School-based ear-health screening initiatives
- 4.3 Market Restraints
- 4.3.1 Social stigma associated with ENT disorders
- 4.3.2 Shortage of skilled ENT professionals in LMICs
- 4.3.3 Regulatory delays for smartphone-connected devices
- 4.3.4 Supply-chain dependence on high-precision optics
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Standard-sized Otoscopes
- 5.1.2 Pocket-sized Otoscopes
- 5.2 By Portability
- 5.2.1 Portable
- 5.2.2 Wall-mounted
- 5.3 By Power Source
- 5.3.1 Battery-operated
- 5.3.2 Mains-powered
- 5.4 By Application
- 5.4.1 Diagnosis
- 5.4.2 Surgical / Interventional
- 5.5 By End-User
- 5.5.1 Hospitals
- 5.5.2 ENT Clinics
- 5.5.3 Ambulatory Surgery Centers
- 5.5.4 Others
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Heine Optotechnik GmbH & Co. KG
- 6.3.2 Welch Allyn (Hill-Rom / Baxter)
- 6.3.3 Rudolf Riester GmbH
- 6.3.4 American Diagnostic Corporation
- 6.3.5 Kirchner & Wilhelm (KaWe)
- 6.3.6 Midmark Corporation
- 6.3.7 Luxamed Medizintechnik
- 6.3.8 Olympus Medical Systems
- 6.3.9 Sync Vision
- 6.3.10 Adam Rouilly
- 6.3.11 Fazzini Srl
- 6.3.12 AUG Medical
- 6.3.13 orlvision GmbH
- 6.3.14 OtoNexus Medical Technologies
- 6.3.15 Firefly Global
- 6.3.16 Spengler SA
- 6.3.17 Inventis SRL
- 6.3.18 Interacoustics A/S
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

